

Intersnack Is Buying Utz for $2.9bn After Frito-Lay's Price Cut Reversed Its Share Gains
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
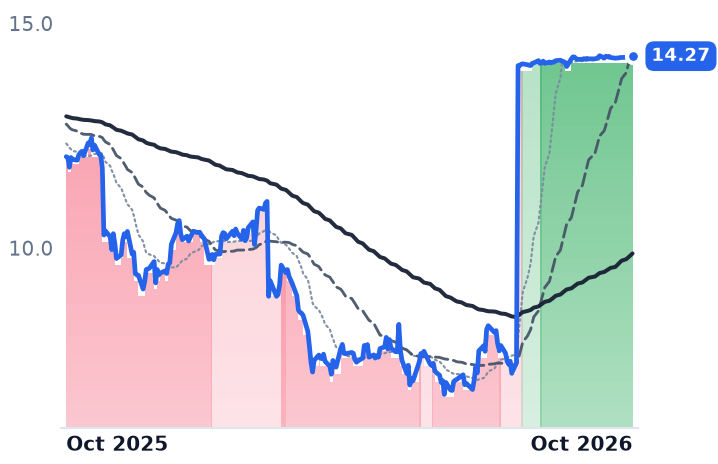
A European family snack group is paying roughly 13.3x consensus 2026 earnings before interest, taxes, depreciation and amortization for the largest pure-play salty-snack maker in the United States — a business the public market was carrying at around half that the day before the bid, at a 91% discount to the agreed price.
The operating numbers do not explain the re-rating. Utz's second-quarter organic net sales rose 1.4%, all of it price: net price realisation added 3.6% while volume and mix subtracted 2.2%, and its measured-channel retail volumes fell 4.6% into a salty-snack category whose volumes grew 1.1%. Margin gains came from productivity, with adjusted gross margin at 33.2% against 31.7%.
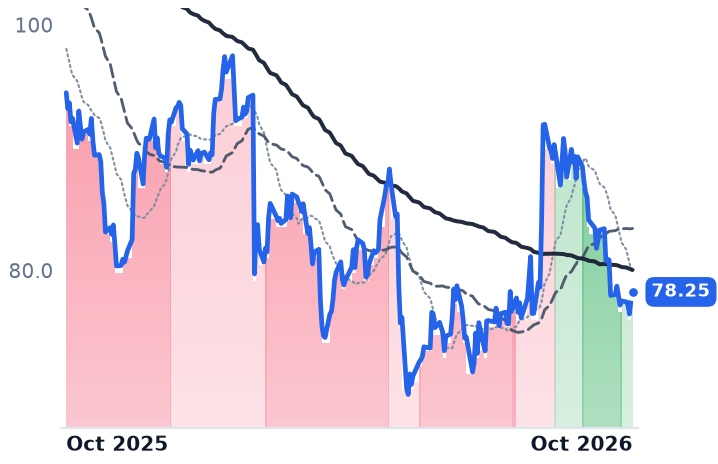
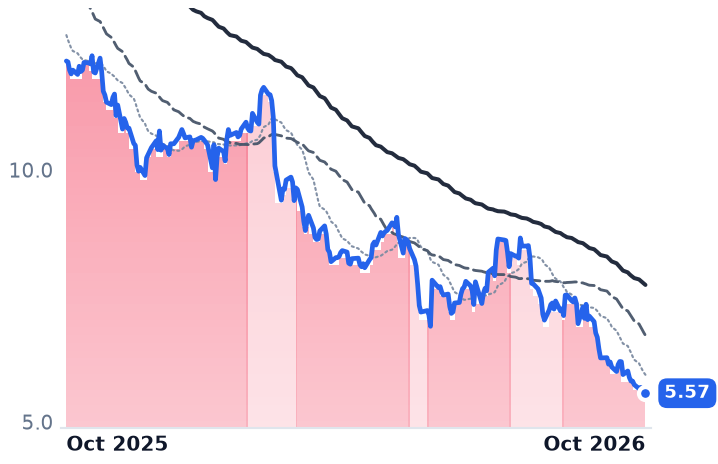
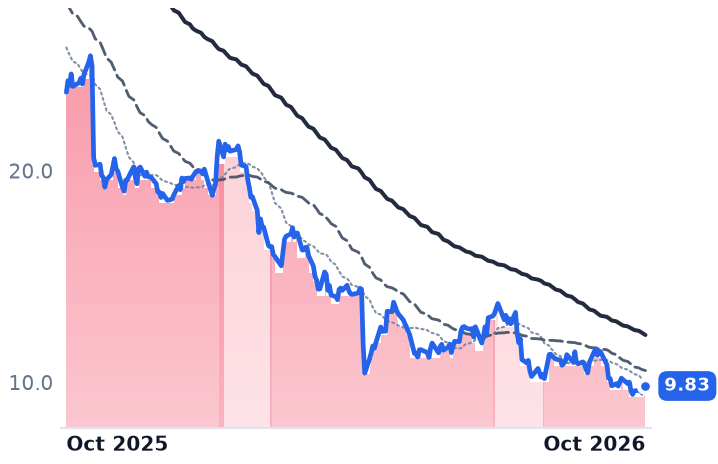
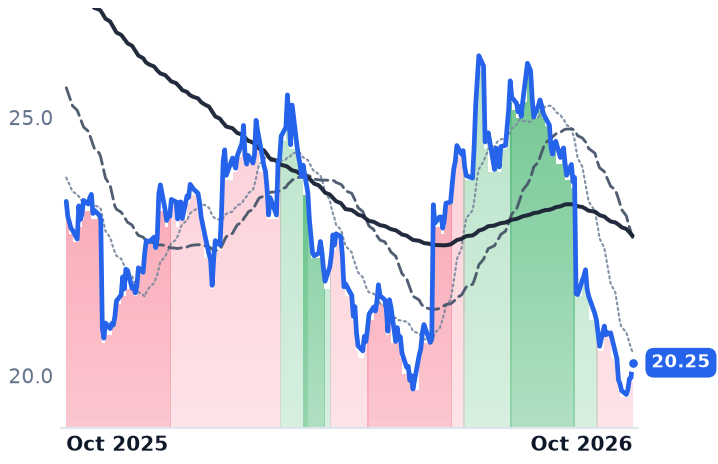
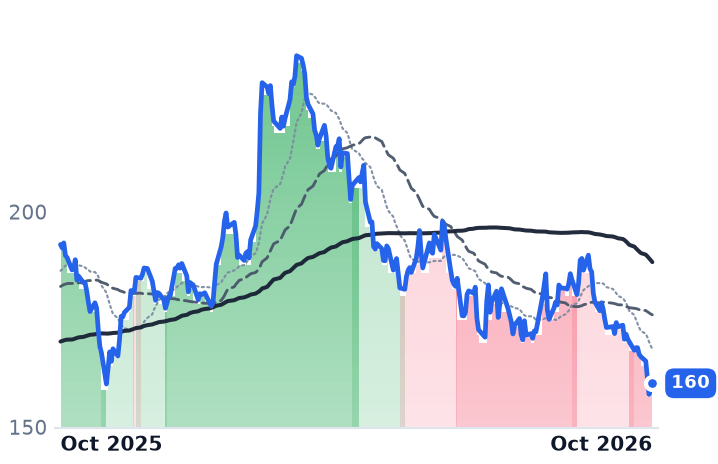
The two snack names without a buyer — J&J Snack Foods and Flowers Foods — are down 19.1% and 57.2% over twelve months, and their own revenue, volume and guidance lines earn it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
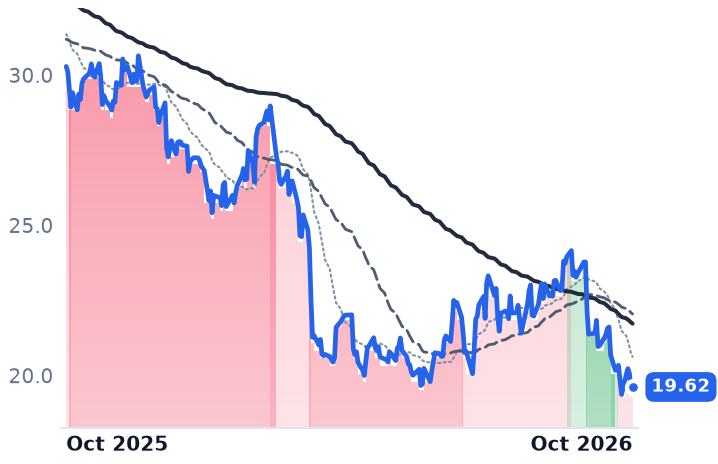
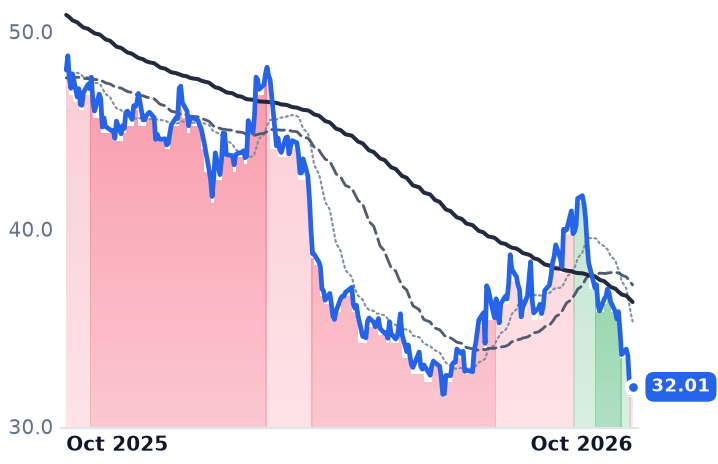
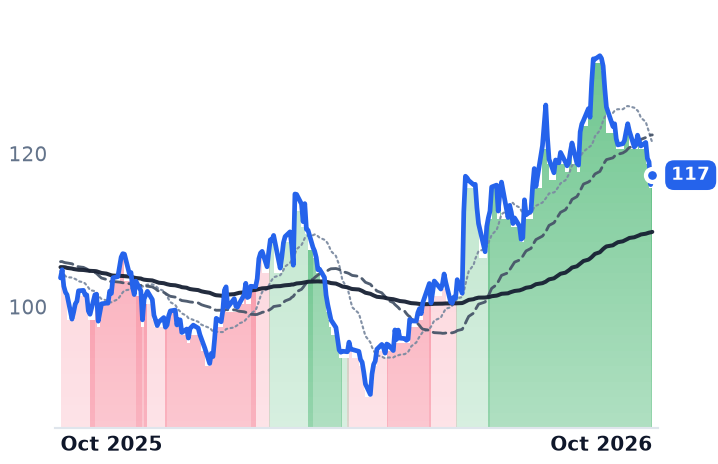
UTZ | Utz Brands | Snacks & Convenience Foods | 🌱 Emerging Bull | +0.4% | +18.6% |
JJSF | J&J Snack Foods | Snacks & Convenience Foods | 🔴 Cont. Bear | −7.0% | −17.2% |
FLO | Flowers Foods | Snacks & Convenience Foods | 🔴 Cont. Bear | −11.2% | −54.2% |
| Compared against · context, not the story | |||||
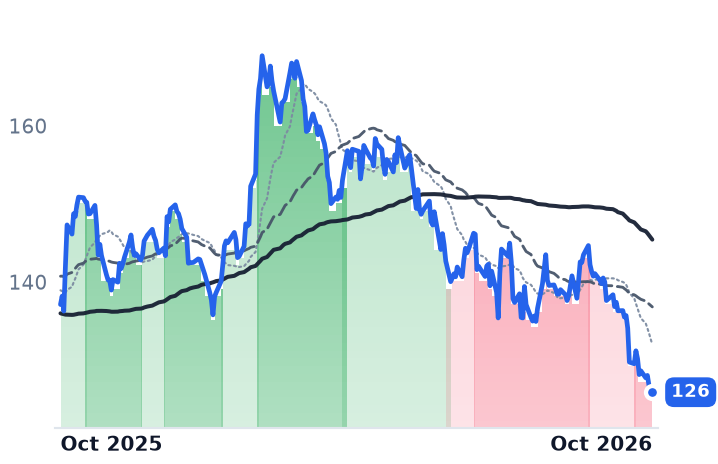
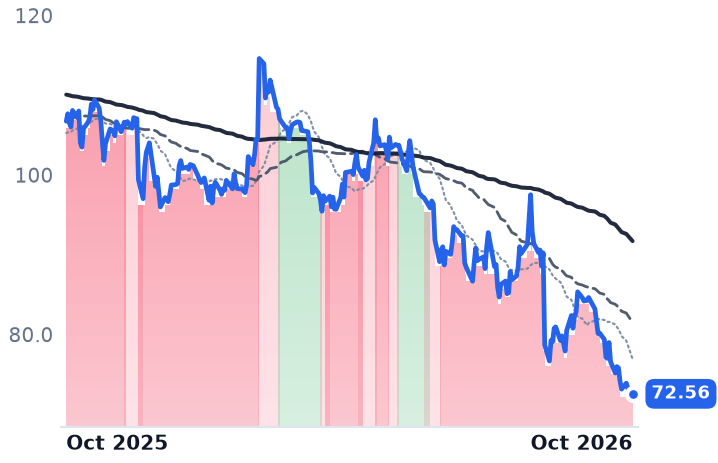
PEP | PepsiCo | Large-Cap Global Beverage | 🔴 Cont. Bear | −8.5% | −8.2% |
CPB | Campbell Soup | Frozen & Prepared Foods | 🔴 Cont. Bear | −8.2% | −35.2% |
GIS | General Mills | Cereals & Breakfast | 🔴 Cont. Bear | −16.4% | −33.4% |
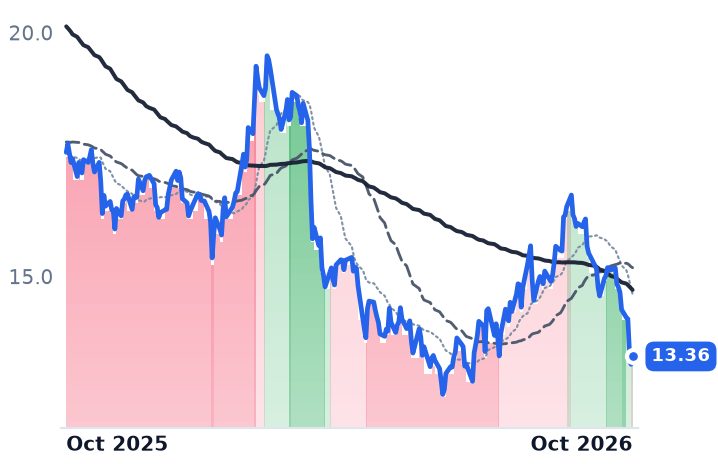
POST | Post | Cereals & Breakfast | 🔴 Cont. Bear | −14.3% | −32.0% |
CAG | Conagra Brands | Frozen & Prepared Foods | 🔴 Cont. Bear | −13.7% | −23.9% |
SMPL | The Simply Good Foods | Nutritional & Wellness Products | 🔴 Cont. Bear | −14.1% | −58.5% |
HRL | Hormel Foods | Meat & Protein Processing | 🔴 Cont. Bear | −6.0% | −13.4% |
HSY | The Hershey | Food Confectioners | 🔴 Cont. Bear | −7.5% | −16.8% |
KHC | The Kraft Heinz | Condiments & Sauces | 🟢 Cont. Bull | −10.7% | −9.3% |
SJM | The J. M. Smucker | Pet Food & Nutrition | 🟢 Cont. Bull | −7.1% | +12.9% |
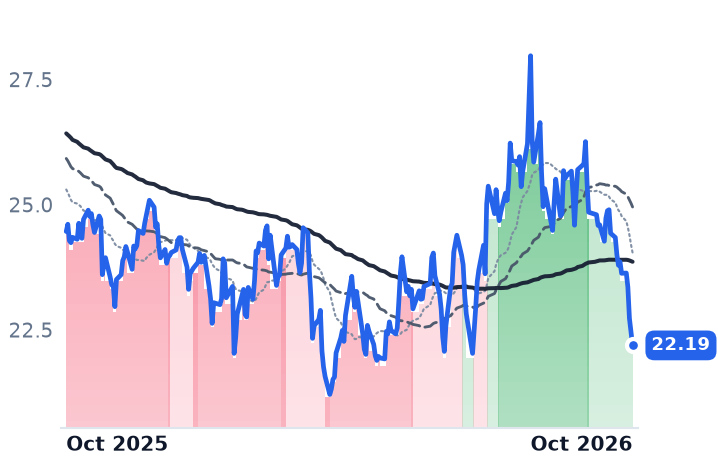
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UTZ | $1.3B | n/m | 18.4x | 0.9x | 0.8x | 4.3x | 4.2x | 22.8x | 4.0% |
JJSF | $1.5B | 29.9x | 18.1x | 1.0x | 1.0x | 3.1x | 3.1x | 11.5x | 6.3% |
FLO | $1.2B | 21.4x | 7.1x | 0.2x | 0.2x | 0.5x | 0.5x | 11.0x | 26.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PEP | $203.8B | 23.3x | 17.2x | 2.1x | 2.1x | 4.0x | 3.8x | 16.3x | 4.3% |
CPB | $5.9B | 14.9x | 11.8x | 0.6x | 0.6x | 2.2x | 2.2x | 10.0x | 11.4% |
GIS | $17.6B | 8.1x | 9.6x | 1.0x | 1.0x | 2.9x | 2.9x | 10.1x | 9.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POST | $4.6B | 14.3x | 13.1x | 0.5x | 0.5x | 2.0x | 2.1x | 8.3x | 15.8% |
CAG | $7.1B | n/m | 10.3x | 0.6x | 0.7x | 2.6x | 2.7x | n/m | 13.8% |
SMPL | $1.0B | n/m | 7.0x | 0.7x | 0.8x | 2.2x | 2.4x | 9.3x | 14.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HRL | $11.5B | 33.3x | 14.1x | 0.9x | 0.9x | 6.1x | 6.1x | 15.5x | 6.8% |
HSY | $37.9B | 34.0x | 22.2x | 3.2x | 3.1x | 9.1x | 8.9x | 20.8x | 5.7% |
KHC | $27.2B | n/m | 11.1x | 1.1x | 1.1x | 3.3x | 3.3x | n/m | 14.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SJM | $10.7B | n/m | 10.1x | 1.2x | 1.2x | 3.7x | 3.6x | n/m | 9.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
UTZ | Revenue | +3.8% | +1.0% | +1.6% |
| EPS | −4.0% | +7.5% | +5.5% | |
JJSF | Revenue | −4.6% | +2.0% | +1.7% |
| EPS | +1.7% | +8.4% | +6.0% | |
FLO | Revenue | +2.6% | −2.8% | −0.4% |
| EPS | −18.7% | −23.2% | −7.4% | |
PEP | Revenue | +6.0% | +3.1% | +3.6% |
| EPS | +6.7% | +5.6% | +6.6% | |
CPB | Revenue | −4.9% | −2.9% | −0.5% |
| EPS | −26.0% | −21.7% | +6.9% | |
GIS | Revenue | −5.6% | −2.5% | +1.0% |
| EPS | −18.2% | −4.5% | +4.0% | |
POST | Revenue | +2.2% | −0.2% | −0.0% |
| EPS | +9.5% | +13.5% | +14.4% | |
CAG | Revenue | −3.2% | −3.9% | −0.4% |
| EPS | −26.7% | −14.9% | +3.6% | |
SMPL | Revenue | −7.9% | +0.5% | +1.8% |
| EPS | −14.7% | +6.6% | +7.7% | |
HRL | Revenue | +0.1% | +1.8% | +1.4% |
| EPS | +9.0% | +5.7% | +5.6% | |
HSY | Revenue | +5.8% | +2.8% | +2.7% |
| EPS | +40.4% | +18.1% | +8.6% | |
KHC | Revenue | −2.0% | +0.6% | +1.1% |
| EPS | −18.6% | +1.4% | +4.4% | |
SJM | Revenue | +3.2% | +1.0% | +1.5% |
| EPS | −10.2% | +10.4% | +8.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Intersnack Group agreed on 21 July to take Utz Brands private at $14.25 a share in cash, a day after the Hanover, Pennsylvania chipmaker closed at $7.45. The deal values Utz at about $2.9bn including debt and carries a premium of roughly 91%. On completion, expected in the fourth quarter, Utz leaves the New York Stock Exchange and is owned half by Intersnack and half by the founding Rice and Lissette family entities, financed with about $920m of Intersnack cash and a $1.1bn term loan.
Against consensus 2026 earnings before interest, taxes, depreciation and amortization of $217.6m, Intersnack is paying roughly 13.3x — which means the quoted market was valuing the identical cash flows near 7x the previous afternoon. That is the finding worth carrying forward: the dislocation on the American snack shelf was real, and a strategic buyer, not the public market, collected it. Everything else in the aisle is still being marked down.
What Utz's dollar actually did
Utz sells potato chips, pretzels, cheese snacks and pork rinds under Utz, Zapp's, Golden Flake and Boulder Canyon into grocers, clubs and convenience stores. Organic net sales rose 1.4% in the June quarter, and the composition matters more than the total: favourable net price realisation of 3.6% offset by lower volume and mix of 2.2%. In measured retail channels its volumes fell 4.6% while the salty-snack category's grew 1.1%, and its retail dollars grew 0.3% against the category's 0.8%. A year earlier the arrows pointed the other way — Utz volumes up 3.4% against a category down 0.9%.
The reversal has an author. PepsiCo, whose Frito-Lay unit holds roughly 62% of the US salty-snack market, cut prices on its core brands in February and won back shelf space, and its North America food volume turned positive at 2% for the first time in over two years. The category's volume recovery was bought by the leader's discount, and Utz was raising net price into it.
What improved was cost. Adjusted gross margin reached 33.2% from 31.7%, driven by productivity savings that more than offset supply-chain inflation, and net leverage fell 0.6 turns to 3.5x. "I was pleased with our execution in the quarter and the business performance through the first half, including the continued year-over-year improvement in adjusted free cash flow and net leverage," chief executive Howard Friedman said with the 5 August results. The delivery-route programme that once flattered selling costs is over: substantially all of Utz's direct-store-delivery routes were independent-operator managed as of 28 September 2025, and the company's own accounting notes that the saved selling cost comes back as a permanent discount to independent operators, reducing both net sales and gross profit.
The names nobody bid for
J&J Snack Foods sells nearly the same calories through a different meter — soft pretzels, churros and ICEE frozen beverages billed to stadiums, theatres and school cafeterias, with a machine estate it owns and services. Fiscal third-quarter net sales fell 6.2% to $426.0m, Food Service down 8.3%, and the razor-and-blade inverted: beverage sales rose 5.9% on theatre and mass traffic while machine sales fell $7.3m and service fell $3.4m. Gross margin expanded to 35.45% from 33.03% as management exits low-margin bakery items, yet operating income fell 23.6%. "Fiscal 2026 has been a year of disciplined transformation," chief executive Dan Fachner told investors on 5 August, promising a return to top-line growth in fiscal 2027. The shares, at 29.9x trailing earnings and 18.1x forward, already price that promise; consensus has revenue falling 4.6% this year before rising 2.0%.
Flowers Foods, the baker of Nature's Own and Dave's Killer Bread, is the harder case. Second-quarter revenue fell 4.0% to $1.193bn with operating income down 27.1%, total volume down 5.8% and fresh bread down 9.5%. Guidance was cut and the dividend reset to $0.125 a quarter from $0.2475 to prioritise debt reduction. "Our second quarter results did not meet our expectations," chairman and chief executive Ryals McMullian said on the 21 August call, citing household budgets, shifting preferences and competitive activity; management added that rivals have not followed its 2026 pricing moves. The equity optics look like a bargain — 7.05x forward earnings, 0.89x book — but that multiple is struck on a fiscal 2027 estimate of $0.79 a share, itself down 23.2%, and at the enterprise level Flowers and J&J Snack Foods trade within half a turn of each other near 11x trailing earnings before interest, taxes, depreciation and amortization. Leverage is doing the flattering.
The shelf, not the ticker
The pressure is category-wide: Simply Good Foods is down 59.6% over twelve months, Campbell's 37.9%, General Mills 36.4%. Two input legs are confirmed — the USDA forecasts canola oil at 78 cents a pound, up 11%, and freight expenditures are running about 9% higher year on year — while demand leaks at the top: households starting GLP-1 medications cut grocery spending 5.3% within six months, with savory snacks off about 10%. Bernstein cut four large packaged-food names to underperform in June on exactly that pairing of cost and appetite.
So the verdict splits cleanly. Utz's share price earns nothing from its own trading — volume and share went backwards, and the gain is a contract, not a turn. What Intersnack is buying is brands, shelf coverage and a completed route structure at a price the public market refused to pay; the premium measures the market's error, not Utz's momentum. J&J Snack Foods' and Flowers' declines, by contrast, are paid for in full by their own revenue, volume and guidance lines, and the cheapest-looking of the two is cheap against an estimate that keeps falling.
When the vote clears and the listing ends, the snack aisle loses the one quote that was not being set by what happens at the register.