

Primoris Lost $24m on Six Fixed-Price Jobs While Quanta's Unit-Rate Margin Hit 11.5%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Seven listed contractors build and maintain North America's electric and gas networks. Five widened margins last quarter while their shares fell; the two that did not were broken by things specific to them — fixed-price renewable overruns at Primoris, a 48% jump in diesel at Centuri.
The dividing line is the contract. Unit-rate work under master service agreements held: Quanta's electric segment earned 11.5%, against the 10%-to-12% ceiling its own chief executive describes. Fixed-price work did the damage: Primoris took group gross margin to 4.88% from 12.26% and had consensus earnings for this year cut 61% against a record order book. Aecon is the same mechanism in reverse, its margin recovering as its last legacy fixed-price job finished.
MasTec's halved share price is the piece none of the operating numbers explain.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
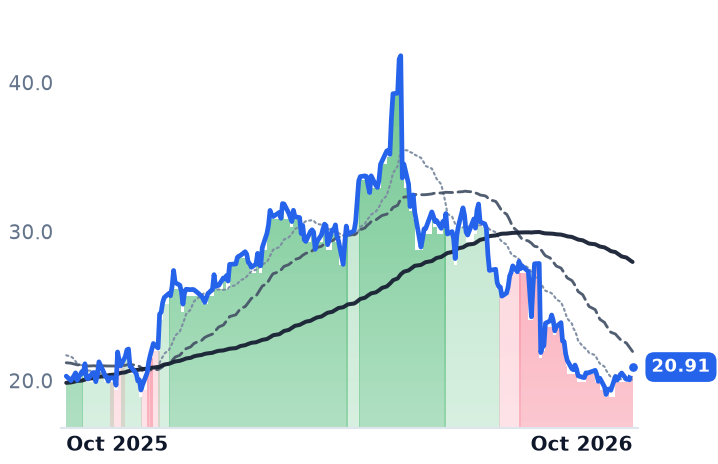
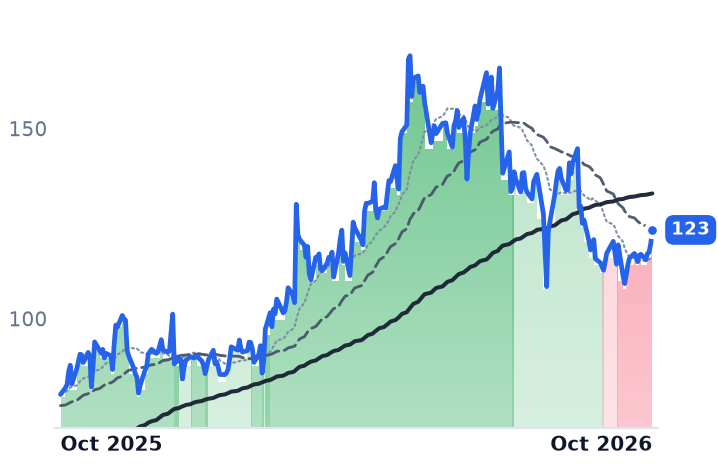
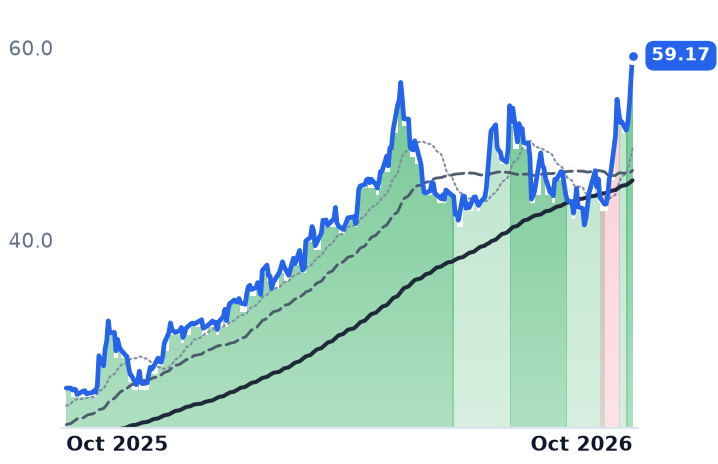
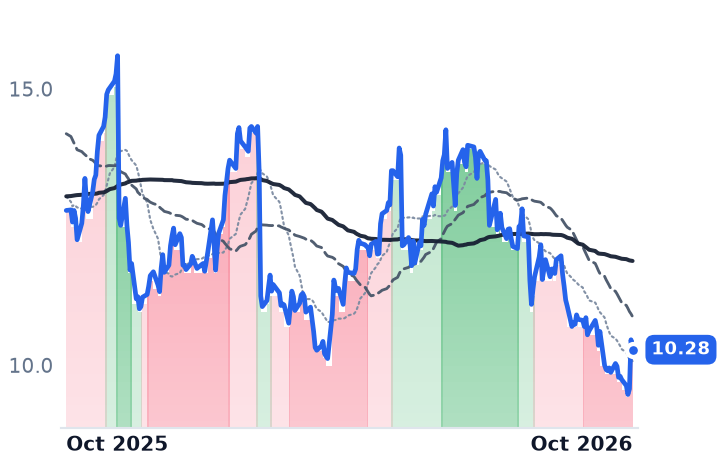
PWR | Quanta Services | Electrical & Power Infrastructure | ⚠️ Emerging Bear | +9.1% | +60.7% |
PRIM | Primoris Services | Energy & Power Project Solutions | 🔴 Cont. Bear | +7.5% | −42.1% |
MTZ | MasTec | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −7.0% | +0.1% |
MYRG | MYR | Electrical & Power Infrastructure | ⚠️ Emerging Bear | +7.3% | +52.7% |
CTRI | Centuri | Utility Services & Installation | ⚠️ Emerging Bear | +2.0% | +3.0% |
ECG | Everus Construction | Electrical & Power Infrastructure | ⚠️ Emerging Bear | +7.2% | +54.1% |
ARE.TO | Aecon | Engineering & Construction | 🟢 Cont. Bull | +36.1% | +140.6% |
MTRX | Matrix Service | Engineering & Construction | 🔴 Cont. Bear | −2.6% | −19.7% |
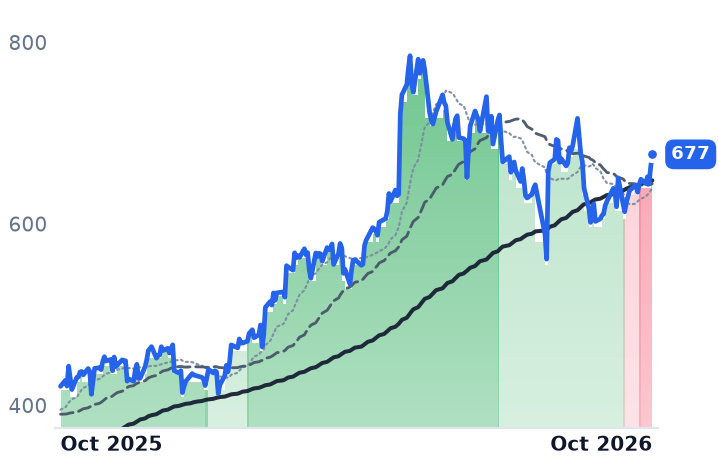
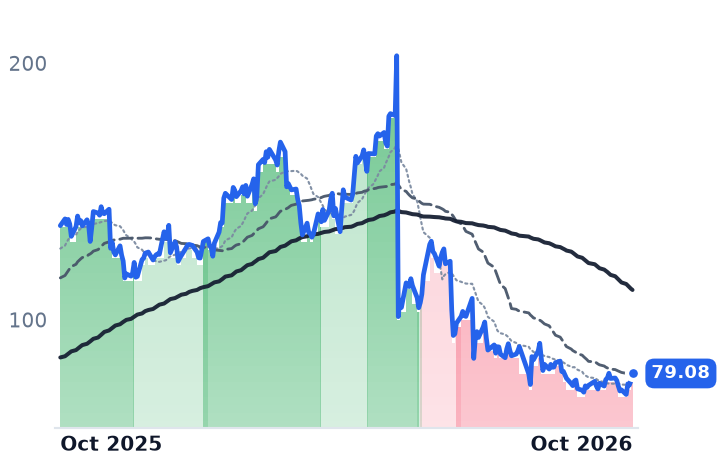
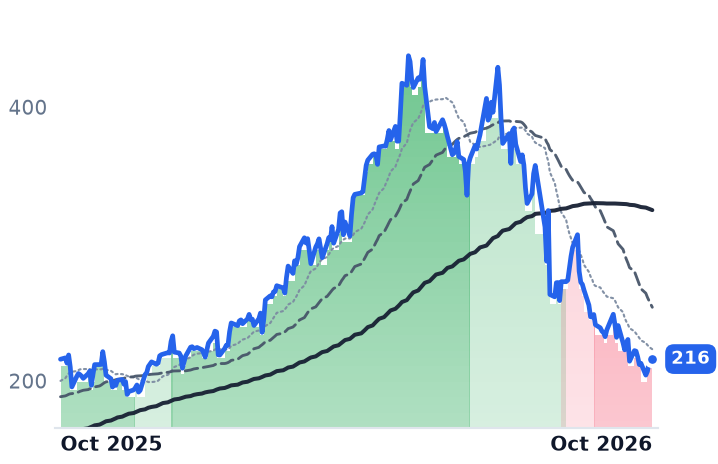
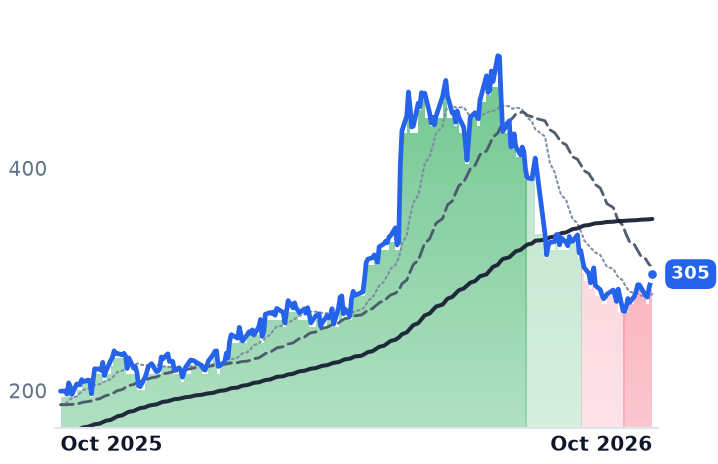
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWR | $101.7B | 76.5x | 40.4x | 3.1x | 2.6x | 21.5x | 17.8x | 35.5x | 2.4% |
PRIM | $4.3B | 30.7x | 36.9x | 0.6x | 0.6x | 6.8x | 6.8x | 16.9x | 2.1% |
MTZ | $17.3B | 34.0x | 23.2x | 1.1x | 1.0x | 9.4x | 8.3x | 15.4x | 1.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MYRG | $4.7B | 28.7x | 25.0x | 1.2x | 1.1x | 9.6x | 8.7x | 15.8x | 4.1% |
CTRI | $2.1B | 66.7x | 30.6x | 0.7x | 0.6x | 7.8x | 6.9x | 13.4x | -0.7% |
ECG | $6.3B | 24.8x | 23.3x | 1.5x | 1.4x | 11.3x | 10.4x | 17.1x | 4.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ARE.TO | $4.1B | n/m | 38.7x | 0.7x | 0.6x | 8.5x | 8.0x | 34.5x | 7.0% |
MTRX | $289.2M | n/m | 17.3x | 0.3x | 0.3x | 4.5x | 4.2x | 12.5x | 0.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
PWR | Revenue | +41.1% | +16.2% | +13.8% |
| EPS | +57.6% | +17.8% | +17.9% | |
PRIM | Revenue | −3.5% | +11.4% | +10.2% |
| EPS | −61.2% | +144.5% | +18.9% | |
MTZ | Revenue | +29.2% | +18.9% | +15.4% |
| EPS | +44.9% | +34.5% | +31.0% | |
MYRG | Revenue | +22.9% | +15.5% | +11.4% |
| EPS | +72.5% | +18.4% | +22.2% | |
CTRI | Revenue | +28.8% | +13.0% | +8.8% |
| EPS | +53.2% | +43.6% | +26.4% | |
ECG | Revenue | +28.9% | +11.8% | +7.0% |
| EPS | +45.5% | +12.8% | +10.9% | |
ARE.TO | Revenue | +20.0% | +6.5% | +4.9% |
| EPS | +617.9% | +38.4% | +15.3% | |
MTRX | Revenue | +11.6% | +6.4% | +5.7% |
| EPS | −105.4% | +1600.0% | +16.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Primoris Services booked a record order book in the second quarter and still lost money. The damage came from six fixed-price renewable-energy projects, while the gas-distribution and electric line work that makes up most of the Dallas contractor's $13.9bn backlog was not the problem.
That distinction is now the only thing that separates these businesses from one another. Seven listed specialty contractors build, upgrade and maintain North American electric and gas networks, and all seven sold off in August — the trigger, established at the time, was MasTec's cut to its wireless-communications guidance, which dragged down companies that sell nothing to carriers. Five of the seven then reported wider margins. Group-level multiples have a separate explanation: the Federal Reserve raised rates 25 basis points on 16 September and the 30-year Treasury yield reached its highest since 2002, which discounts order books that managements themselves date to 2027 and beyond.
Unit rates held
Quanta Services, the Houston contractor that supplies craft crews to utilities and keeps roughly 28,000 journeymen and foremen in the field daily, bills most of its work at unit rates under master service agreements. Its electric infrastructure segment earned an 11.5% operating margin, up from 10.1%, on revenue up 43.6% — and on the second-quarter call chief executive Duke Austin put the ceiling on that business at "10 to 12 on the utility side," with 12 achievable only when every element stacks at once. Group gross margin of 16.17% breaks a five-year record of roughly 13%. The near-term book grew faster than the long tail: twelve-month backlog rose 61.5% to $32.3bn against total backlog up 49.2% to $53.4bn. "Total backlog reached a record level at quarter end," Austin said in the 30 July release. Quanta costs 40.4 times forward earnings against 76.5 times trailing — cheaper on forward earnings than the 53x to 57x logged in May, when trailing was above 90x.
The same direction held at the smaller names. MYR Group, the 1891-vintage electrical contractor whose transmission-and-distribution division runs high-voltage lines and substations, took T&D operating margin to 9.4% from 8.0% on record net income of $49.9m. MasTec, the Coral Gables group whose power delivery arm carries a record $6.3bn book, lifted operating margin to 5.17% from 4.41% and guided to $9.30 of full-year earnings, up 42%. Everus Construction, the Bismarck builder of transmission lines and electrical panels, earned the highest operating margin here at 9.08% and raised guidance on data-center demand. MasTec costs 23.2 times forward earnings against 34.0 trailing, MYR Group 25.0 against 28.7, Everus 23.3 against 24.8 — each roughly 1.6 times cheaper on forward earnings than Quanta.
Where it broke
Primoris's energy segment revenue fell 19.2% and its gross margin went slightly negative from 10.8% a year earlier, taking group gross margin to 4.88% from 12.26% and producing a $24.2m net loss. The overruns are bounded and dated: two of the six projects are finished, three were due to complete in the third quarter and the last reaches mechanical completion in early November. Chief executive Koti Vadlamudi said the quarter carried "the majority of the impact". Consensus still cut this year's earnings 61% to $2.14, which leaves Primoris the one name here whose forward multiple — 36.9x — sits above its 30.7x trailing.
Centuri Holdings, the Phoenix gas and electric utility services arm majority owned by Southwest Gas, shows the other cost that lands on unit-rate work. Fuel prices rose 48% year on year, costing roughly $7m and 70 basis points of base gross margin on work it cannot reprice mid-contract; operating income fell 28.4% on record revenue of $962.0m. It raised full-year guidance anyway and trades at 13.4 times trailing earnings before interest, taxes, depreciation and amortization, the lowest here.
Aecon Group, the Toronto contractor founded in 1877, is the mechanism in reverse. Its third and final legacy fixed-price project reached substantial completion in the quarter, gross margin went to 9.48% from 5.91%, and adjusted EBITDA doubled. Its C$108.1m headline loss is a C$124.2m non-cash remeasurement on the Oaktree preferred shares it is buying out of Aecon Utilities. Then Ontario Power Generation awarded the Pickering refurbishment packages, about C$1.75bn of which is Aecon's and enters third-quarter backlog. The shares have more than doubled over twelve months and cost 38.7 times forward earnings.
The contract form was the risk, not the lineman
The trend signals that turned down across this group in September are measuring an August decline that Quanta has since partly reversed, rising to $676.56 by 2 October. Primoris's de-rating is earned and, on cut earnings, has not made the shares cheap. Centuri's is a diesel bill with guidance intact. MasTec is the one nothing in the accounts explains: down 42.2% in three months and 50.6% below its high, on expanding margins, a 30% larger backlog and earnings consensus expects to rise 44.9%.
Lineman wages were never the exposure in this group; the contract form is. Primoris's sixth problem project is due to finish by year end, and third-quarter results land from 28 October.