

Powell Books Switchgear Into Fiscal 2028 and Costs 28 Times Earnings, Against 35x in May
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The grid-equipment names that fell hardest this quarter are the ones whose businesses improved most, and the one that rose is the one that got dearer and, on reported profit, worse.
Powell Industries booked $934m of orders in the June quarter — roughly three times what it billed — took backlog to a record $2.4bn and held gross margin at 30.6% while copper set an all-time high. Its shares are a fifth lower over three months. Eaton raised guidance on record orders, yet its reported net income fell 16.4% and it is the only name here whose earnings multiple expanded.
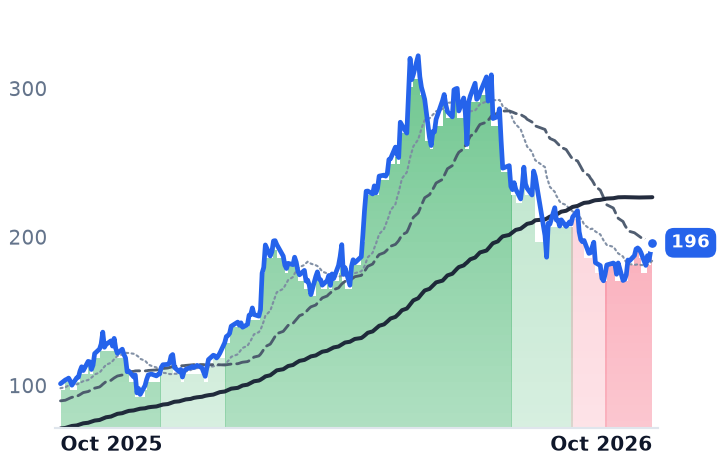
The judgment: a missed quarter and thinning operating leverage earn part of Powell's fall; the rest is the price of time, with the 30-year Treasury yield at 5.61% and one September session repricing everything with a 2028 delivery date.
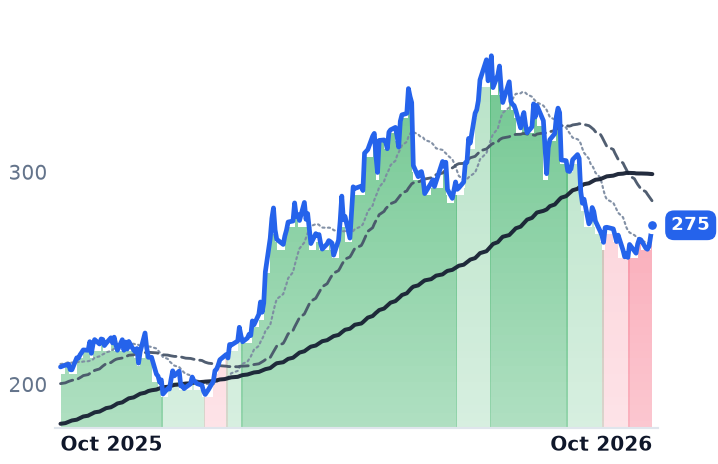
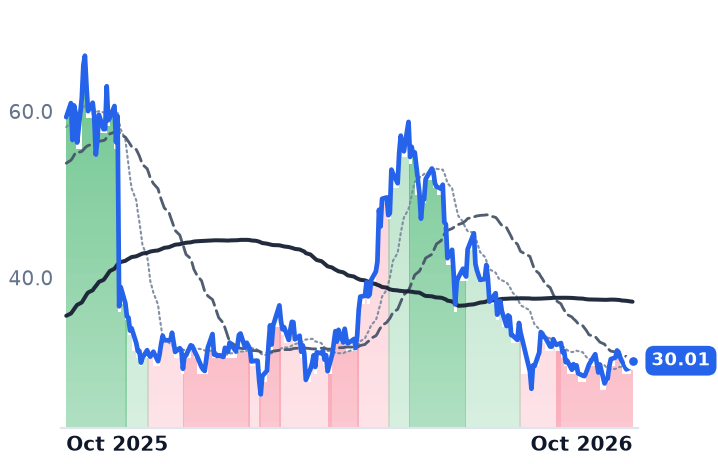
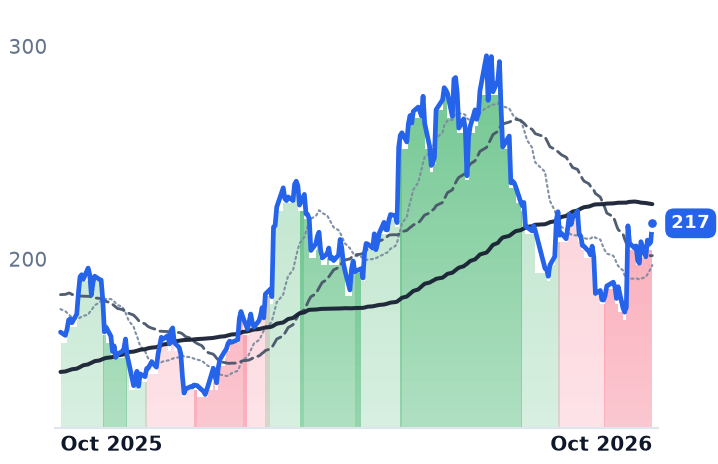
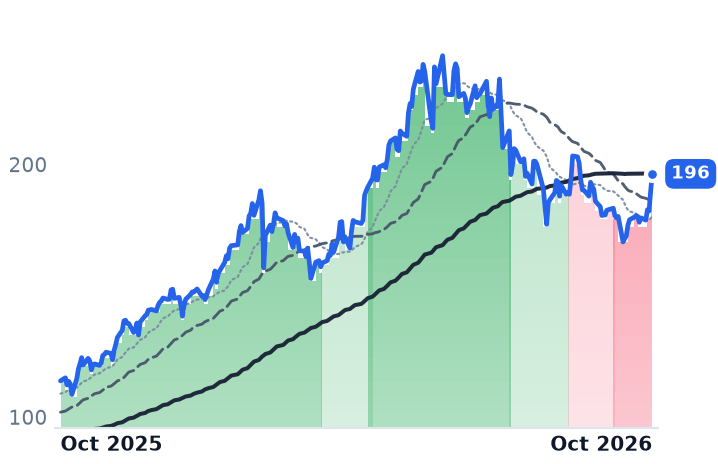
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
POWL | Powell Industries | Electrical Distribution & Switchgear | ⚠️ Emerging Bear | +12.0% | +93.7% |
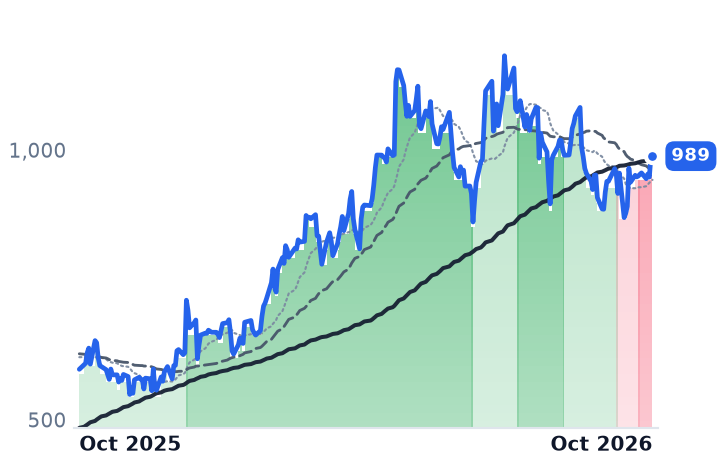
GEV | GE Vernova | GE Vernova Integrated | ⚠️ Emerging Bear | +5.0% | +66.5% |
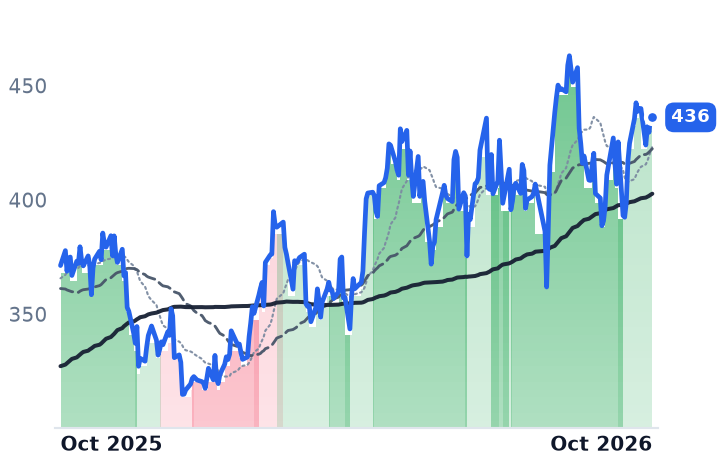
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | +9.8% | +17.5% |
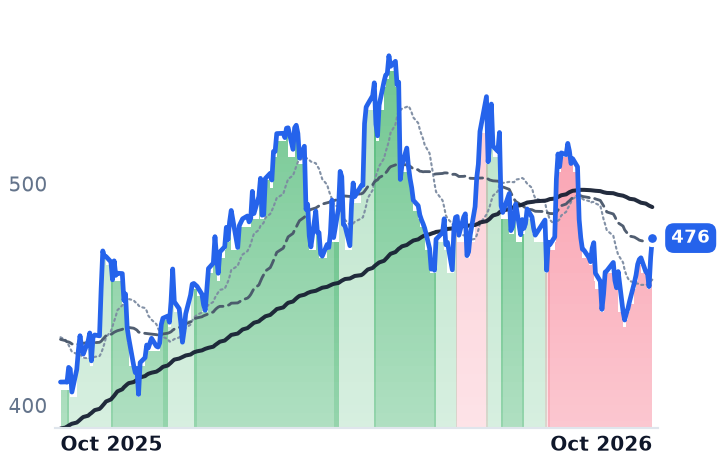
HUBB | Hubbell Incorporated | Electrical Distribution & Switchgear | ⚠️ Emerging Bear | +3.3% | +15.8% |
NVT | nVent Electric | Data Center Power & Thermal | 🟢 Cont. Bull | +11.5% | +74.3% |
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −6.2% | +57.5% |
SPXC | SPX Technologies | HVAC & Refrigeration | ⚠️ Emerging Bear | −10.7% | −8.8% |
RAL | Ralliant | Advanced Materials & Components | 🟢 Cont. Bull | +16.7% | +65.6% |
ESE | ESCO Technologies | Data Infrastructure & Software Solutions | ⚠️ Emerging Bear | +0.4% | +32.0% |
AMSC | American Superconductor | Specialty Components & Systems | 🔴 Cont. Bear | +3.4% | −49.4% |
GNRC | Generac | Power & Propulsion Systems | ⚠️ Emerging Bear | +18.5% | +30.9% |
ENS | EnerSys | Energy Storage & Batteries | ⚠️ Emerging Bear | +9.1% | +71.6% |
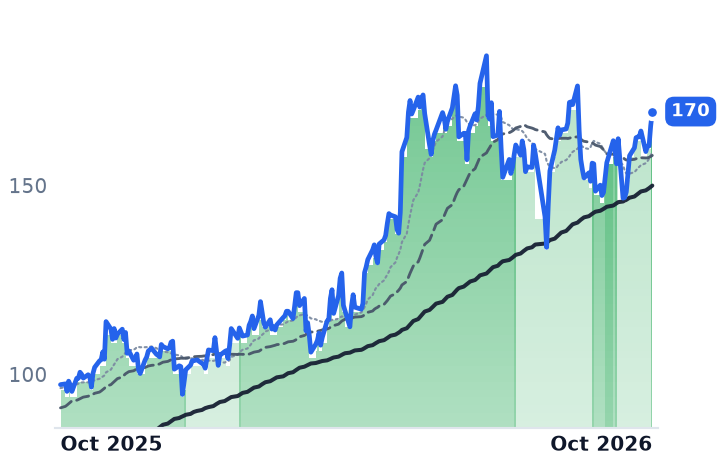
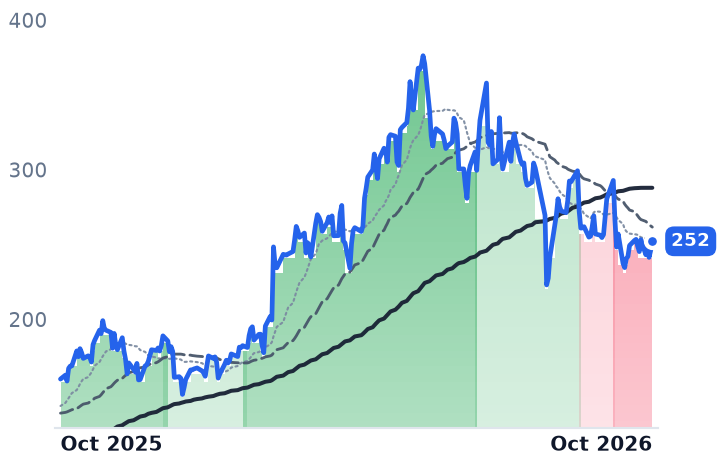
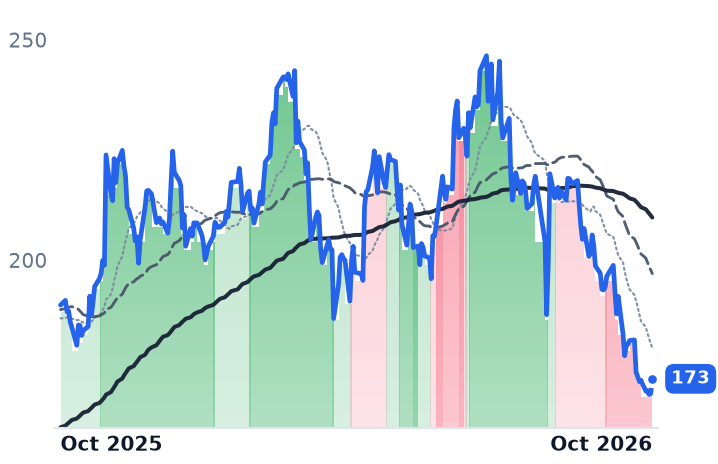
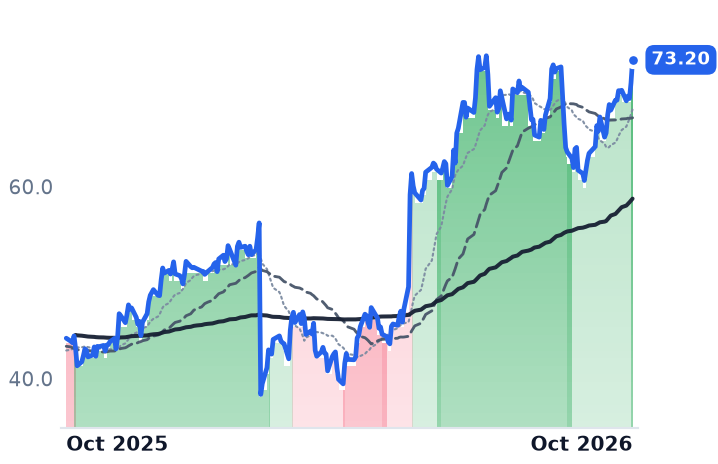
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POWL | $7.1B | 37.4x | 28.5x | 6.2x | 4.8x | 20.5x | 15.8x | 26.2x | 3.4% |
GEV | $263.3B | 28.0x | 32.4x | 6.4x | 5.7x | 31.5x | 28.1x | 29.3x | 4.7% |
ETN | $169.3B | 44.2x | 32.2x | 5.6x | 5.1x | 15.7x | 14.3x | 29.5x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HUBB | $25.1B | 28.1x | 23.2x | 4.0x | 3.7x | 11.5x | 10.4x | 20.5x | 3.6% |
NVT | $27.4B | 46.0x | 33.0x | 5.7x | 5.0x | 15.3x | 13.6x | 28.6x | 2.1% |
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPXC | $8.7B | 30.7x | 20.7x | 3.5x | 3.1x | 8.7x | 7.8x | 17.1x | 3.5% |
RAL | $8.1B | n/m | 25.6x | 3.7x | 3.5x | 7.6x | 7.2x | n/m | 4.0% |
ESE | $7.1B | 22.6x | 29.8x | 5.5x | 4.6x | 13.1x | 10.9x | 25.7x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMSC | $1.5B | 9.7x | 34.2x | 4.5x | 4.0x | 16.1x | 14.0x | 45.2x | 1.4% |
GNRC | $12.8B | 49.2x | 22.4x | 2.9x | 2.6x | 7.3x | 6.5x | 25.0x | 3.0% |
ENS | $7.2B | 20.6x | 14.7x | 1.9x | 1.8x | 6.2x | 6.0x | 13.1x | 10.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
POWL | Revenue | +8.8% | +25.8% | +14.4% |
| EPS | +12.1% | +27.8% | +19.8% | |
GEV | Revenue | +24.0% | +14.6% | +14.9% |
| EPS | +319.0% | −19.6% | +41.4% | |
ETN | Revenue | +19.9% | +11.1% | +9.7% |
| EPS | +12.5% | +19.1% | +17.2% | |
HUBB | Revenue | +17.6% | +10.3% | +6.2% |
| EPS | +12.6% | +12.0% | +10.8% | |
NVT | Revenue | +42.8% | +21.1% | +15.3% |
| EPS | +54.3% | +27.3% | +19.0% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
SPXC | Revenue | +22.1% | +12.6% | +6.7% |
| EPS | +24.3% | +16.0% | +10.3% | |
RAL | Revenue | +11.5% | +6.6% | +6.0% |
| EPS | +7.2% | +17.2% | +17.8% | |
ESE | Revenue | +17.8% | +18.4% | +11.9% |
| EPS | +43.0% | +10.4% | +15.1% | |
AMSC | Revenue | +36.2% | +24.9% | +14.6% |
| EPS | +470.9% | −74.6% | +46.7% | |
GNRC | Revenue | +15.4% | +29.1% | +18.5% |
| EPS | +48.8% | +29.0% | +24.7% | |
ENS | Revenue | +3.3% | +4.6% | +4.9% |
| EPS | +3.5% | +29.2% | +7.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Powell Industries has work booked into fiscal 2028. The Houston company builds custom medium- and high-voltage switchgear, circuit breakers and modular "E-House" substations — the metal-clad gear that sits between a utility feed and a refinery, a mine or a data hall — and among its recent awards is a single data-center project worth more than $400m that pushes execution two fiscal years out. Order backlog reached $2.4bn at the end of June, the first time it has exceeded $2bn in the company's 79 years.
What has changed since early September is the price attached to that duration. Powell trades at 28.5 times forward earnings and 37.4x trailing, against about 35x forward in May, when backlog was $1.8bn and gross margin 28.4%. The order book is not the reason. The 30-year Treasury yield reached 5.61% on 1 October, its highest since 2004, with traders moving to price better than a 75% chance of a Federal Open Market Committee rate increase in October. A delivery that lands in 2028 is discounted harder than one that ships this quarter. That is the mechanism by which the longest-dated books re-rate with nothing operational going wrong.
The quarter the price is arguing with
Powell booked $934m of new orders in the June quarter, up 158% and roughly three times the $311.7m it recognized as revenue. Revenue growth has been accelerating — 4.0%, then 6.5%, then 8.9% across the fiscal year's three reported quarters. Gross margin was 30.6%, level with a year earlier and up from 29.6% in the March quarter. The backlog's largest component is no longer oil and gas: commercial and other industrial work is 40% of it, against 24% each for oil and gas excluding petrochemicals and for electric utilities.
That margin held through a record input cost. Three-month copper on the London Metal Exchange set an all-time high above $14,500 a tonne in early September as tariff fears concentrated metal in the United States, and a trade compilation of US producer price data puts copper wire and cable up 17.9% in the year to July against switchgear up 8.9% — input cost running at roughly twice the pace of output price, on a secondary compilation rather than a primary government citation. Powell's own account is that the squeeze has not reached the income statement. There is "moderate inflation on core commodities like copper and steel," chief financial officer Mike Metcalf said on the August 4 call, which was "being offset by hedging and commercial discipline."
The blemishes are real but small. Powell missed on both lines, reporting earnings of $1.42 a share against $1.47 expected on revenue of $311.7m against $315.2m, and operating income grew 6.6% on 8.9% more revenue, trimming operating margin to 20.6% from 21.0%. The harder problem is the forward arithmetic: consensus has fiscal 2027 revenue at $1.503bn, a 25.8% acceleration that no reported quarter has yet produced. The backlog says the work exists. The delivery schedule says much of it bills in 2028.
Five sessions, not a slow slide
Powell is down 20.4% over three months and 39% below its 2026 high, yet the balance of the quarter was net positive — the decline sits in a handful of dates. The worst was September 14, when Anthropic chief executive Dario Amodei's essay calling for a slowdown in advanced artificial-intelligence development, endorsed by Sam Altman and Elon Musk, hit everything attached to the data-center buildout; the power producer Vistra fell 28%. The same day, GLJ Research initiated GE Vernova at Sell with a $470 target, calling it "a cyclical gas-turbine manufacturer priced as a secular compounder" — an argument about price, not production. The telling detail is who fell hardest: nVent Electric, the enclosures and thermal-management maker, lost 9.7% that session, more than Powell's 6.5% or GE Vernova's 8.6%, and nVent has held an uptrend throughout, its 50-day average above its 200-day. Powell has since recovered 14.9% off that low, GE Vernova 13.0%.
The mirror and the short-cycle name
GE Vernova's Electrification arm is where the hypothesis of a fading backlog should show first, and it shows the reverse: June-quarter orders of $6.3bn, up 66% organically, equipment backlog of $40.6bn and segment profitability up 700 basis points organically to an 18.4% margin. "The long-cycle electric power industry is in the early stages of a multi-decade growth opportunity," chief executive Scott Strazik told investors on the second-quarter call. Its 32.4x forward multiple is flattered by a $4.5bn pre-tax gain on Prolec GE sitting inside this year's consensus; against next year's $24.51 of expected earnings it is 40.3x, down from roughly 37–40x forward in May on a comparable basis only loosely.
Eaton, the one name here whose shares rose, is also the one that got more expensive — 32.2x forward against roughly 30–31x in May — and the only one with genuine profit deterioration: reported net income fell 16.4% to $821m on 21.4% more revenue, with gross margin down 349 basis points. Its Electrical Americas segment posted record sales of $4.0bn and record operating profit at a 27.5% margin, and chief executive Paulo Ruiz said "accelerating orders and growing backlogs are clear proof points that our customer-focused end-to-end solutions are winning in the market." Eaton also made the longest-duration statement anyone in this group made: US data-center backlog has grown to 307 gigawatts, with only about 20% converting near term and the majority translating to deliveries in 2028 and beyond. Hubbell, meanwhile, the utility-component maker that entered its downtrend earliest, on July 30, is the cheapest of the group at 23.2x forward earnings after reported profit fell 1.6% on interest from a $3.0bn acquisition closed in June, while it doubled sales-growth guidance to 16–18%.
What the group actually sorted on
The sort was not contract structure. If fixed-price awards signed before the copper was bought were the problem, Powell would be the casualty and Eaton the refuge; instead Powell's booked margin rose at a record copper price and Eaton's reported profit fell. Nor did the shortest book protect anyone on the day it mattered. Powell's missed quarter and its thinning operating leverage earn a share of a 20% decline; the remainder is the discount rate applied to a 2028 delivery slot, plus one weekend's doubt about whether the halls get built at all. Both are repricings of time, and neither has yet appeared in an order, a margin or a cancellation.
The awkward consequence is that Powell now finds out last. A hyperscaler that slows down cancels a 2028 switchgear slot long after the equity has been marked for it — which is why the shares moved first, and why the September quarter's backlog number is the only disclosure that can settle the argument.