

Doron Blachar Says 190 of Ormat's Megawatts Reprice at $86 No Sooner Than 2031
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Geothermal delivers the round-the-clock carbon-free power every data-center deal now asks for, and the older of the two US-listed pure-plays is being paid slightly less for it than a year ago. Ormat's average realized price slipped to $92.6 per megawatt hour in 2025 from $94.3, and its product division, which sells turbines and engineering to rival developers, shrank 21.6% last quarter.
Fervo, public since May, has no annuity at all: a 1,054-megawatt contracted offtake book, first power last week, and drilling costs down roughly 70% per foot since 2022.
September's decline was shared with Brookfield Renewable and Clearway as the 10-year Treasury reached 5.21%, so the month was mostly about the discount rate. What is being repriced at Ormat is the value of an old contract book, and it cannot be refreshed at scale before the 2030s.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
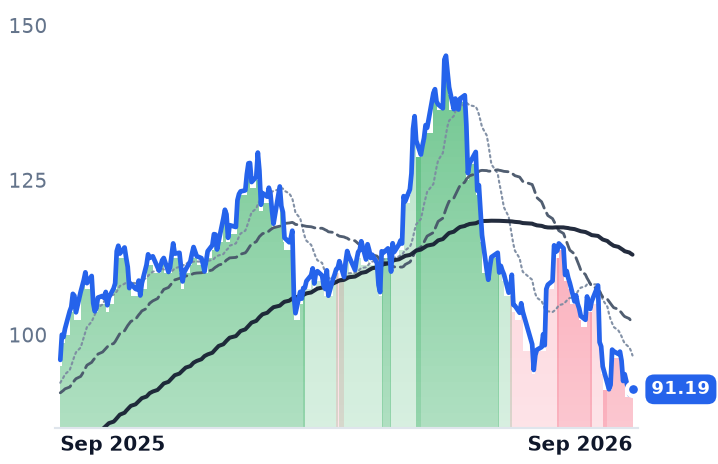
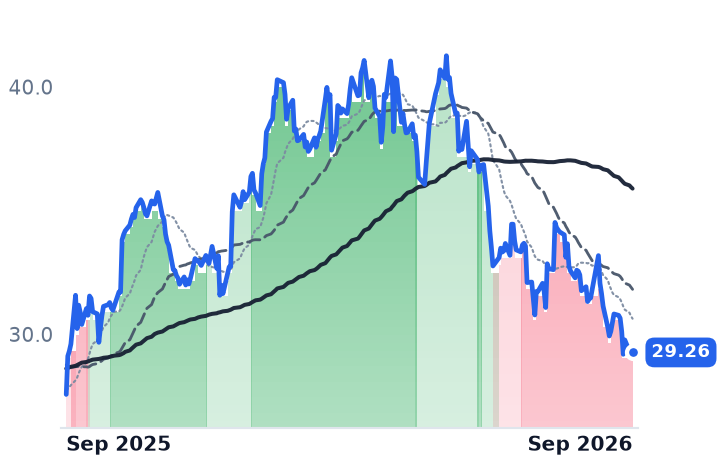
ORA | Ormat Technologies | Geothermal & Specialized | ⚠️ Emerging Bear | −11.0% | −5.0% |
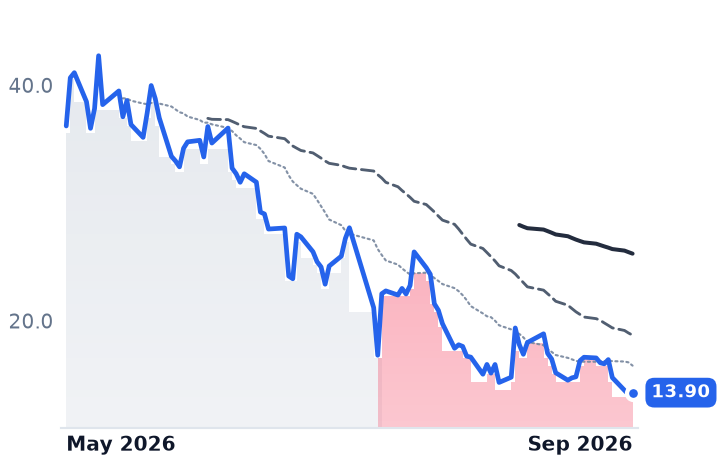
FRVO | Fervo Energy | Emerging & Specialized Energy | 🔴 Cont. Bear | −8.6% | −61.9% |
| Compared against · context, not the story | |||||
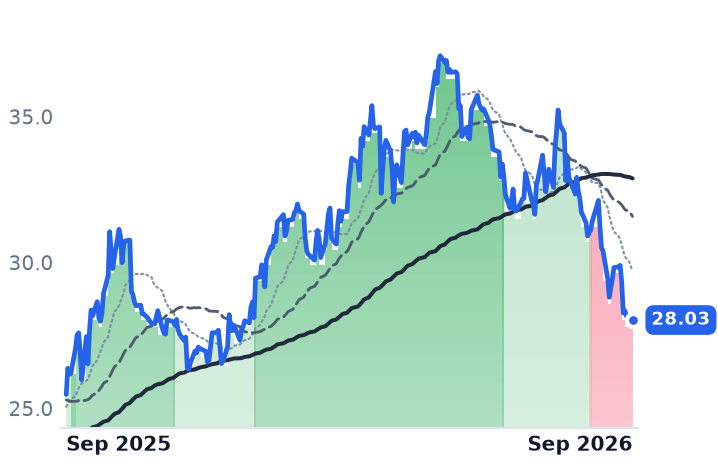
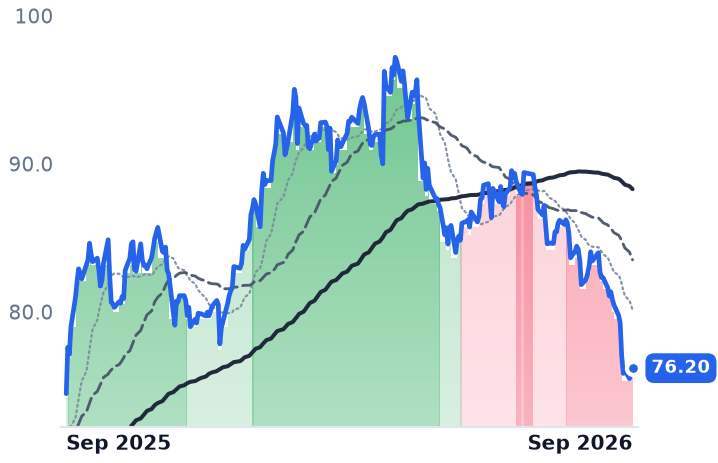
BEP | Brookfield Renewable Partners | Diversified Renewable Generators | ⚠️ Emerging Bear | −10.6% | +10.0% |
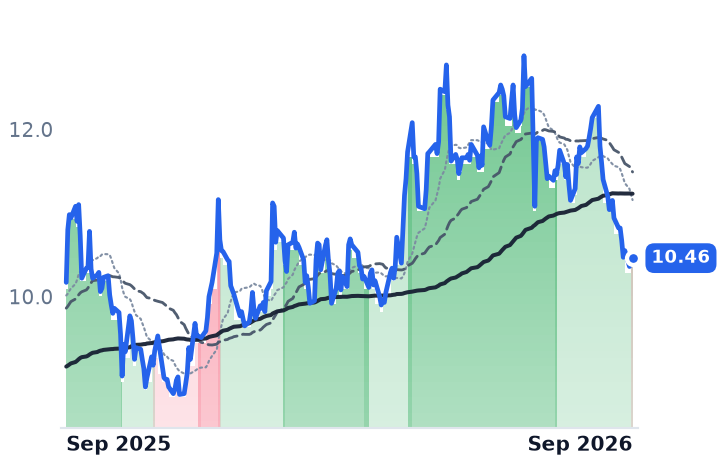
XIFR | XPLR Infrastructure | Renewable & Infrastructure Assets | 🟢 Cont. Bull | −11.1% | +2.9% |
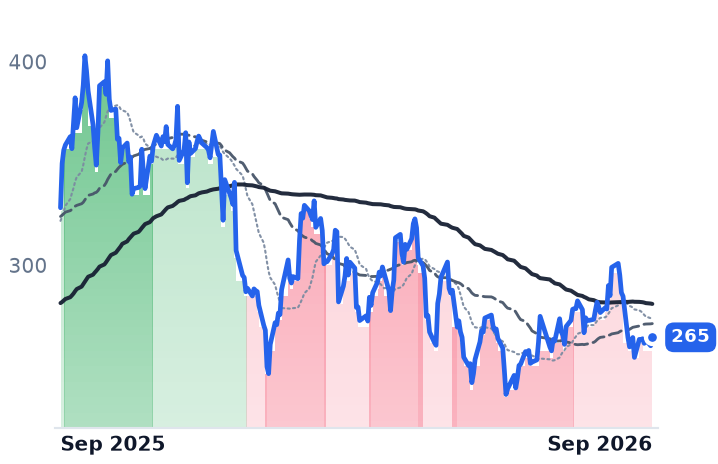
CWEN | Clearway Energy | Wind & Solar Developers | 🔴 Cont. Bear | −8.3% | +6.2% |
NEE | NextEra Energy | Vertically Integrated Utilities | 🔴 Cont. Bear | −7.3% | +2.3% |
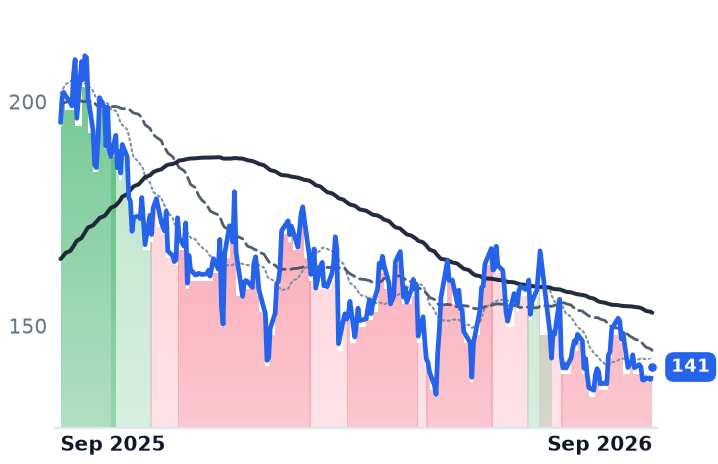
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | −5.2% | −19.4% |
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +2.6% | −27.9% |
TLN | Talen Energy | Wholesale Power Producers | 🔴 Cont. Bear | +5.9% | −26.5% |
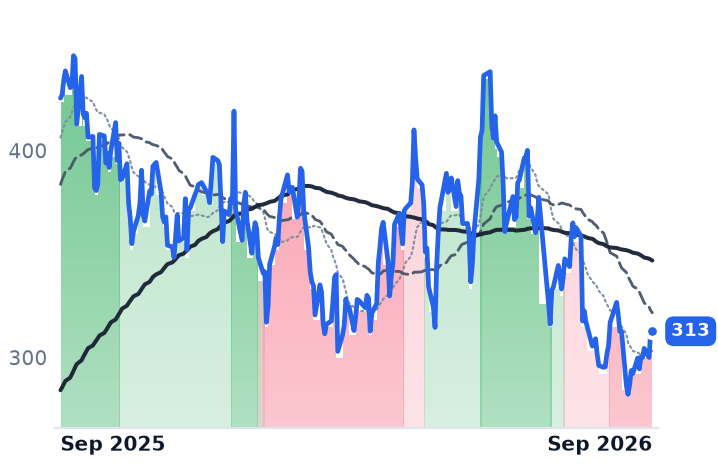
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ORA | $5.6B | 44.0x | 36.0x | 4.7x | 4.8x | 16.9x | 17.1x | 19.6x | -4.7% |
FRVO | $3.9B | n/m | — | — | 697.5x | — | — | n/m | -11.4% |
BEP | $9.1B | 64.8x | — | 1.4x | 1.4x | 5.9x | 5.6x | 9.7x | -51.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
XIFR | $994.6M | 15.7x | 9.3x | 0.8x | 0.7x | 4.8x | 4.3x | 8.8x | -63.7% |
CWEN | $6.3B | 40.3x | — | 4.0x | 3.8x | 7.6x | 7.2x | 14.3x | 10.7% |
NEE | $165.4B | 17.7x | 19.7x | 5.7x | 5.3x | 7.9x | 7.4x | 15.4x | -6.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEG | $94.5B | — | 21.8x | — | 2.8x | — | — | 13.9x | 0.3% |
VST | $46.7B | — | 16.4x | — | 2.1x | — | — | 10.2x | 2.9% |
TLN | $13.8B | n/m | 14.8x | 3.9x | 3.1x | 8.8x | 7.0x | 29.2x | 3.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ORA | Revenue | +21.4% | −1.7% | +11.1% |
| EPS | +16.3% | −3.5% | +28.4% | |
FRVO | Revenue | +3950.2% | +1195.2% | +180.7% |
| EPS | −91.5% | −23.7% | −21.5% | |
BEP | Revenue | +3.9% | +7.6% | −11.5% |
| EPS | +5.7% | −20.9% | −6.6% | |
XIFR | Revenue | +0.8% | +4.7% | +1.3% |
| EPS | −849.6% | −44.0% | −144.3% | |
CWEN | Revenue | +14.5% | +11.5% | +12.2% |
| EPS | −116.0% | −318.9% | +60.4% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.1% | +8.5% | |
CEG | Revenue | +37.2% | +2.5% | +5.3% |
| EPS | +28.9% | +10.4% | +26.4% | |
VST | Revenue | +16.6% | +10.0% | +5.1% |
| EPS | +77.0% | +19.7% | +18.7% | |
TLN | Revenue | +84.0% | +16.0% | +4.9% |
| EPS | +247.2% | +49.2% | +17.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ormat Technologies, which owns and operates geothermal plants in Nevada, California, Kenya and Guatemala and sells their output under long-term power purchase agreements, told investors in August how long it will be before the data-center power bid reaches most of its revenue line. A block of contracted capacity sits priced in the mid-$80s per megawatt hour and cannot be renegotiated until the next decade.
"Between 2031 and 2034, we have approximately 190 megawatts under contract that are currently priced at a weighted average of approximately $86 per megawatt hour, lower than today's market pricing of over $100 per megawatt hour," chief executive Doron Blachar said on the second-quarter call dated August 12.
That is the geothermal annuity in one sentence. Ormat's plants sell substantially all their output under contracts with a weighted-average remaining term of about 14 years, most at fixed prices, and its average realized price fell to $92.6 per megawatt hour in 2025 from $94.3 in 2024 — a decline during the year firm clean power became the most discussed commodity in the electricity business. For the equity, what reprices is the value of an old contract book, on a five-to-eight-year lag.
What the fleet is actually paid
Two channels pull that forward. The first is amendment: on March 10 Ormat signed a "blend-and-extend" deal at its Casa Diablo-4 plant lifting contract pricing about 27% over a 15-year term, effective October 1. The second is expiry, and there is little of it soon: the Amatitlan contract in Guatemala runs to the end of 2027, while Heber 1 was extended 25 years to 2052. Management says over 200 MW is in negotiation above $100 per megawatt hour, against contracts signed over the prior five years at $60 to $80. The hyperscaler business booked so far is small and deferred: up to 150 MW for Google with deliveries expected between 2028 and 2030, and 13 MW for Switch.
So the growth reported in the June quarter came from elsewhere. Electricity revenue rose 5.8% to $169.3m on a full quarter of Blue Mountain, well-field optimization at Olkaria and lower curtailments at McGinnis Hills, Dixie Valley and Tungsten — capacity and availability doing the work of price.
The two books blended into the same line
Ormat's product segment, which sells geothermal turbines and engineering to third-party developers, shrank 21.6% to $46.7m at a 9.7% gross margin, with backlog of $202.8m concentrated in Asia and Oceania. The storage segment, paid merchant rates for ancillary services, grew 195.1%. Consolidated revenue rose 10.6% to $258.8m, yet operating income fell 3.2% and net income 3.4%. Growth decelerated hard inside the year, from 75.8% in the March quarter. Full-year 2025 gross margin was 27.6% against 31.0% in 2024, and consensus has 2027 revenue declining 1.7% with earnings per share down 3.5%.
Against that, Ormat trades at 19.6 times trailing earnings before interest, taxes, depreciation and amortization — roughly double the 10 to 12 times typical for owners of contracted power — 36 times forward earnings, and a trailing free-cash-flow yield of minus 4.7%. The September 8 investor day targeted 3.5 to 3.7 gigawatts by 2030 with $1.0bn to $1.1bn of EBITDA and electricity gross margin recovering to 40%, while placing enhanced geothermal at a gigawatt only between 2033 and 2035. Shares fell 8.5% the next session.
Fervo is a cost curve wearing a power company's clothes
Fervo Energy, the Houston developer that drills horizontal wells into hot rock, has the mirror-image balance sheet: no annuity, and a learning curve instead. Phase I wells at Cape Station in Utah averaged 21 days and 14,483 feet at about $7,000 per kilowatt, with Phase II targeted at $5,500 and per-foot drilling costs down roughly 70% since 2022. Its binding offtake book reached about 1,054 MW when Google signed a 396 MW contract on September 1; the 658 MW signed before it, including 320 MW with Southern California Edison, carries a $7.2bn contracted revenue backlog. None of it is collected yet. Revenue was $113,000 in the June quarter; capital spending was $226.5m, with $850m to $900m guided for the second half against $2.1bn of cash, a May initial public offering of 70m shares at $27.00 and $421m of non-recourse project debt. Consensus does not have Fervo earning a profit until 2029; at 1.43 times book, about $1.87bn of net cash sits inside a $3.90bn market value.
First power came on September 24. "This is a gamechanger for the geothermal industry," chief executive Tim Latimer said that day. It was also one 33 MW block of a three-block, 100 MW Phase I, and the shares fell 9.2% the following session.
A discount-rate month
The September decline was not geothermal's. From August 28 to September 30 Ormat fell 11.5% and Fervo 5.9%, while Brookfield Renewable fell 11.7%, XPLR Infrastructure 10.8% and Clearway 8.2%; merchant generators Vistra and Talen rose. The 10-year Treasury yield reached 5.21% on September 28, a near 20-year high, and decades of fixed PPA cash flows are discounted off exactly that. Ormat's own damage is older and larger: $145.10 on June 3 to $91.19 at the end of September, though only 4.6% below where it traded a year ago.
The verdict splits cleanly. The fall from June is work the business earns — a leveraged generator at double the multiple of its contracted-power peers, negative free cash flow, and consensus modeling a smaller 2027. The last five weeks are the bond market, shared with every owner of long-dated contracts. What nothing in either company explains is the premise that put them on data-center shelves: Ormat cannot sell today's price into today's market at scale, and Fervo cannot bill for anything yet. If Fervo's cost per kilowatt keeps falling while Ormat's realized price stalls, the two are not a hedge on each other — both need the same discount rate, and only one of them is still getting cheaper to build.
On October 1 the amended Casa Diablo-4 contract starts paying Ormat about a quarter more for one plant's output. The rest of the fleet waits until the next decade.