

Accenture Books 2% Less New Work Into Its First 2027 Guidance, Due October 1
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Accenture has given back everything it gained on the Anthropic evaluation deal and more, and the sell side moved against it in the same stretch: Guggenheim cut the stock to Neutral and 19 of 20 covering analysts trimmed fourth-quarter profit estimates over the last 90 days. On Thursday it issues its first fiscal-2027 guidance.
The three large integrators grow at almost the same rate once currency is stripped out, yet the market has re-rated them apart. Infosys conceded the mechanism: utilization rose and operating margin reached 21.1%, the fattest of the three, while full-year growth guidance was cut to 1.5–3.0% on broad-based client requests for price reductions. The pyramid is not breaking; the price of the work is.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ACN | Accenture | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −8.4% | −27.9% |
INFY | Infosys | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −13.1% | −34.6% |
CTSH | Cognizant Technology Solutions | Enterprise Consulting & Systems Integration | 🌱 Emerging Bull | −11.6% | −14.6% |
| Compared against · context, not the story | |||||
EPAM | EPAM Systems | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −9.7% | −31.3% |
GLOB | Globant | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −17.2% | −43.7% |
WIT | Wipro | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −11.7% | −38.7% |
IT | Gartner | Research & Advisory | 🌱 Emerging Bull | −6.7% | −28.7% |
TCS.NS | Tata Consultancy Services | Information Technology Services | 🔴 Cont. Bear | −13.7% | −26.9% |
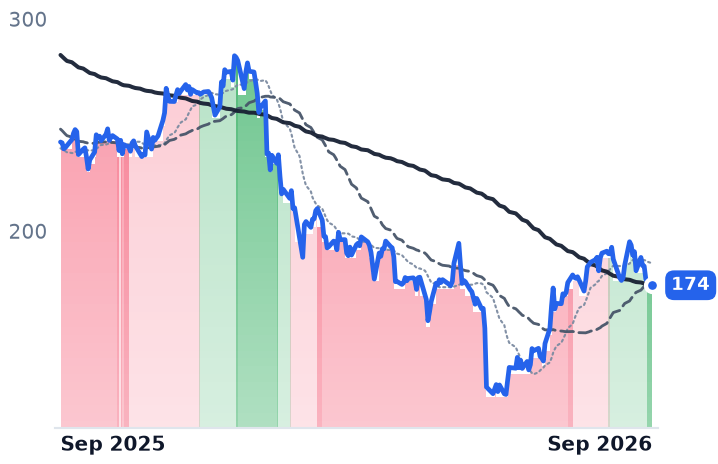
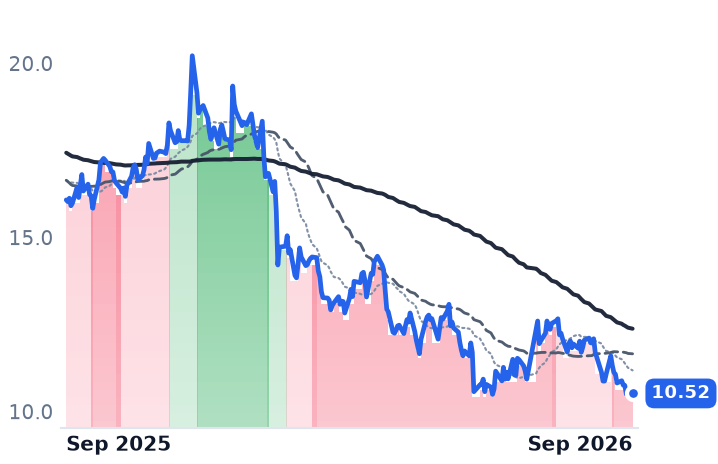
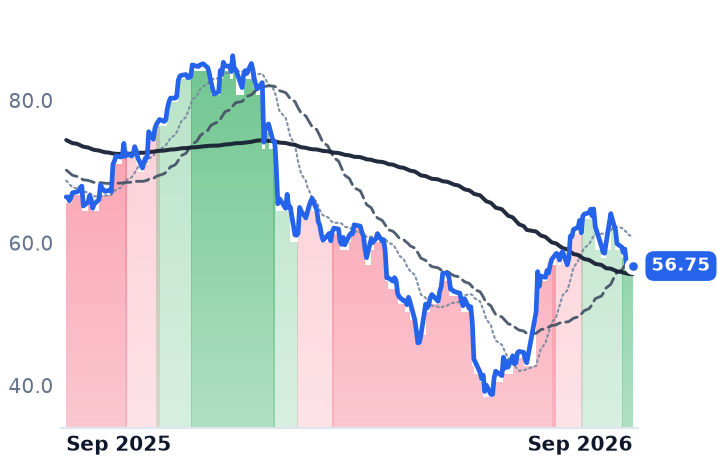
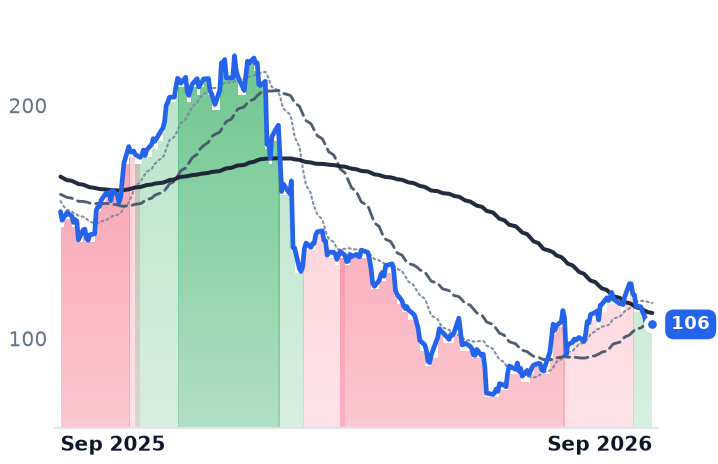
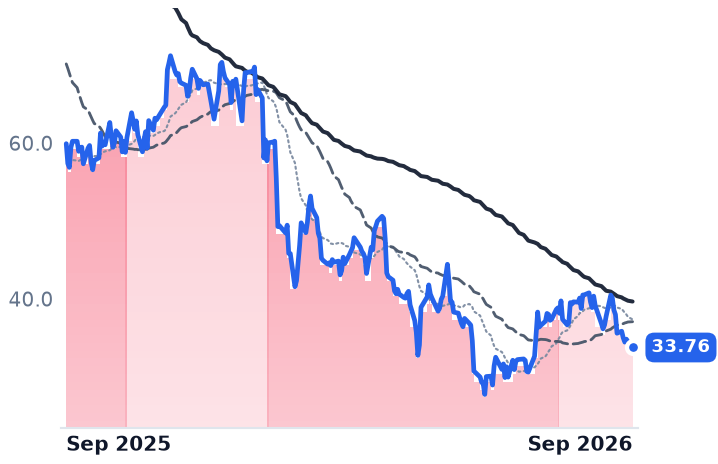
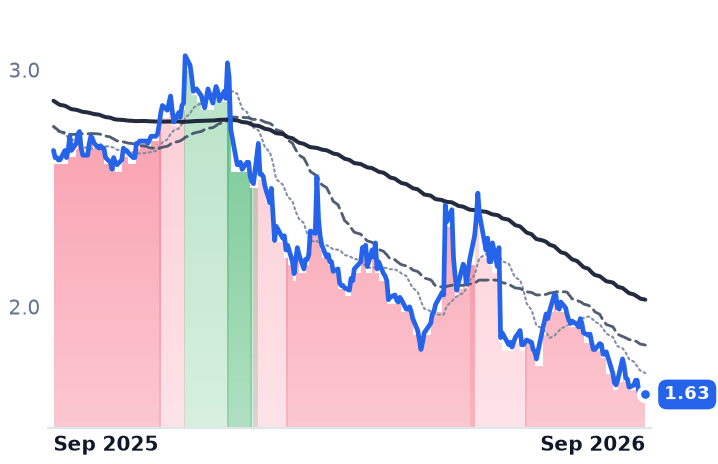
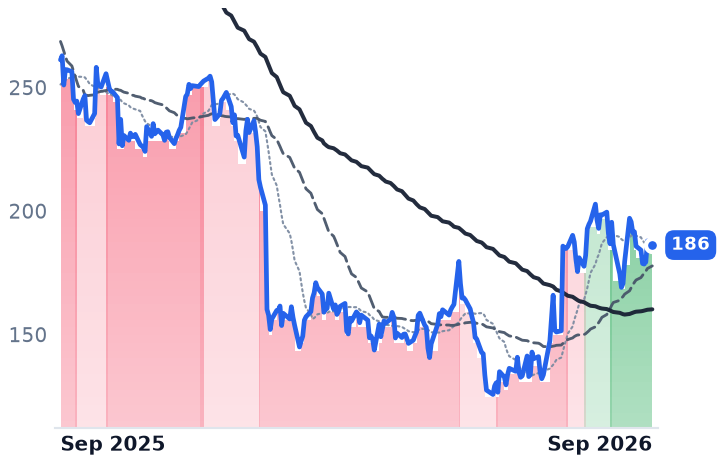
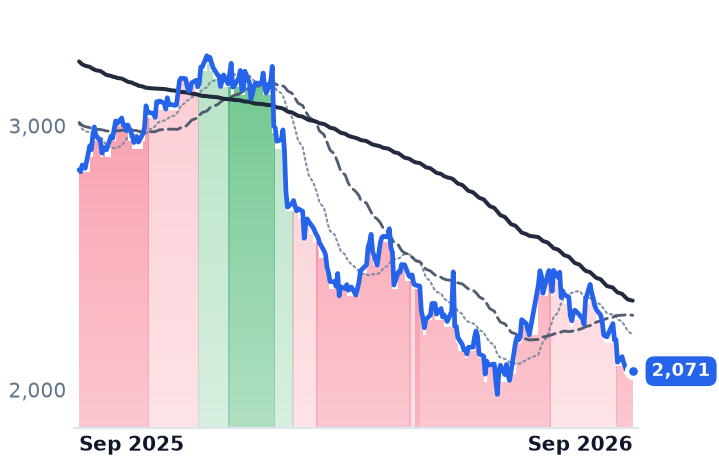
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ACN | $106.8B | 13.8x | 11.9x | 1.5x | 1.4x | 4.6x | 4.4x | 8.3x | 11.8% |
INFY | $42.7B | 12.6x | 13.2x | 2.1x | 2.1x | 6.8x | 6.9x | 8.0x | 9.1% |
CTSH | $25.6B | 12.2x | 9.9x | 1.2x | 1.2x | 3.7x | 3.6x | 6.7x | 10.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EPAM | $6.1B | 15.8x | 8.9x | 1.1x | 1.1x | 3.8x | 3.8x | 8.0x | 7.9% |
GLOB | $1.7B | 15.6x | 6.7x | 0.7x | 0.7x | 2.2x | 2.2x | 6.8x | 18.4% |
WIT | $16.3B | 13.0x | — | 1.7x | — | 5.9x | — | 8.7x | 8.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IT | $9.8B | 13.8x | 10.7x | 1.5x | 1.5x | 2.2x | 2.2x | 9.0x | 12.8% |
TCS.NS | $8.6T | 17.2x | 15.4x | 3.1x | 2.9x | 8.2x | 7.8x | 11.8x | 5.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ACN | Revenue | +5.9% | +3.9% | +4.8% |
| EPS | +7.6% | +5.6% | +6.7% | |
INFY | Revenue | +1.6% | +4.2% | +3.6% |
| EPS | +2.3% | +4.4% | +4.4% | |
CTSH | Revenue | +5.2% | +4.7% | +5.1% |
| EPS | +10.9% | +9.8% | +10.2% | |
EPAM | Revenue | +3.9% | +3.5% | +4.9% |
| EPS | +15.1% | +7.3% | +7.6% | |
GLOB | Revenue | −0.1% | +2.5% | +3.6% |
| EPS | −2.4% | +4.9% | +4.8% | |
WIT | Revenue | +5.4% | +5.1% | +2.6% |
| EPS | +4.6% | +3.7% | +3.7% | |
IT | Revenue | −0.7% | +4.6% | +6.3% |
| EPS | +7.2% | +12.5% | +14.2% | |
TCS.NS | Revenue | +4.0% | +8.9% | +3.9% |
| EPS | +4.0% | +9.1% | +4.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Accenture reports fourth-quarter results on Thursday 1 October and, for the first time, tells investors what it expects of fiscal 2027. It gets there with a shrinking order book: new bookings of $19.32bn in the May quarter, down 2% in dollars and 3% in local currency, on revenue of $18.72bn that missed consensus by $80m.
That guidance is the only scheduled disclosure left this year that speaks to the question the whole sector is priced on: whether artificial intelligence expands enterprise technology budgets or deflates the price of an hour of the work. When Accenture — the Dublin-headquartered consulting and managed-operations firm with 799,000 staff — cut full-year local-currency growth to 3–4% from 3–5% on 18 June, Indian software stocks slumped alongside it. Accenture fell 17.97% that session, EPAM 12.61%, Globant 11.18%, Cognizant 10.49% and the Infosys American depositary receipt 9.66%.
"Because the indirect impact really started in the last few weeks and mostly in discretionary spend, we do think that there will be more impact in Q4, which is why we're saying that more of the range is in play," Chair and Chief Executive Julie Sweet told investors on the 18 June call. Three months earlier she had called AI "a tailwind because it's helping us win more today and take market share".
The recovery split was not about delivery model
From that 18 June close to 28 September, the US-listed integrators came back and the Indian listings did not: Accenture recovered 36.3%, EPAM 38.5%, Cognizant 29.9%, against Infosys at -0.5% and Tata Consultancy at -6.0%. Labour arbitrage does not explain the gap. Cognizant, the Teaneck, New Jersey firm running consulting and outsourcing across financial services, healthcare, products and communications, earns $60,673 of trailing revenue per employee across 356,700 staff — within about $1,200 of Infosys's $61,869. Accenture earns $91,489.
Infosys, the Bengaluru outsourcer that sells application and operations work plus its Topaz AI suite and Finacle core-banking product, conceded on price. June-quarter revenue of $5,082m grew 2.4% in constant currency, and full-year guidance was narrowed to 1.5–3.0% from 1.5–3.5% against the 3.4% analysts had modelled. The pyramid held: utilization excluding trainees rose 1.9 percentage points to 84.9%, headcount was flat at 328,062, and operating margin reached 21.1%, above Accenture's 17.0% and Cognizant's 16.0%. What gave was the rate. Management described client requests for price reductions as broad-based across telecom, financial services, retail and utilities, arriving at renewal or mid-contract. "Over 80,000 employees are working today on coding tools such as Cloud Codex for our clients," chief executive Salil Parekh said on the 23 July call — the productivity the client is now pricing. Fixed-price contracts were 54% of revenue in the March quarter, the book where that productivity becomes revenue no longer billed.
Cognizant runs the same offshore model and was treated as the opposite case. June-quarter revenue of $5.48bn grew 4.1% in constant currency, operating income rose 7%, and trailing-twelve-month bookings reached $29.1bn. Full-year constant-currency revenue guidance was trimmed to 4.0–5.5% while adjusted earnings guidance was raised to $5.70–$5.82.
What the week did
Accenture's 50-day average crossed above its 200-day only because June's crash rolled out of the lookback; the shares fell 7.0% in the week to 28 September and sit 9.8% below their 15 September high, having surrendered the entire pop from the $1bn Anthropic model-evaluation commitment, including a 3.3% drop on 24 September. Guggenheim's Jonathan Lee downgraded the stock to Neutral, citing deal timelines pushed into fiscal 2027.
At 13.82x trailing and 11.92x forward earnings, Accenture is cheaper than at any of its last five fiscal year-ends, the nearest of which was 21.4x. Cognizant is cheaper still at 9.85x forward, below the 14–15x that looked undemanding in May. Infosys is the only one of the three whose forward multiple, 13.22x, sits above its trailing 12.56x — because consensus fiscal-2027 earnings of $0.796 a share are below the $0.83 it delivered last year.
So the split is not a growth-differential story: constant-currency growth is within two points across all three. It is a story about which direction forward estimates are moving. Cognizant's earnings guidance went up as its price fell; Infosys's went down and its price went with it; Accenture's shares recovered a third of their value on no new disclosure at all, while every disclosure it does have — bookings, guidance, analyst estimates — got worse. Deflation of roughly 2–3% a year in traditional services pricing sits underneath all of it, against Gartner's forecast of $6.31trn of worldwide technology spending in 2026. The budget grows; the price of the hour falls.
Thursday is the first morning since June that Accenture has to put a number on next year. Infosys reports on 23 October, Cognizant on 4 November.