

Amkor Took a $1.5bn Nvidia Prepayment and Lifted Its Arizona Build to $12bn
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Amkor's shares have been marked down by more than a third since June while its reported numbers accelerated — June-quarter revenue up 25.6% year over year and gross margin 4.75 points wider. Three weeks ago the company committed to far more capacity anyway.
The squeeze is memory. DRAM wafers diverted to high-bandwidth memory for AI servers have starved Amkor's phone system-in-package line of parts to assemble, and the same shortage is paying ChipMOS, whose memory revenue rose 46.7% year over year with factory utilization falling. ASE, the largest of the three, raised advanced-packaging quotes by more than 20% in July and ran its assembly-and-test arm at a record 27.3% gross margin.
The repricing is real at the leading edge. What Amkor's discount reflects is the phone book, not the AI book — and Arizona does not produce until 2028.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
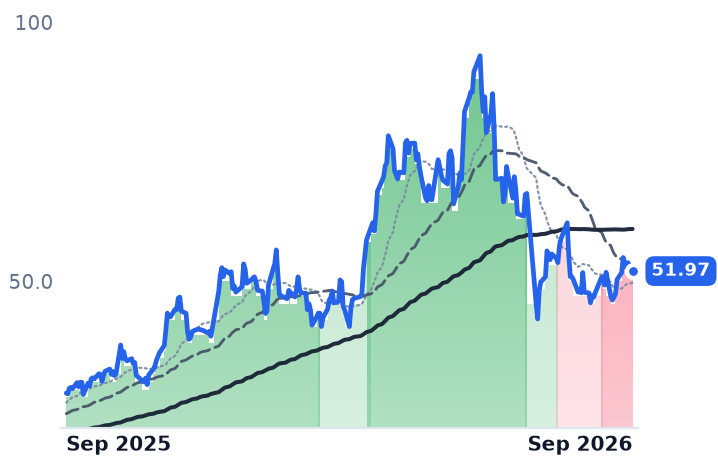
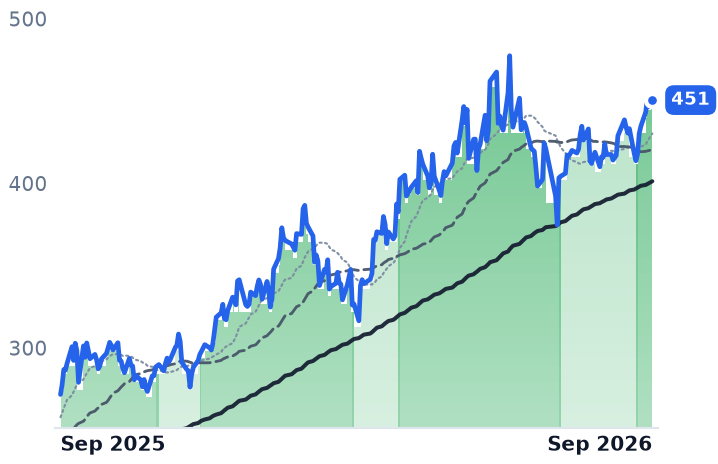
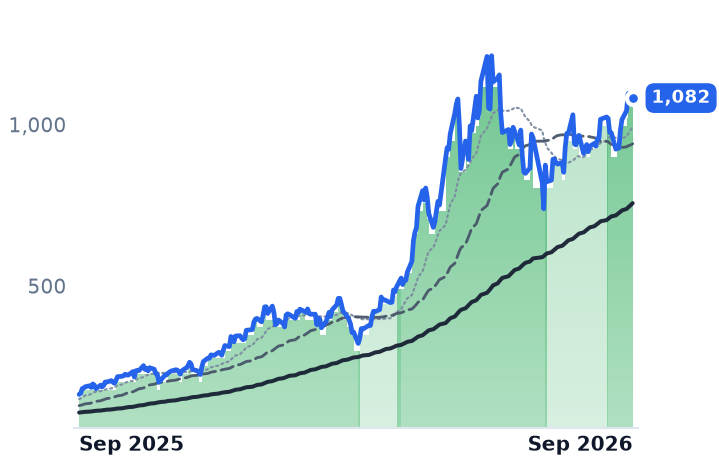
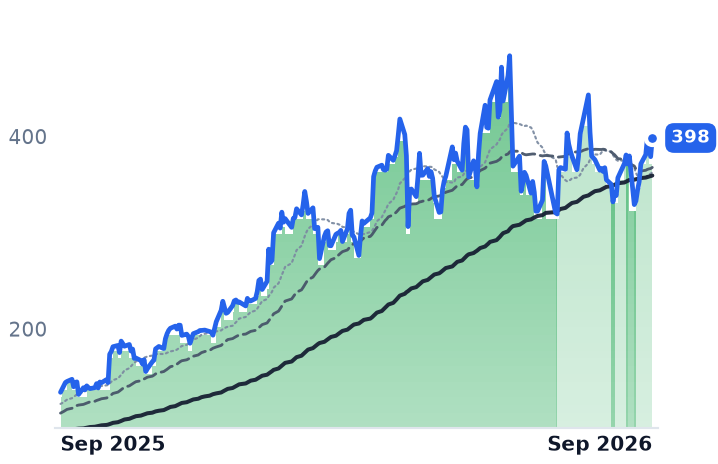
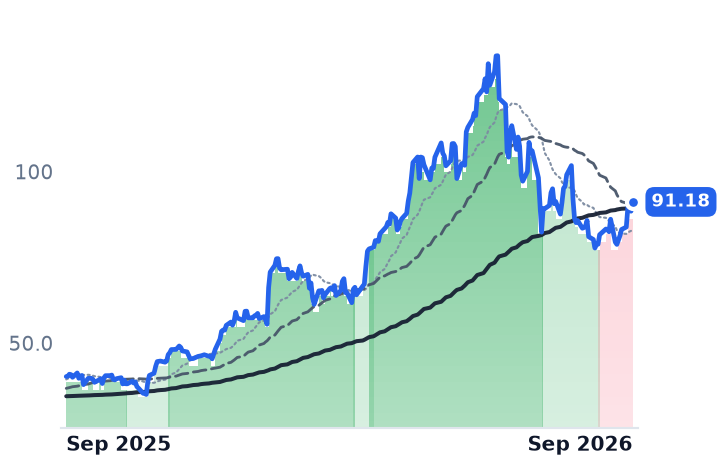
AMKR | Amkor Technology | Packaging & Assembly | ⚠️ Emerging Bear | +8.9% | +83.0% |
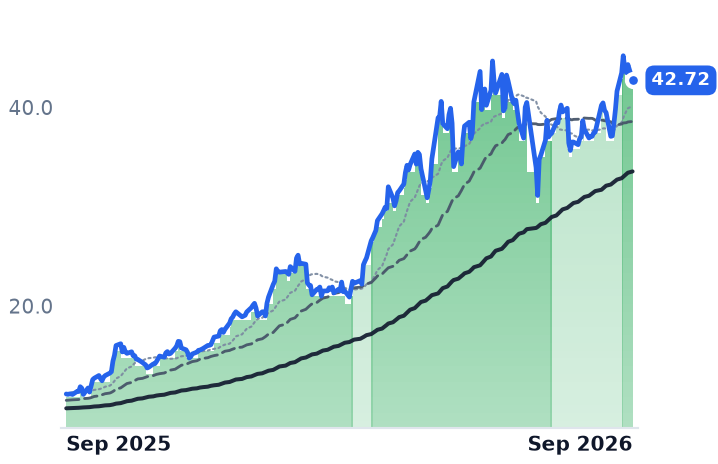
ASX | ASE Technology | Packaging & Assembly | 🟢 Cont. Bull | +15.7% | +283.8% |
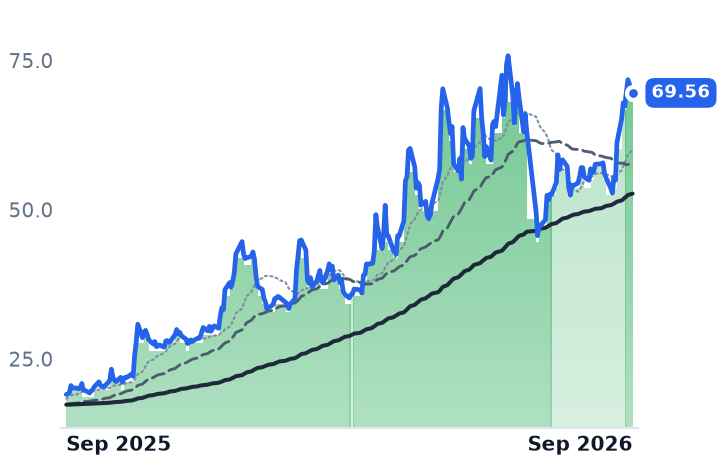
IMOS | ChipMOS TECHNOLOGIES | Packaging & Assembly | 🟢 Cont. Bull | +26.6% | +265.2% |
| Compared against · context, not the story | |||||
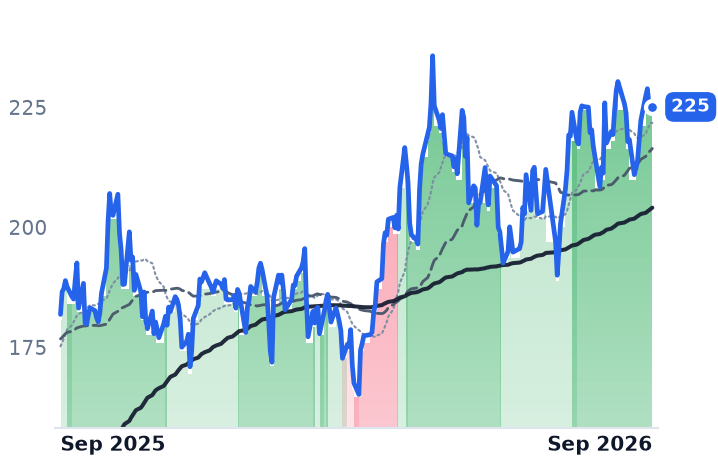
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +2.3% | +23.8% |
TSM | Taiwan Semiconductor Manufacturing | Logic Foundries | 🟢 Cont. Bull | +7.9% | +65.8% |
MU | Micron Technology | Memory (DRAM/NAND) | 🟢 Cont. Bull | +14.9% | +561.3% |
TER | Teradyne | Semiconduct Equipment | 🟢 Cont. Bull | +13.8% | +196.9% |
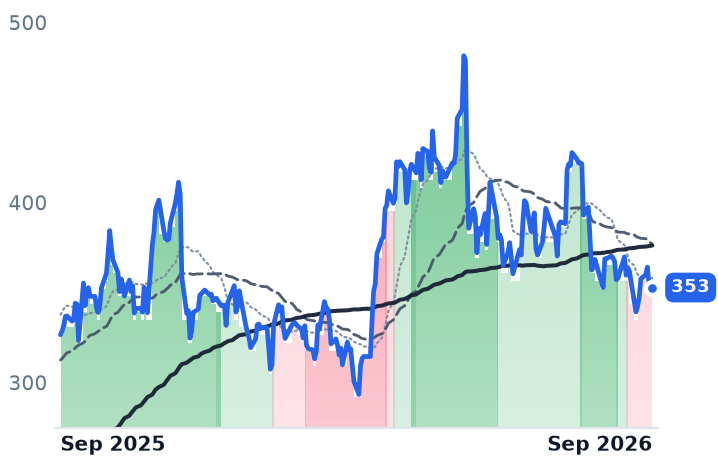
KLIC | Kulicke and Soffa Industries | Semiconduct Equipment | ⚠️ Emerging Bear | +13.7% | +126.5% |
ONTO | Onto Innovation | Semiconduct Equipment | 🟢 Cont. Bull | +7.3% | +120.6% |
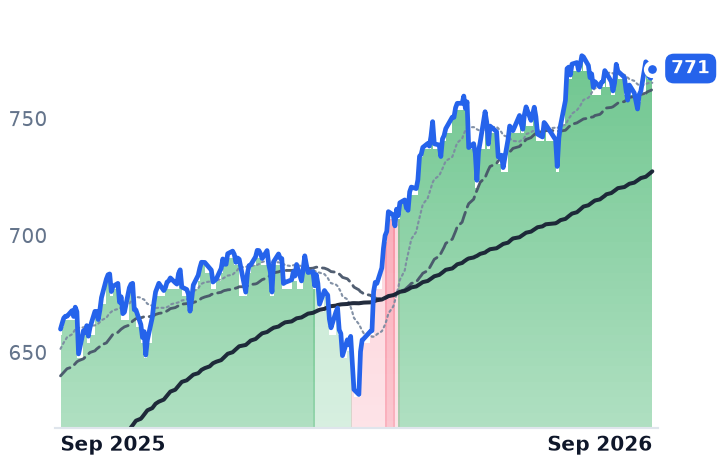
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.7% | +16.9% |
AVGO | Broadcom | Semiconductor Subsystems | 🟢 Cont. Bull | −4.7% | +8.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMKR | $12.9B | 23.2x | 20.2x | 1.7x | 1.7x | 11.2x | 10.9x | 10.0x | 4.0% |
ASX | $93.9B | 50.3x | — | 4.3x | — | 22.2x | — | 21.3x | -1.0% |
IMOS | $2.4B | 35.0x | — | 2.9x | — | 19.6x | — | 10.5x | -0.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
TSM | $2.2T | 27.9x | — | 14.1x | — | 21.9x | — | 18.5x | 1.8% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TER | $60.8B | 53.1x | 42.2x | 13.6x | 11.8x | 23.0x | 19.9x | 41.7x | 1.3% |
KLIC | $5.3B | 46.0x | 29.8x | 5.6x | 4.9x | 11.6x | 10.2x | 31.1x | 0.8% |
ONTO | $13.4B | 100.3x | 33.2x | 11.9x | 9.3x | 23.7x | 18.5x | 51.4x | 1.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
AVGO | $1.7T | 45.0x | 31.1x | 19.4x | 16.3x | 28.6x | 24.1x | 33.7x | 2.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AMKR | Revenue | +14.7% | +12.8% | +10.1% |
| EPS | +103.7% | +8.9% | +19.2% | |
ASX | Revenue | +27.2% | +25.4% | +15.9% |
| EPS | +110.4% | +52.3% | +28.1% | |
IMOS | Revenue | +26.1% | +15.5% | +15.6% |
| EPS | +791.1% | +42.8% | +19.7% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
TSM | Revenue | +42.0% | +34.4% | +26.0% |
| EPS | +65.5% | +30.7% | +26.5% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
TER | Revenue | +67.1% | +21.2% | +24.5% |
| EPS | +159.3% | +27.3% | +31.7% | |
KLIC | Revenue | +66.9% | +19.5% | +6.4% |
| EPS | +2317.8% | +29.8% | +1.7% | |
ONTO | Revenue | +2.2% | +43.0% | +30.3% |
| EPS | −5.1% | +63.1% | +44.2% | |
AVGO | Revenue | +67.1% | +63.9% | +62.1% |
| EPS | +73.0% | +64.9% | +58.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Amkor Technology, which assembles and tests other companies' chips for a fee rather than designing any, told the market on 8 September that it would raise planned investment in its Peoria, Arizona campus from about $7bn to roughly $12bn, adding some 60,000 square meters of cleanroom. The reason given was that customer commitments had already exceeded the 33,000 square meters planned for the first phase.
Part of the money is somebody else's. Nvidia has committed a $1.5bn prepayment — cash against future capacity, not an equity stake — to fund the US expansion and move packaging technology from Korea to Arizona. The campus also carries $407m of funding under the CHIPS and Science Act, lists Apple and Nvidia as lead customers, and finishes construction in mid-2027 for production starting in early 2028. The spend is now; the revenue is three years out. And Amkor is making that commitment while the market has cut its valuation in half.
One shortage, two directions
Amkor's June quarter was its best in years: revenue of $1.898bn, up 25.6%, with net income more than tripling and gross margin widening from 12.0% to 16.8%. "Amkor delivered record second quarter revenue and strong profitability, with record revenue in our Computing and Automotive & Industrial end markets," chief executive Kevin Engel said on 27 July. The shares fell more than 10% anyway, on a third-quarter guide of $1.95–2.05bn against a $2.12bn consensus.
What broke was the phone line. Amkor guided communications revenue down high-single-digits on the shift of system-in-package work to Vietnam, "ongoing memory supply constraints" and changed customer build patterns, with Android revenue already down 20%. Memory makers have diverted wafers to high-bandwidth memory for AI servers; conventional DRAM contract prices rose about 90% in the first quarter of 2026 alone. Amkor cannot assemble modules around chips its customers cannot buy.
ChipMOS, the smallest of the three, sits on the other side of the same trade. It packages memory and display driver chips, and its August revenue rose 33.3% year over year on what the company called strong memory demand led by a persistent AI-related imbalance. Memory reached 51% of revenue in the June quarter, up 46.7%, and gross margin went from 6.6% to 18.0% — while utilization fell from 84% to 78%. "Better pricing, product mix, and utilization are now translating demand strength into meaningful operating leverage," chairman S.J. Cheng told investors on the 11 August call. Margin up on fewer loaded machines is price, not volume.
What ASE is charging
ASE Technology, the world's largest outsourced assembler, raised advanced-packaging quotes by more than 20% in July, covering the chip-on-wafer work that AI accelerators need. Its assembly-and-test arm set a record at TWD 126.1bn in the June quarter at a 27.3% gross margin, producing 94% of group operating profit on 66% of revenue; the electronic manufacturing services arm contributed a third of sales and almost nothing to profit. Chief operating officer Tien Wu described the company on the 30 July call as being in "a very awkward and peculiar position because we're capacity-constrained." ASE lifted capital spending by a further $2bn, to about $10.5bn, and its trailing free cash flow has turned negative.
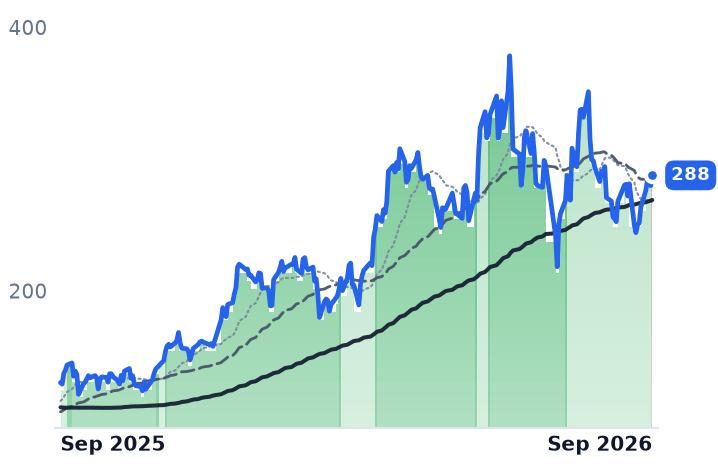
The three trade as though only two are in the same business. Amkor is at 10.0x trailing enterprise value to EBITDA and 20.2x forward earnings, its trailing price-to-earnings ratio down to 23.2x from 44.4x in May even as trailing profit rose. ChipMOS is at 10.5x on the same EBITDA measure and, converting Taiwan-dollar consensus at the rate implied by its ADR, roughly 24x 2026 earnings. ASE is at 21.3x EBITDA and about 37x 2026 earnings — more than double its peers on the first measure. Over twelve months Amkor has risen 79%, against 283% for ASE and 269% for ChipMOS, and it sits 39% below its 25 June close with its 50-day average under its 200-day.
The verdict
Packaging is genuinely being repriced: ASE's quote increase and ChipMOS's eleven-point margin gain on falling utilization are both price and mix, and that is broader than AI packaging alone. Amkor earns the same tailwind in computing and gets taxed by memory scarcity in phones, which is what its discount reflects — not a verdict on its AI book. The Arizona decision converts it from a cyclical earner into a capital-spending story with an anchor customer's cash on the balance sheet and no revenue until 2028.
Micron reports on 30 September. How much DRAM it is willing to sell to anyone not building an AI server sets the sign on two of these three companies at once.