

Starbucks Is Closing 250 North America Cafes and Cut Its 2026 Openings to 440
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Starbucks is shrinking its home market in the same year its sales line is running strongest in years. On 24 September it confirmed about 250 North America cafe closures and roughly $300m of charges, and cut fiscal-2026 net new stores to about 440 — all of them international.
The June quarter was not weak: North America comparable sales rose 8.1% on transactions up 4.5%, segment operating margin widened to 13.6% from 13.3%, and full-year adjusted earnings guidance was raised to $2.55–$2.65 from $2.25–$2.45. The comp is being bought, with more than $500m of added barista hours and now lease exits.
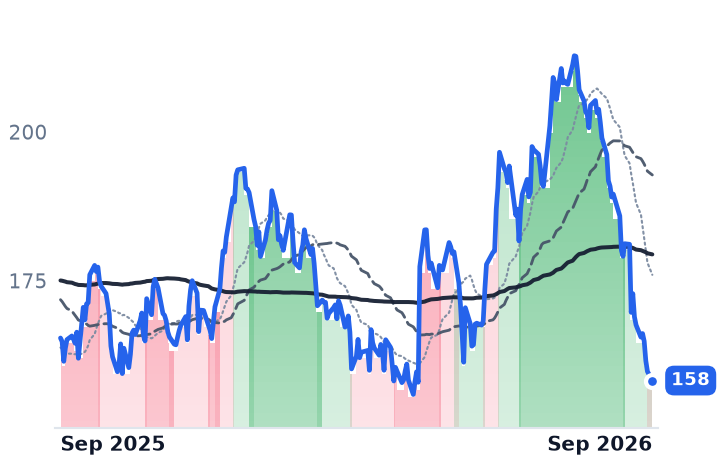
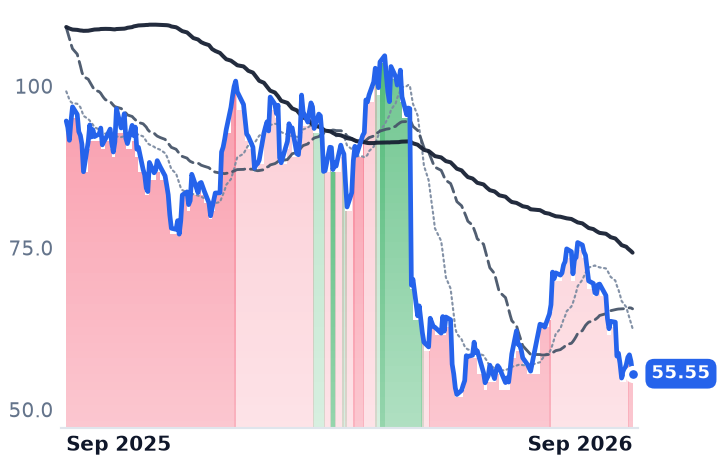
At roughly 36 times the fiscal-2026 consensus of $2.61 — still a fifth below the $3.31 Starbucks earned in fiscal 2024 — the shares pay in advance for a recovery not yet delivered. Dutch Bros, de-rated harder on raised guidance, is the harder case to explain.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
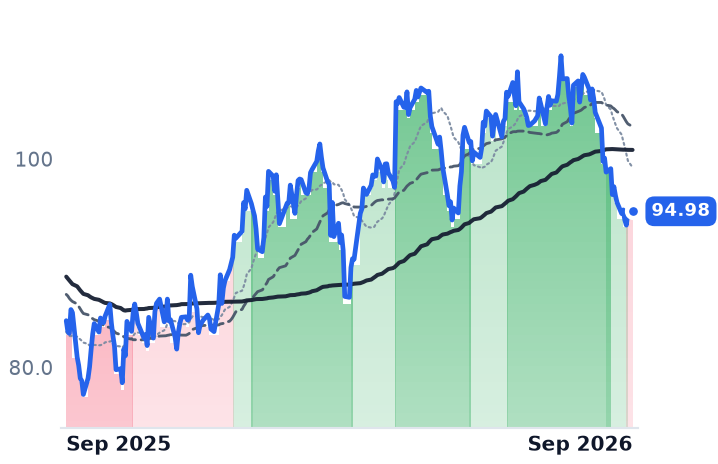
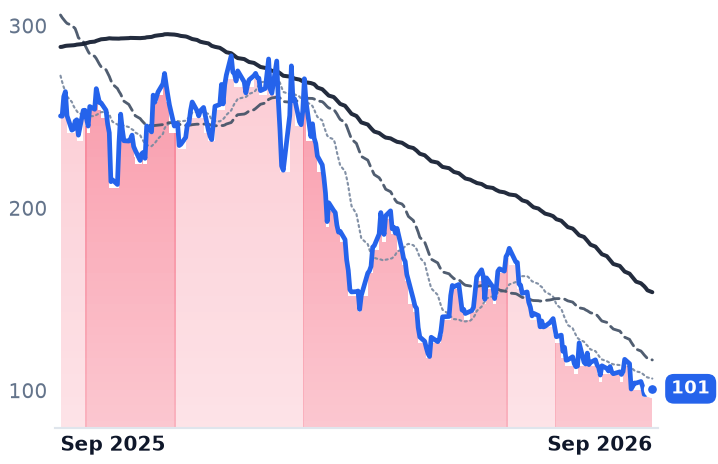
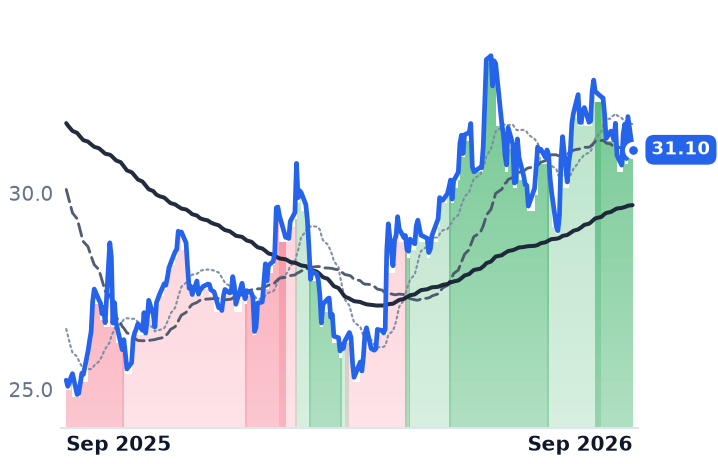
SBUX | Starbucks | Coffee & Beverages | 🟢 Cont. Bull | −11.0% | +12.4% |
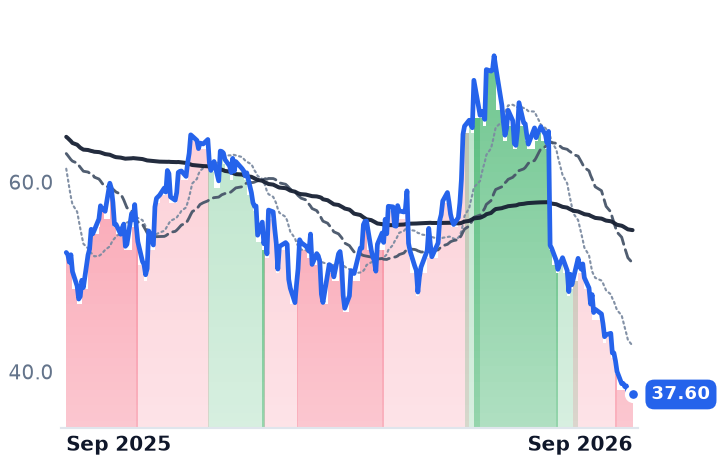
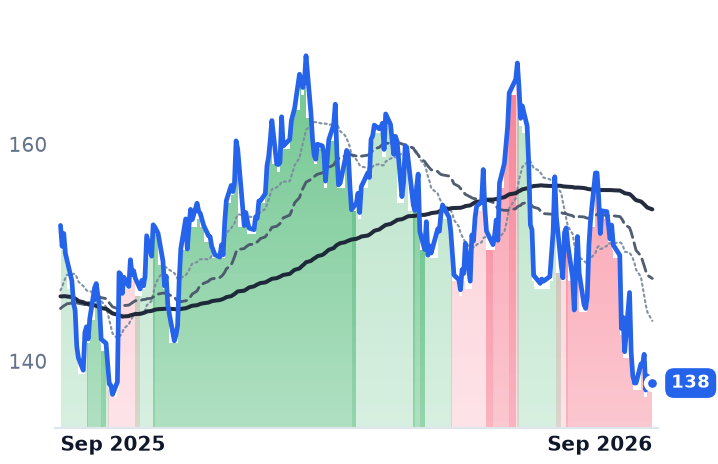
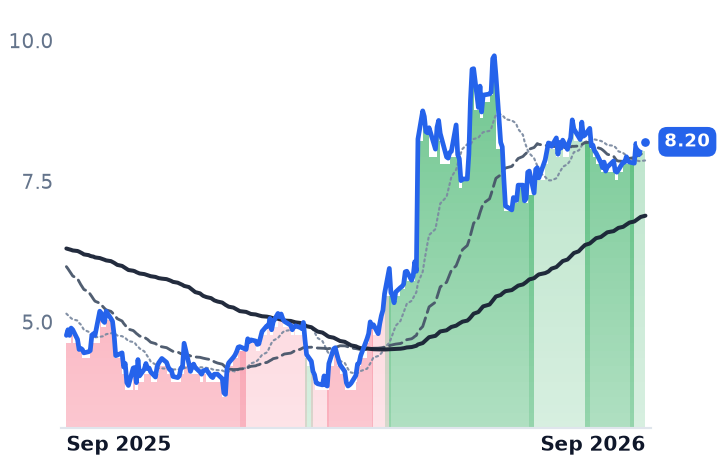
BROS | Dutch Bros | Coffee & Beverages | 🔴 Cont. Bear | −23.0% | −28.5% |
| Compared against · context, not the story | |||||
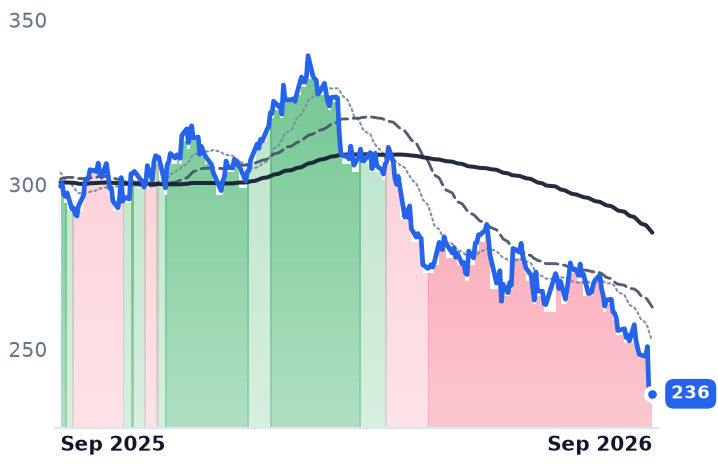
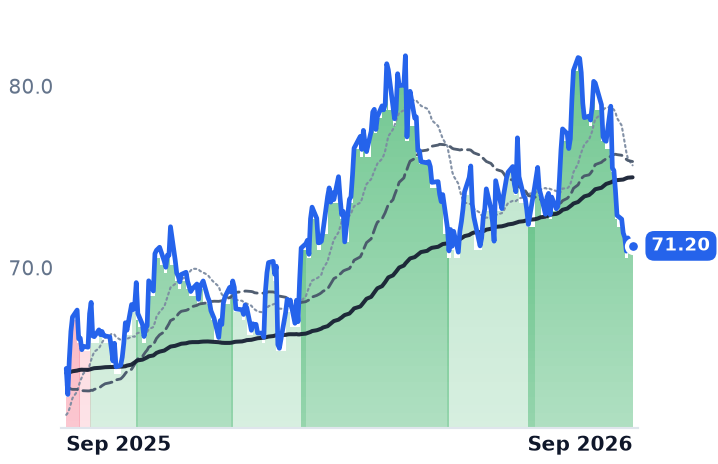
MCD | McDonald's | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −10.8% | −21.0% |
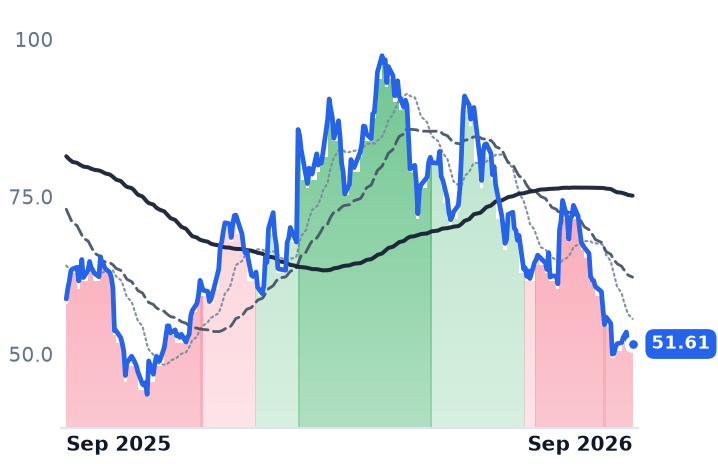
CAVA | CAVA | Quick Service - Mexican & Bowls | ⚠️ Emerging Bear | −21.8% | −12.2% |
TXRH | Texas Roadhouse | Casual Dining - Steakhouse & Seafood | 🌱 Emerging Bull | −19.4% | −4.3% |
SHAK | Shake Shack | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −20.1% | −41.3% |
DPZ | Domino's Pizza | Quick Service - Pizza | 🔴 Cont. Bear | −16.6% | −32.4% |
CMG | Chipotle Mexican Grill | Quick Service - Mexican & Bowls | 🌱 Emerging Bull | −16.8% | −20.7% |
WING | Wingstop | Quick Service - Chicken & Wings | 🔴 Cont. Bear | −10.0% | −59.7% |
YUM | Yum! Brands | Quick Service - Pizza | ⚠️ Emerging Bear | −10.3% | −9.5% |
QSR | Restaurant Brands International | Quick Service - Pizza | 🟢 Cont. Bull | −9.1% | +10.5% |
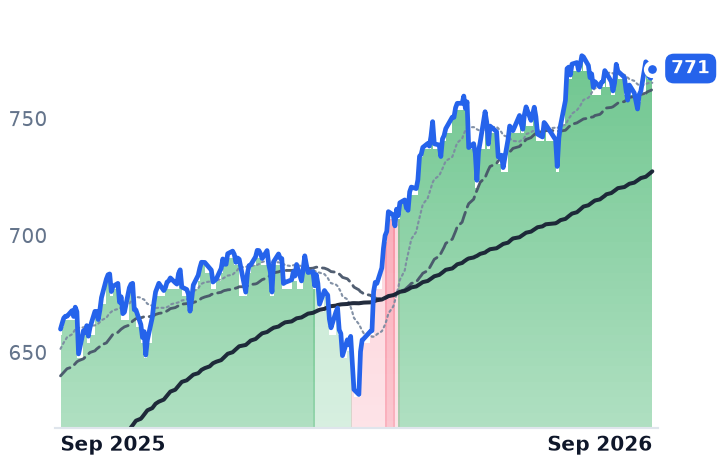
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.1% | +15.9% |
KDP | Keurig Dr Pepper | Coffee & Diverse Beverages | 🟢 Cont. Bull | −2.2% | +23.3% |
WEST | Westrock Coffee Company, LLC | Coffee & Beverages | 🟢 Cont. Bull | +4.7% | +72.3% |
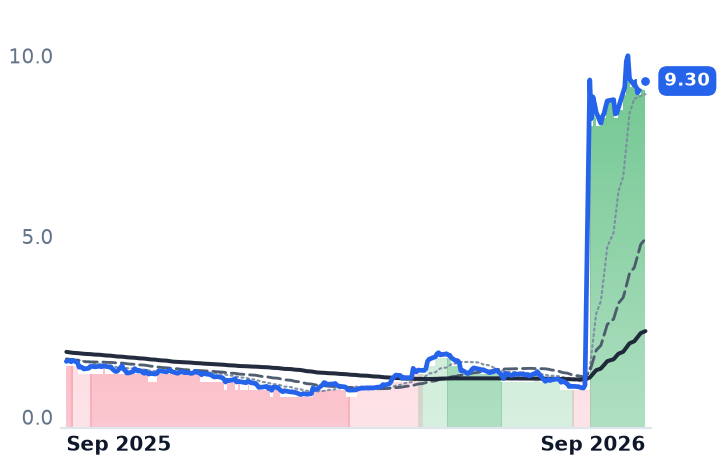
BRCC | BRC | Coffee & Beverages | 🟢 Cont. Bull | +14.4% | +503.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SBUX | $108.6B | 54.8x | 30.3x | 2.8x | 2.8x | 8.9x | 8.9x | 21.7x | 3.4% |
BROS | $6.5B | 52.4x | 39.4x | 3.5x | 3.1x | 13.8x | 12.2x | 25.1x | 1.5% |
MCD | $168.0B | 19.2x | 18.3x | 6.1x | 6.0x | 10.6x | 10.4x | 14.8x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CAVA | $6.5B | 97.6x | 102.4x | 4.7x | 4.3x | 23.5x | 21.5x | 39.5x | 0.8% |
TXRH | $11.9B | 28.9x | 27.4x | 1.9x | 1.8x | 12.5x | 11.9x | 16.7x | 3.4% |
SHAK | $2.2B | 56.5x | 49.0x | 1.4x | 1.4x | 5.6x | 5.3x | 12.3x | 0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DPZ | $11.1B | 18.9x | 17.7x | 2.2x | 2.1x | 5.5x | 5.3x | 16.2x | 5.9% |
CMG | $41.9B | 29.2x | 28.7x | 3.5x | 3.2x | 9.5x | 8.9x | 20.5x | 3.6% |
WING | $3.5B | 31.7x | 28.3x | 5.0x | 4.5x | 6.0x | 5.5x | 15.4x | 3.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
YUM | $38.0B | 17.2x | 21.0x | 4.4x | 4.3x | 9.5x | 9.3x | 17.2x | 4.4% |
QSR | $25.0B | 17.6x | 17.8x | 2.6x | 2.5x | 5.8x | 5.7x | 14.2x | 6.3% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KDP | $39.4B | 21.5x | 12.7x | 2.3x | 1.5x | 4.3x | 2.8x | 17.3x | 4.0% |
WEST | $756.1M | n/m | — | 0.6x | 0.6x | 4.6x | 4.9x | 23.8x | -2.1% |
BRCC | $278.4M | n/m | 47.3x | 0.6x | 0.6x | 1.9x | 1.9x | 87.5x | 2.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SBUX | Revenue | +2.8% | +1.6% | +5.0% |
| EPS | +21.4% | +20.4% | +18.9% | |
BROS | Revenue | +31.7% | +24.6% | +21.4% |
| EPS | +39.2% | +32.9% | +27.7% | |
MCD | Revenue | +5.7% | +4.9% | +3.1% |
| EPS | +6.4% | +7.9% | +6.6% | |
CAVA | Revenue | +28.3% | +20.8% | +20.5% |
| EPS | +3.5% | +36.2% | +38.8% | |
TXRH | Revenue | +11.0% | +9.3% | +8.6% |
| EPS | +4.7% | +18.3% | +20.8% | |
SHAK | Revenue | +14.1% | +14.7% | +13.3% |
| EPS | −12.2% | +22.8% | +27.3% | |
DPZ | Revenue | +5.4% | +2.4% | +3.9% |
| EPS | +7.6% | +9.8% | +8.0% | |
CMG | Revenue | +9.0% | +11.0% | +10.9% |
| EPS | −1.6% | +19.6% | +18.0% | |
WING | Revenue | +11.6% | +15.4% | +14.1% |
| EPS | +17.0% | +22.2% | +24.3% | |
YUM | Revenue | +9.4% | +3.2% | +5.8% |
| EPS | +8.1% | +10.2% | +11.0% | |
QSR | Revenue | +5.2% | +0.5% | +0.4% |
| EPS | +10.3% | +9.1% | +9.4% | |
KDP | Revenue | +59.5% | +13.5% | +3.0% |
| EPS | +11.4% | +10.2% | +6.2% | |
WEST | Revenue | +5.9% | +7.7% | — |
| EPS | −49.5% | −106.6% | — | |
BRCC | Revenue | +9.3% | +8.0% | +16.6% |
| EPS | −118.5% | +337.8% | +9.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
On 24 September Starbucks said it would close about 250 underperforming cafes in North America, from a base of more than 18,000, and take roughly $300m of restructuring charges — around $200m for early lease exits and separation pay, $100m in non-cash asset disposal and impairment. The same announcement cut the fiscal-2026 net new store target to about 440 from 600–650, with all of the net openings international. The company said the closing stores were ones where it would be "unable to create the physical environment our customers and partners expect" or saw no path to financial performance.
The home market is therefore being made smaller in the year its sales line is running strongest since the slump — and that is the trade underneath chairman and chief executive Brian Niccol's turnaround. Comparable sales are being bought with labour hours, remodels and now lease terminations, while the shares change hands at about 36 times the fiscal-2026 consensus of $2.61 a share, a figure still 21% below the $3.31 Starbucks earned in fiscal 2024.
The comp is real, and it has a price
In the June quarter North America comparable sales rose 8.1%, led by a 4.5% gain in transactions against 3.5% in average ticket — more visits, at higher prices, simultaneously, which is the harder combination. North America segment operating margin widened to 13.6% from 13.3%, credited to sales leverage, lapping the prior-year Leadership Experience event, and lower inflation paired with tariff refunds. "Our Back to Starbucks plan was built on the belief that an extraordinary cup of coffee, human connection and customer experience win the day, every day. Our third quarter results are proof they do," Niccol said in the 29 July results release. Full-year adjusted earnings guidance went up that day, to $2.55–$2.65 from $2.25–$2.45.
The cost side is disclosed too: Starbucks has committed over $500m of incremental labour spending across twelve months, a figure RBC said exceeded its modelling when it cut the stock to Sector Perform in March. And the reported top line no longer describes the same company: consolidated revenue fell 1.4% to $9.32bn even with comps up, because China was deconsolidated after Boyu Capital bought 60% of the retail operations in a $4bn deal that closed in April, moving 7,991 coffeehouses to a licensed model with Starbucks keeping 40% and the brand.
Not a coffee problem
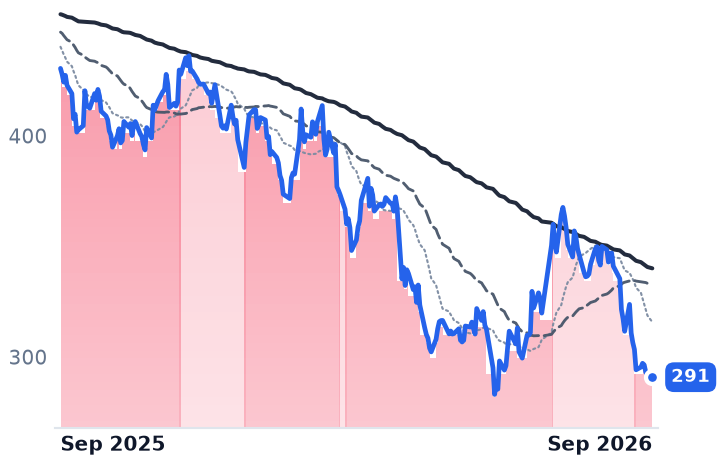
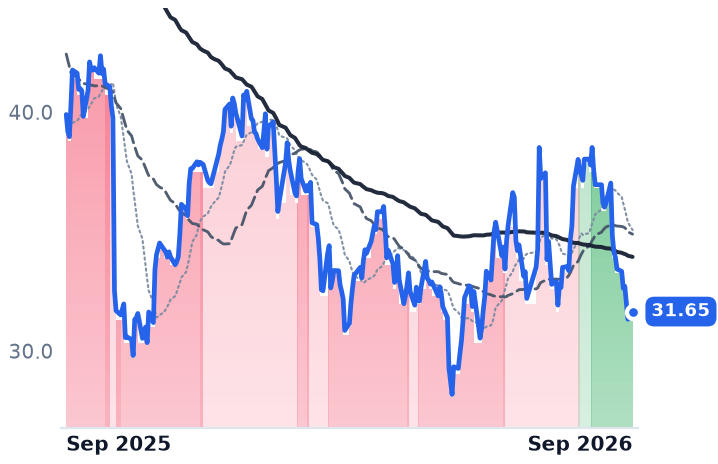
The shares are down 11.9% over thirty days to $94.98, and they fell 0.5% on the closure announcement itself — the de-rating preceded the news. Starbucks is also mid-pack: over the same window Cava fell 22.9%, Texas Roadhouse and Shake Shack 20.5% each, Domino's 16.9%, Chipotle 16.8% and McDonald's 10.8%, against 0.6% for the S&P 500 tracker. Placer.ai counted August restaurant visits down 2.4% year on year while total retail visits rose 0.3%, with gasoline above $4 a gallon and food-away-from-home prices up 3.4% — though a Labor Day shift out of the month flatters the decline. The bean is not the culprit: arabica closed at $2.71 a pound on 23 September, down 28.2% in thirty days from a 52-week high of $4.23, the 50% tariff on Brazilian coffee has been zero since November 2025, and packaged-coffee names barely moved, Keurig Dr Pepper down 3.3%.
The one that fell twice as far
Dutch Bros, the drive-thru beverage chain with 1,225 shops, fell 24.7% over the same thirty days and 47.7% over three months. Its June quarter grew revenue 32.5% to $550.9m, posted a thirteenth straight positive same-shop quarter at 5.8%, transactions up 3.4%, and a record $2.2m systemwide average unit volume, and raised full-year guidance to $2.10–$2.13bn of revenue and $385–$390m of adjusted earnings before interest, taxes, depreciation and amortization. The soft edge was third-quarter comp guidance of 4% to 5%, which cost the shares 18.4% in a single session on 6 August, and a beverage, food and packaging line up 80 basis points to 26.1% of shop revenue on higher coffee costs — 2025's record beans reaching the profit and loss now, with more pressure guided for the second half.
The verdict
A sector-wide traffic repricing hit both, but only one of them was carrying a recovery premium into it. Starbucks at 54.8 times trailing earnings and 21.7 times enterprise value to trailing earnings before interest, taxes, depreciation and amortization, against McDonald's at 19.2 times trailing earnings and 14.8 times, is being asked to pay for margins it has not rebuilt — consensus has revenue up 2.8% this fiscal year and 1.6% next, so the whole case is margin. That part of the fall the multiple earns. Dutch Bros is the harder one: its forward multiple has compressed from about 74.9 times the 2026 consensus in late June to 39.4 times now while that consensus rose, leaving 39.4 times against expected earnings growth of 39% — roughly one times growth, where McDonald's sits near three. Its weak point is cash, not demand: a trailing free-cash-flow yield of 1.46% against Starbucks' 3.35%, with 185-plus shops a year to fund at about $1.4m each.
Closing 250 cafes to make the remaining ones work is a coherent plan, and it is the second time in two years Starbucks has paid to shrink toward it — last September's round cost about $1bn. The fiscal fourth quarter will be the first to carry both the new charge and a North America store count moving the other way from its comp.