

Utilities Signed 15% Fewer Pounds at a Record $96.50, and Cameco Raised Its Guidance
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The uranium equities have been marked down all year on a premise the fuel market does not support: the price utilities actually contract at reached a nominal record last month, above the 2007 peak, and spot is roughly where it started the year. What moved instead was the discount rate — the 30-year Treasury yield broke 5.5% on 25 September, its highest since 2004.
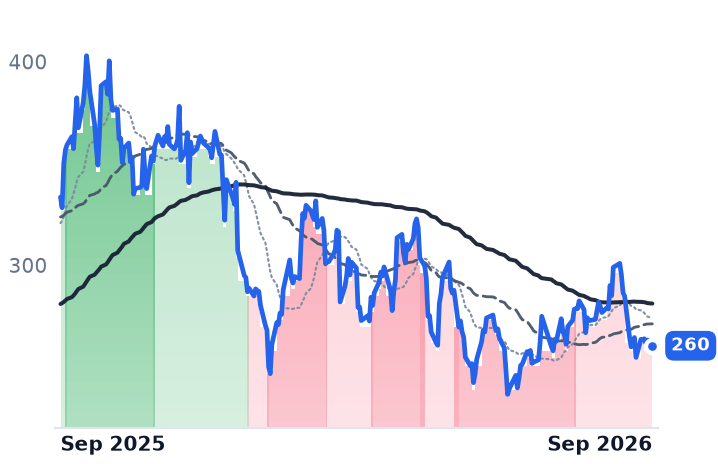
The cross-section ranks by distance to cash flow, not exposure to the pound. Cameco lifted 2026 realized-price guidance to C$91–96 a pound from C$85–89 and is the only name higher over twelve months; Centrus is the one genuine casualty, with separative-work volumes down 23% and its Department of Energy contract cut to a $15.0m caretaking option that expires 30 September; Uranium Energy booked no revenue because it refused to sell.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
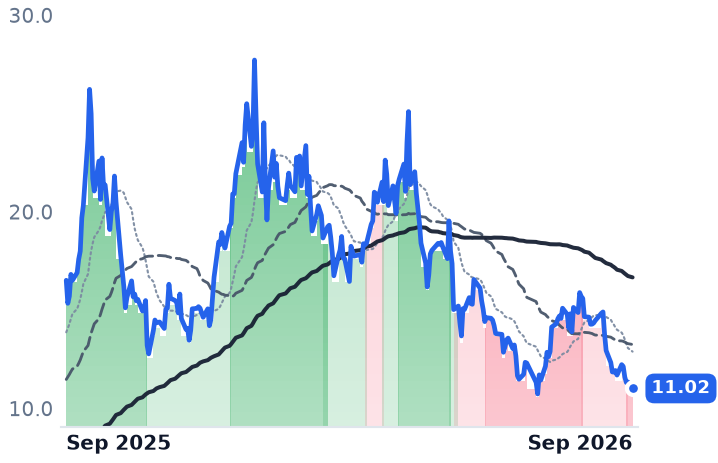
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −11.1% | +3.3% |
UEC | Uranium Energy | Uranium | 🔴 Cont. Bear | −24.9% | −33.7% |
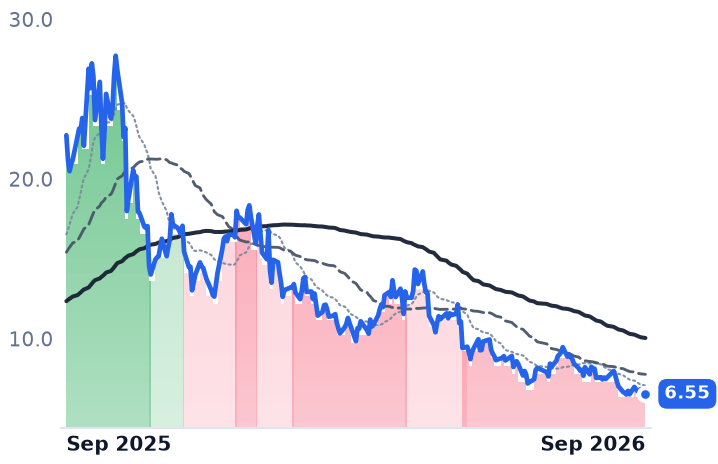
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −19.5% | −55.5% |
| Compared against · context, not the story | |||||
URA | Global X - Uranium ETF | Asset Management | 🔴 Cont. Bear | −11.9% | −14.0% |
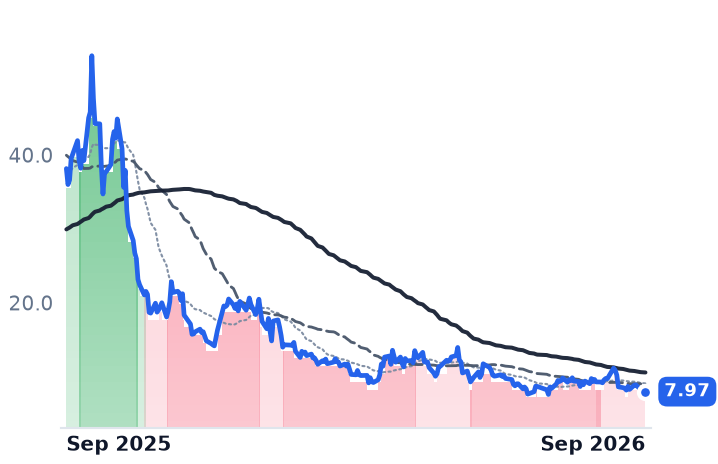
UUUU | Energy Fuels | Uranium | 🔴 Cont. Bear | −24.8% | −33.3% |
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −13.7% | −71.2% |
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −8.6% | −68.2% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | −14.0% | −79.1% |
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | −6.7% | −21.9% |
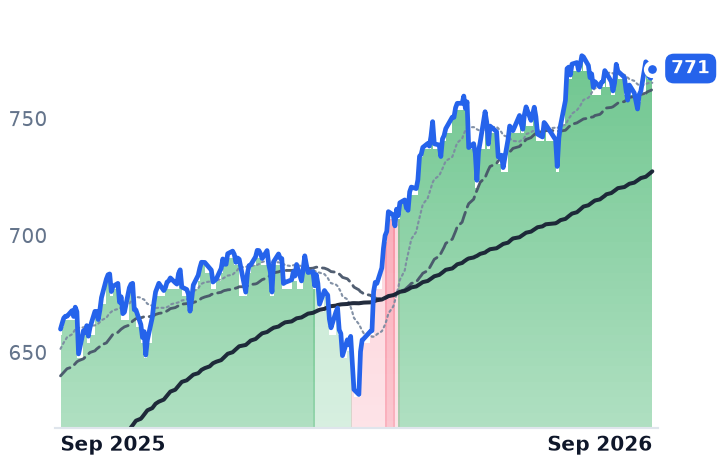
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.1% | +15.9% |
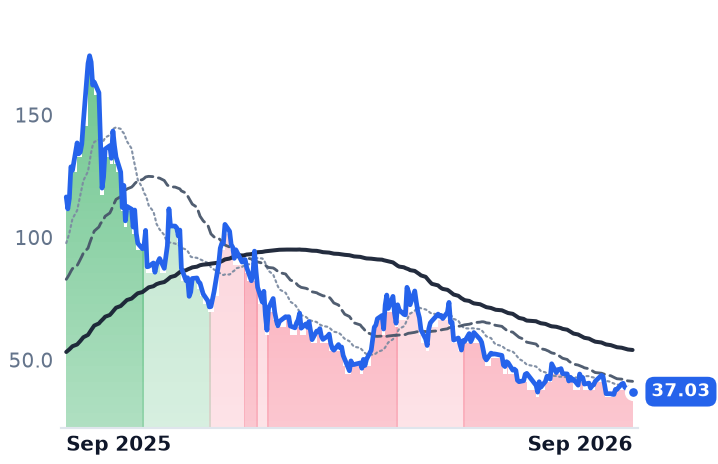
12-month price & trend
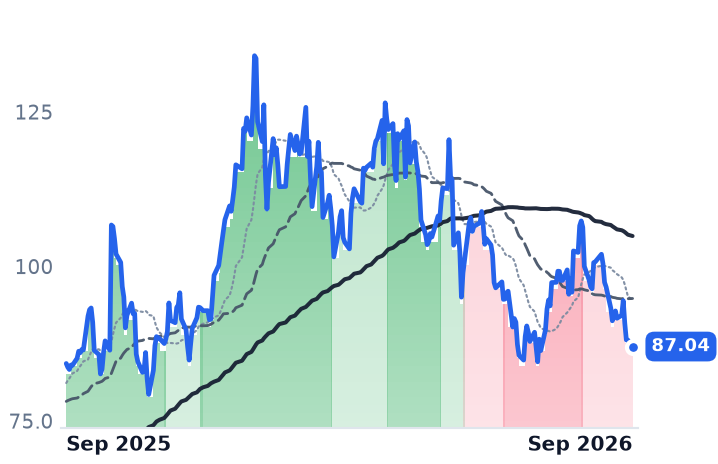
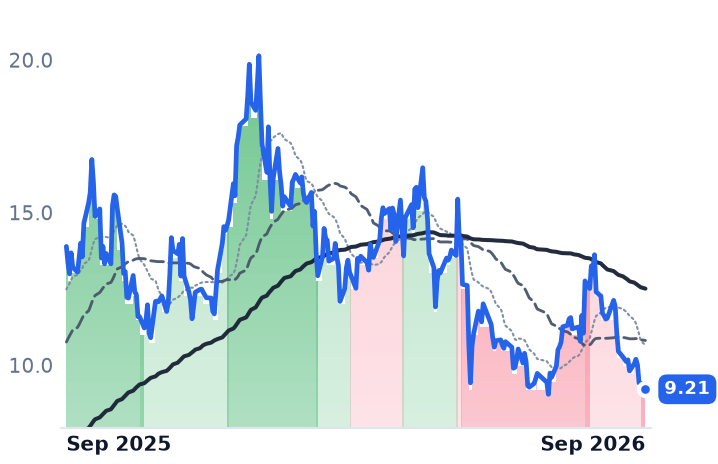
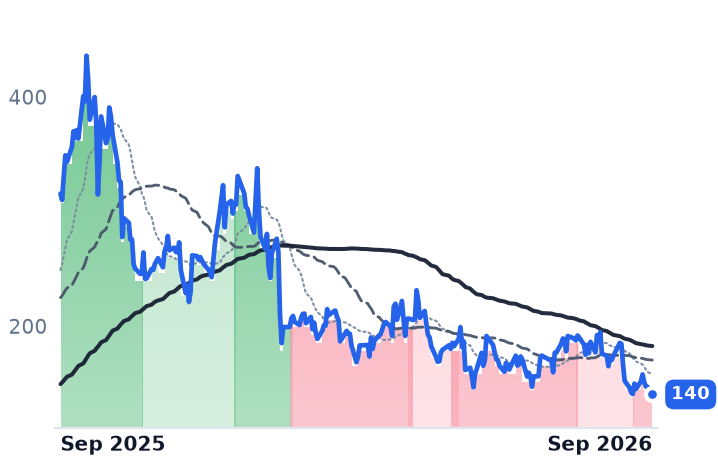
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCJ | $37.9B | 151.0x | 59.1x | 15.5x | 10.9x | 56.1x | 39.6x | 62.2x | 0.9% |
UEC | $4.6B | n/m | — | 225.6x | 44.5x | 533.1x | 105.1x | n/m | -2.6% |
LEU | $2.7B | 55.9x | 55.1x | 5.6x | 5.7x | 24.1x | 24.3x | 27.1x | -8.3% |
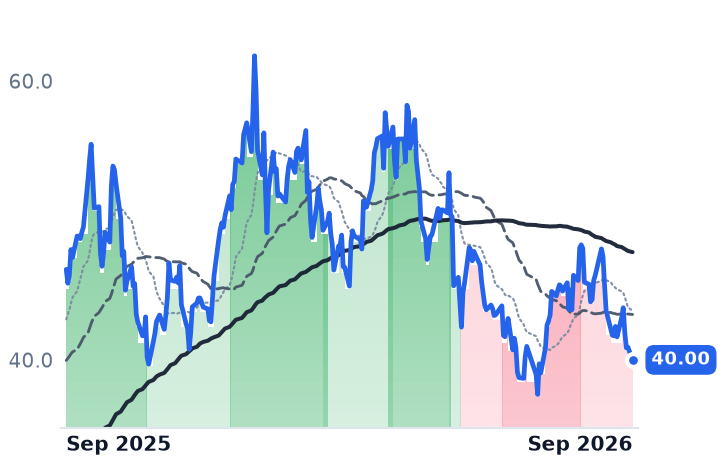
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
URA | $3.9B | — | — | — | — | — | — | — | — |
UUUU | $2.8B | n/m | — | 26.8x | 21.3x | 62.0x | 49.3x | n/m | -3.9% |
LTBR | $258.0M | n/m | — | n/m | — | — | — | n/m | -6.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKLO | $6.6B | n/m | — | — | — | — | — | n/m | -4.2% |
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
CEG | $94.5B | — | 21.8x | — | 2.8x | — | — | 13.9x | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CCJ | Revenue | +1.4% | +12.1% | +8.4% |
| EPS | +2.7% | +71.7% | +24.6% | |
UEC | Revenue | −61.4% | +301.4% | +159.3% |
| EPS | +53.3% | −65.1% | −345.7% | |
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.2% | +13.2% | −23.3% | |
UUUU | Revenue | +128.1% | +88.3% | +62.7% |
| EPS | −37.3% | −160.5% | +170.0% | |
OKLO | Revenue | — | +247.8% | +498.2% |
| EPS | +64.1% | +8.1% | +10.3% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% | |
CEG | Revenue | +37.2% | +2.5% | +5.3% |
| EPS | +28.9% | +10.4% | +26.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A record price, fewer contracts
The price utilities actually sign for uranium reached a nominal record last month while the companies selling it spent the year being marked down. Under multi-year contracts, the long-term price closed August at $96.50 a pound, above the $95 peak set in 2007; spot sat at $89.30 on 28 September, roughly where it began 2026. Cameco, the largest listed producer, raised its 2026 realized-price guidance to C$91–96 a pound from C$85–89 and held production at 19.5–21.5 million pounds. Its shares are 35% below their 28 January high.
What has been marked down is time, not tonnage. The 30-year Treasury yield broke 5.5% on 25 September, the highest since 2004, with roughly $570bn of artificial-intelligence-related corporate bond issuance crowding the long end; a higher discount rate falls hardest on cash flows dated in the 2030s. Over twelve months the nuclear names ranked themselves by distance to cash flow: NuScale Power fell 79%, Oklo 67%, Centrus Energy 54%, Uranium Energy 33% — and Cameco, the only one with a delivery book, rose 1.7%. Two dated tests now land inside 48 hours.
Cameco: the hole is Westinghouse
Cameco's June quarter read like a collapse — net income down 92% to $25.2m — and none of it came from mining. Its 49% share of Westinghouse, the reactor-services business and AP1000 vendor it co-owns with Brookfield, swung to a $10m loss from $126m a year earlier, when the Dukovany two-reactor project in the Czech Republic contributed about US$170m. "Our year-to-date financial and operational performance reflects the value of aligning our marketing, operational and financial decisions with strengthening industry fundamentals," chief executive Tim Gitzel said on 31 July. The quarter's realized price of C$93.13 a pound — about US$68 converted — sits well under spot because the book was struck years ago with floors in the high $70s and ceilings near $160, and it lags in both directions.
The de-rating is real in dollars and illusory in multiples. Market capitalization has fallen from $50.3bn in May to $37.9bn, yet trailing price-to-gross-profit rose from 38.6x to 56.1x, because gross profit shrank faster than the price; forward earnings put the shares on 59.1x, with consensus 2026 profit essentially flat before a 72% step up in 2027. The unpriced item is Westinghouse itself, which confidentially filed a draft registration statement on 31 July.
Centrus: the customer left
Centrus, the only US-owned commercial enricher and supplier of separative work units to utilities in the US, Japan and Belgium, is where the business genuinely deteriorated. Separative-work volumes fell 23% year over year while enrichment pricing rose 3%; gross margin narrowed to 28.3% from 34.9% and operating income dropped 69%. Then the Department of Energy amended the high-assay low-enriched uranium contract on 30 June into a three-month, $15.0m option for cascade maintenance and storage with no production, expiring 30 September, requested no fiscal-2027 operating funds, and said it does not currently intend to exercise further options.
Five weeks after chief executive Amir Vexler called it "another strong quarter of financial and operational progress" on 5 August, Centrus priced $500m of shares and warrants at about $199.64. The stock closed at $140.37, leaving every warrant strike out of the money. A $4.5bn backlog running to 2040 sits behind a trailing price-to-earnings of 55.9x against 55.1x forward: no growth priced, consistent with consensus 2026 earnings 43% below last year's.
Uranium Energy: no revenue, by choice
Uranium Energy, the in-situ recovery producer that restarted Burke Hollow in South Texas in April, booked zero revenue in the quarter ended 30 April and a $52.3m loss. Fully unhedged, it withheld 1,456,000 pounds carried at $127m rather than clear into spot; its last sale moved 200,000 pounds at $101. With no earnings anchor, the usable readings are price-to-book of 3.18x and price-to-sales down from 373x in May to 226x. Full fiscal-2026 results come on 29 September.
What was actually taken back
Three different payment meters, three different verdicts. Cameco's earnings damage is a reactor-construction accounting swing and its cheapness is arithmetic, not value. Centrus's fall was written in Washington and confirmed by a dilutive raise — so the idea that an enrichment premium held while mined pounds fell is simply wrong, since Centrus is the second-worst performer of the three. Uranium Energy's decline has no fuel-market cause at all; the likelier reading is a discount rate that punishes waiting, and a market unwilling to fund a producer that will not sell. Constellation Energy, which mines nothing and enriches nothing, fell 12.9% over the same September sessions in which Cameco fell 13.6% and the S&P 500 fell 0.7%.
One number belongs to the fuel market rather than the bond market: reported term contracting through 31 August exceeded 38 million pounds, about 15% below last year, at the highest long-term price ever printed. Utilities will pay the record. They still will not be the first to sign.