

Appian, BlackLine and Procore Bill Three Different Ways; September Priced Them as One
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
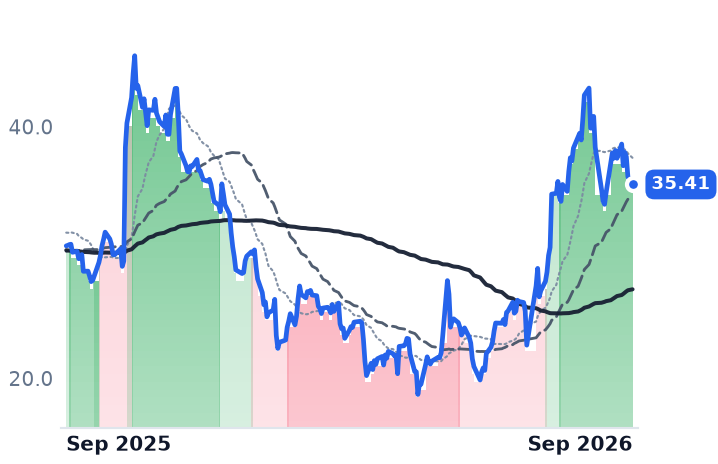
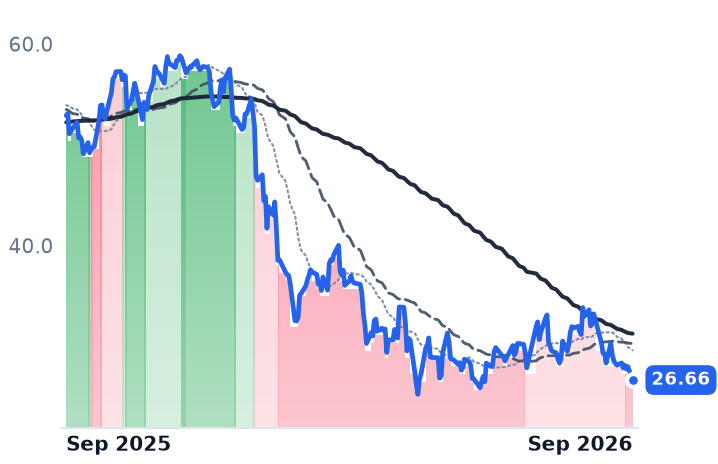
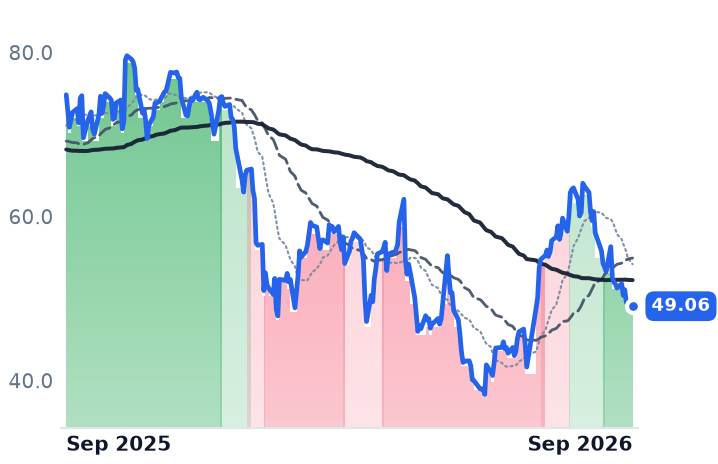
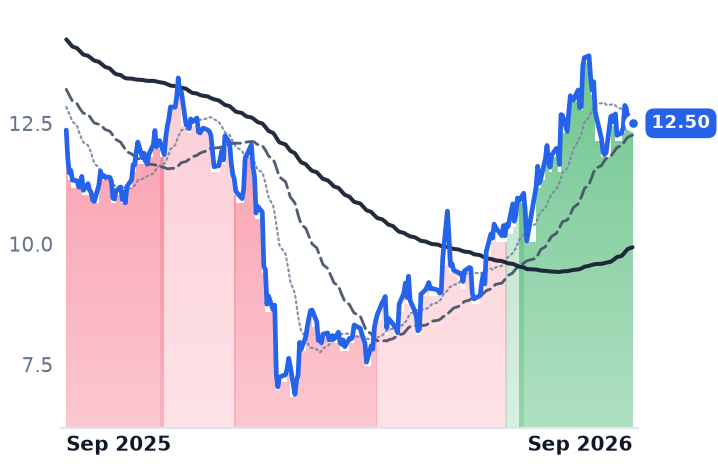
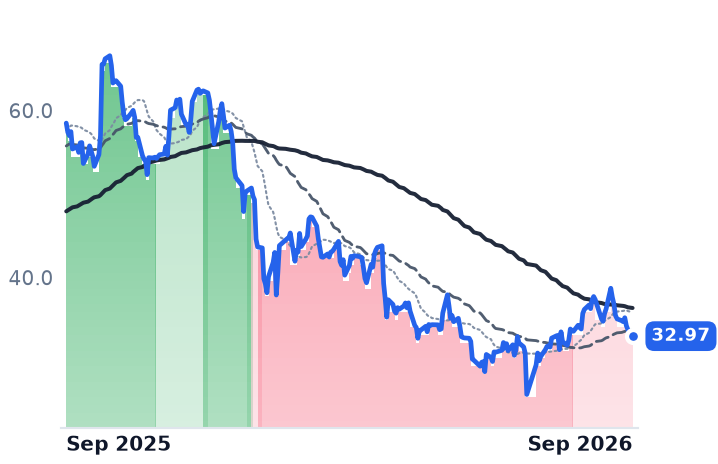
Three vertical software makers are paid by three incompatible meters — a cloud subscription, an uncapped platform contract and a fee indexed to the dollar value of construction a customer puts under management — and in the thirty days to 28 September they fell within six percentage points of each other. Over the prior three months they had diverged violently.
The reported accounts do not line up with the moves. BlackLine's revenue growth accelerated to 9.2% and operating income rose 45.7%, yet its annual recurring revenue grew only 6% and net revenue retention was 102.4% — the leading meter, not the profit-and-loss statement, is what the de-rating tracks. Appian's growth decelerated to 19.1% while its price-to-gross-profit multiple expanded from 3.07x in early May to 4.46x. Procore's growth has sat between 15.6% and 15.8% for four straight quarters.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
APPN | Appian | Low-Code & Process Automation | 🌱 Emerging Bull | −17.8% | +16.0% |
BL | BlackLine | Financial Services Software | 🔴 Cont. Bear | −20.7% | −49.6% |
PCOR | Procore Technologies | Specialized Enterprise Solutions | 🌱 Emerging Bull | −22.0% | −34.4% |
| Compared against · context, not the story | |||||
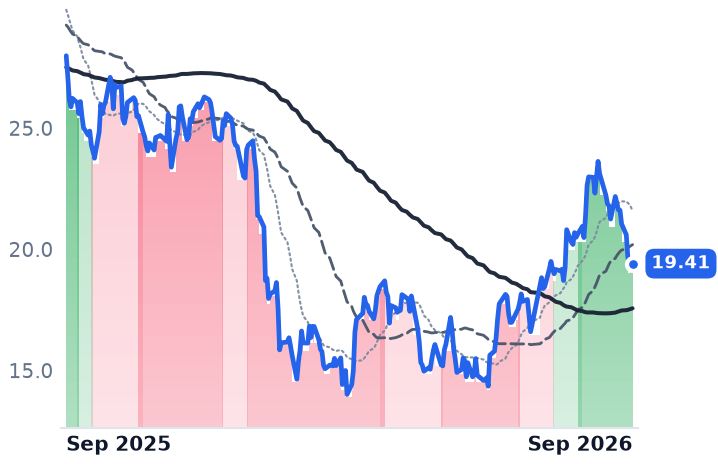
NCNO | nCino | Financial Services Software | 🌱 Emerging Bull | −15.5% | −30.7% |
FRSH | Freshworks | Security & Compliance | 🌱 Emerging Bull | −10.1% | +1.1% |
PEGA | Pegasystems | Low-Code & Process Automation | 🔴 Cont. Bear | −10.1% | −43.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APPN | $2.6B | n/m | 32.4x | 3.3x | 3.0x | 4.5x | 4.2x | 112.4x | 3.0% |
BL | $1.6B | 45.1x | 10.7x | 2.1x | 2.0x | 2.8x | 2.7x | 20.0x | 10.9% |
PCOR | $7.4B | n/m | 29.2x | 5.2x | 4.9x | 6.5x | 6.1x | 115.3x | 4.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NCNO | $2.1B | 62.0x | 14.7x | 3.4x | 3.3x | 5.5x | 5.3x | 28.6x | 6.3% |
FRSH | $3.4B | 18.7x | 18.3x | 3.7x | 3.5x | 4.4x | 4.1x | 37.6x | 7.4% |
PEGA | $6.1B | 19.7x | 15.2x | 3.5x | 3.3x | 4.7x | 4.3x | 30.6x | 8.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APPN | Revenue | +19.1% | +10.8% | +7.4% |
| EPS | +104.0% | +31.1% | +11.4% | |
BL | Revenue | +9.5% | +10.5% | +10.2% |
| EPS | +19.5% | +11.9% | +17.2% | |
PCOR | Revenue | +15.3% | +13.9% | +14.4% |
| EPS | +24.1% | +46.2% | +20.2% | |
NCNO | Revenue | +9.8% | +9.0% | +8.5% |
| EPS | +25.2% | +44.5% | +20.0% | |
FRSH | Revenue | +15.6% | +14.2% | +15.4% |
| EPS | +5.4% | +24.0% | +18.4% | |
PEGA | Revenue | +8.8% | +9.2% | +8.7% |
| EPS | +18.0% | +7.8% | +6.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
DA Davidson cut BlackLine to Underperform on 28 September, lowering its price target to $23 from $30 and citing competition from emerging AI labs as a threat to the growth trajectory of the accounting-close software maker. The shares closed down 4.8%. It was the first company-specific news to reach any of three vertical software makers in weeks — and it arrived after all three had already fallen between 17% and 23% over the preceding month.
That uniformity is the finding. Appian, which sells a low-code platform for building workflows and applications to banks, insurers, drugmakers and government agencies; BlackLine, which automates the corporate accounting close; and Procore, whose platform runs construction projects for owners and contractors, are paid in three ways that share nothing. Yet September moved them as a single instrument. Over the three months from late June they had done the opposite — Appian up 61.2%, Procore up 17.1%, BlackLine down 5.9%.
Three meters, three answers
Appian is paid on cloud subscriptions and services. Second-quarter cloud subscription revenue reached $131.7m, up 23%, with total revenue of $203.3m up 19.1% and adjusted earnings before interest, taxes, depreciation and amortization doubling to $16.2m. Four verticals — financial services, insurance, life sciences and the public sector — supply 80% of annual recurring revenue, chief financial officer Serge Tanjga told a William Blair conference, and more than 70% of the business comes from customers spending over $1m a year.
BlackLine no longer sells seats. More than 90% of new customers now sign uncapped platform contracts with no limit on logins, a shift chief executive Owen Ryan told investors on the 4 August call deliberately reduces the near-term contribution seat additions used to make. Procore never sold seats at all: it charges an annual fee per product set by a customer's Annual Construction Volume — the aggregate dollar value of work across that customer's projects — with unlimited users included.
Where the businesses and the prices disagree
BlackLine's reported accounts improved. Revenue growth accelerated from 7.2% for full-year 2025 to 9.2% in the June quarter, operating income rose 45.7% to $11.0m on a 76.0% gross margin, and the company held full-year guidance at $765m-$769m. The leading meter tells the other story: annual recurring revenue of $719m grew 6% against a stated 13-16% ambition, dollar-based net revenue retention was 102.4%, and the mid-market customer count is still falling. Ryan said artificial-intelligence reviews have made large enterprise deals harder to predict, with finance, security and governance teams now assessing them together. The de-rating tracks the recurring-revenue line, not the profit-and-loss statement.
Appian runs the reverse. Growth decelerated across three quarters — 21.7%, then 21.5%, then 19.1% — gross margin compressed to 71.2% from 75.8% a year earlier, and the raised full-year revenue guide of $845m-$853m implies about 17%, below the pace just posted. Against that, its price-to-gross-profit ratio expanded from 3.07x in early May to 4.46x. The business did earn something real: a first full-year operating profit in 2025, of $0.6m on $726.9m of revenue, against a $60.9m loss the year before. "[Pulling 2027 hiring forward] might be an indication of strong pipeline that's unusually strong and also our confidence of being able to win in the current environment," chief executive Matt Calkins said on the 6 August call. Consensus does not agree: forecasts have revenue growth falling to 10.8% in 2027.
Procore's growth has been the steadiest of the three, inside a band from 15.6% to 15.8% for four straight quarters, and the June quarter produced its first positive operating margin at 1.2%. Its problem sits outside software budgets. Private nonresidential construction spending fell 4.7% year on year in June and 7.9% excluding data centers; the Architecture Billings Index read 47.2 in August, below the line separating growth from contraction. On 9 September Procore closed its largest acquisition, paying about $845m in cash for DroneDeploy, a reality-capture and robotics platform — roughly 11% of its market value, spent as its index contracts. Gross margins differ too widely for revenue multiples to compare here; measured against gross profit Procore is the dearest of the three at 6.52x, down from 7.96x in early May, while BlackLine sits at 2.82x from 3.58x.
The verdict
What the businesses earn and what the market did are separable. BlackLine's fall is earned — by 6% recurring-revenue growth, not by its accounts. Procore's is earned by the construction index its contracts are written on, not by churn. Appian's summer advance is the one nothing in the revenue line explains: growth slowed at every reading while the multiple did the work. And the September leg belongs to none of them. It came with a broader software de-rating in which roughly $2 trillion of enterprise software value has gone since early 2026, alongside the higher long yields the market has been living with since the 10 September 30-year auction. The likelier reading is rotation out of long-duration software, which does not read billing models.
The largest number attached to any of the three appears in none of their revenue lines. Appian's vacated $2.036bn trade-secrets award against Pegasystems returns to a Fairfax County jury on 11 January, and Pegasystems carries no accrual for it.