

Centrus's Cost per Enrichment Unit Rose 13% as Cameco Lifted Its Price Guide to $91–96
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A year that halved Centrus and took a fifth off BWX Technologies never touched the commodity underneath: uranium spot sits near $90 a pound and the long-term contract price at a nominal record in the mid-$90s. And Cameco, the miner at the center of the complex, is up slightly over twelve months — its decline is a month old, not four quarters.
What broke is specific and separable. Centrus's June-quarter gross margin fell to 28.3% from 34.9%, the Energy Department cut its cascade contract to $15.0m of caretaking with no production, and a $500m share-and-warrant sale followed in September. Cameco raised realized-price guidance and reaffirmed 19.5–21.5 million pounds of output; its earnings shortfall was Westinghouse. BWXT raised all four 2026 guidance lines on 3 August with backlog up 40%, and nothing in its own accounts explains a forward multiple a third below May's.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
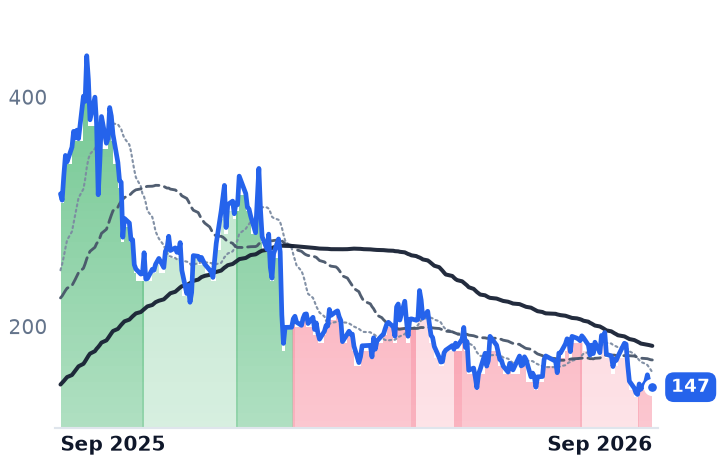
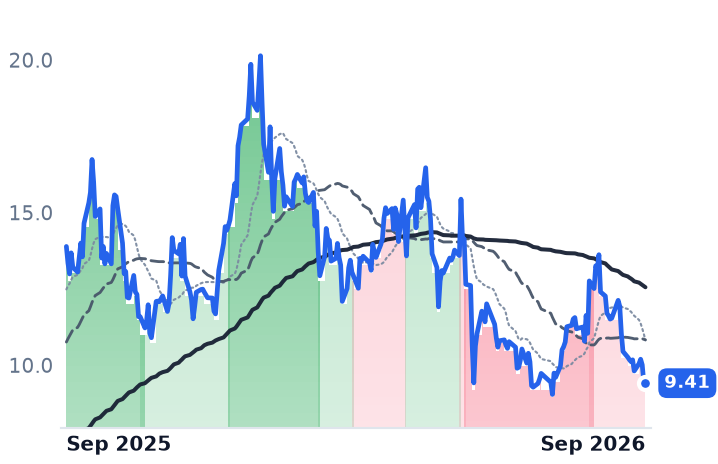
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −16.3% | −53.4% |
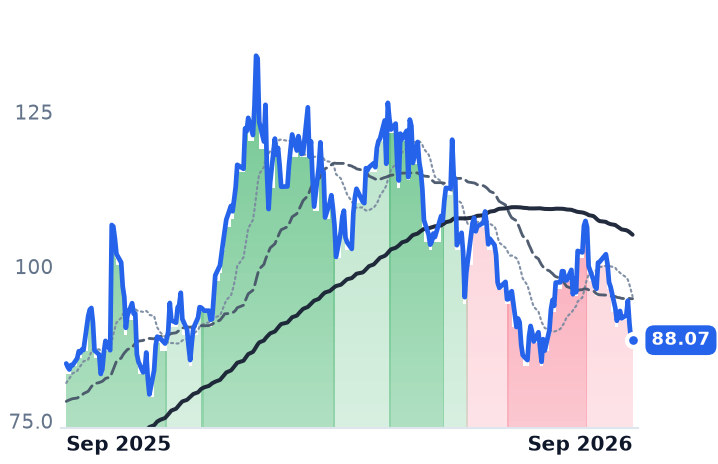
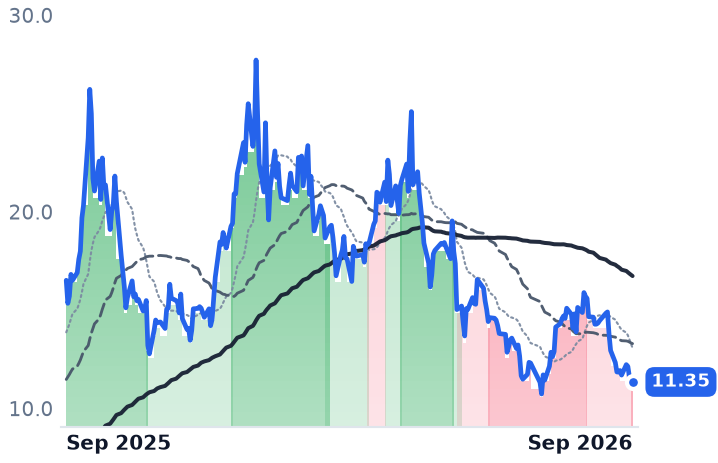
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −11.9% | +4.5% |
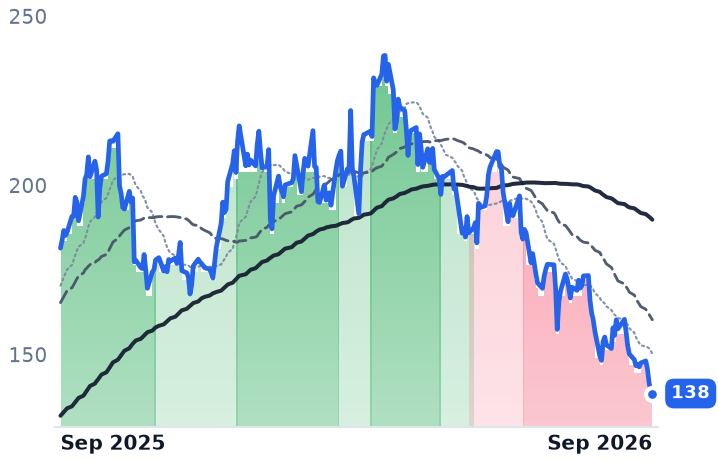
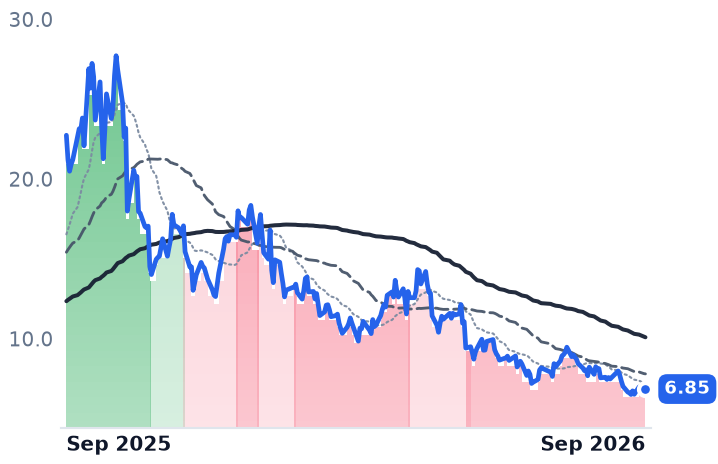
BWXT | BWX Technologies | Naval & Shipbuilding | 🔴 Cont. Bear | −9.4% | −23.7% |
| Compared against · context, not the story | |||||
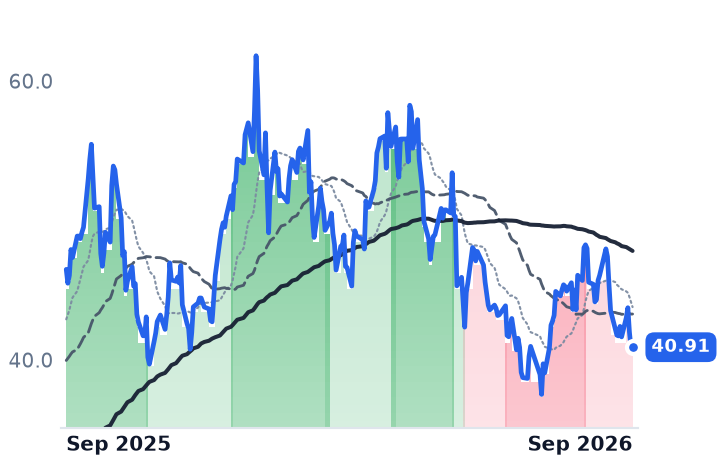
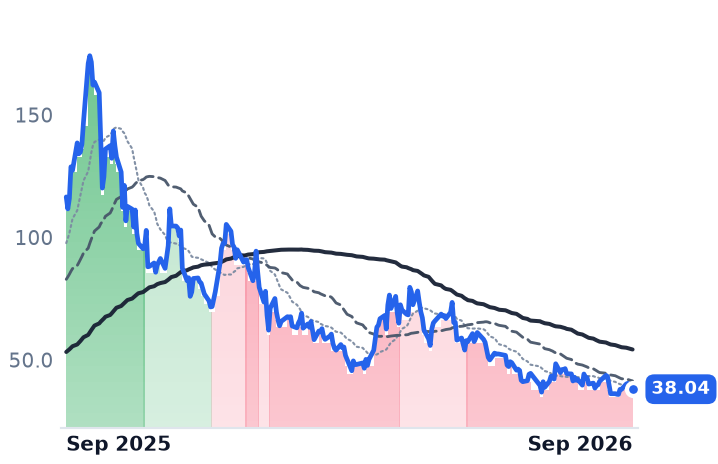
URA | Global X - Uranium ETF | Asset Management | 🔴 Cont. Bear | −10.2% | −12.0% |
UEC | Uranium Energy | Uranium | 🔴 Cont. Bear | −24.1% | −32.3% |
UUUU | Energy Fuels | Uranium | 🔴 Cont. Bear | −22.6% | −31.3% |
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −9.3% | −69.9% |
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −5.2% | −67.4% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | −9.4% | −77.9% |
NNE | Nano Nuclear Energy | Power & Propulsion Systems | 🔴 Cont. Bear | −5.5% | −56.6% |
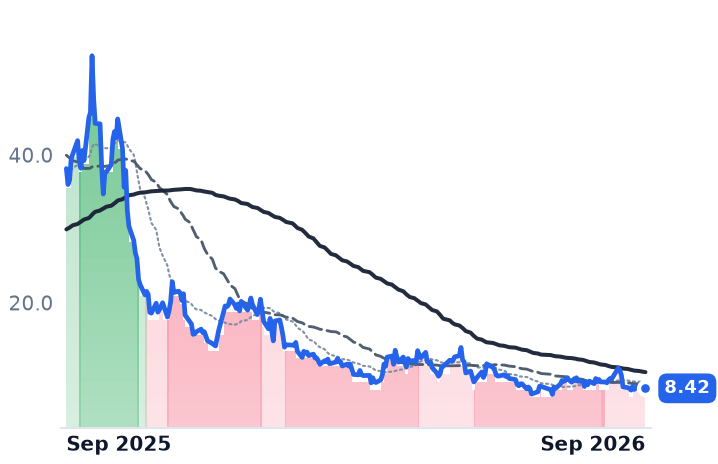
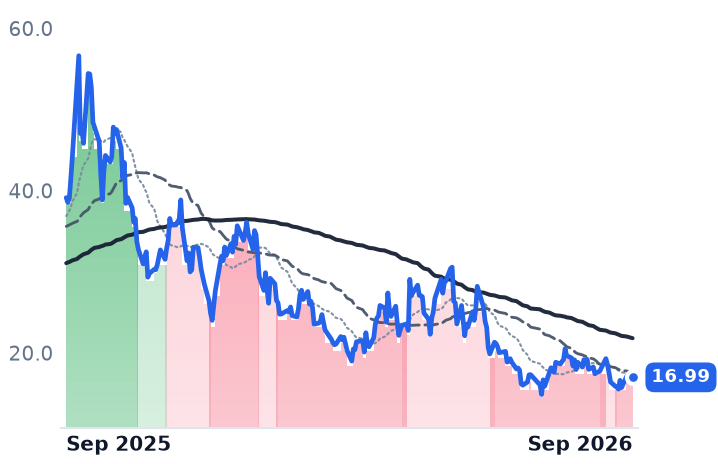
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $2.8B | 58.6x | 57.8x | 5.9x | 5.9x | 25.3x | 25.4x | 28.8x | -8.0% |
CCJ | $38.4B | 152.3x | 60.1x | 15.6x | 11.1x | 56.6x | 40.2x | 62.8x | 0.9% |
BWXT | $12.7B | 35.7x | 29.2x | 3.6x | 3.3x | 16.4x | 15.1x | 25.5x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
URA | $3.9B | — | — | — | — | — | — | — | — |
UEC | $5.1B | n/m | — | 253.1x | 49.9x | 598.0x | 117.9x | n/m | -2.4% |
UUUU | $2.8B | n/m | — | 26.8x | 21.3x | 62.0x | 49.3x | n/m | -3.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LTBR | $258.0M | n/m | — | n/m | — | — | — | n/m | -6.6% |
OKLO | $6.6B | n/m | — | — | — | — | — | n/m | -4.2% |
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NNE | $1.1B | n/m | — | — | 887.7x | — | — | n/m | -3.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.2% | +13.2% | −23.3% | |
CCJ | Revenue | +0.9% | +12.1% | +8.4% |
| EPS | +2.2% | +71.7% | +24.6% | |
BWXT | Revenue | +20.6% | +9.8% | +7.3% |
| EPS | +24.1% | +11.2% | +11.8% | |
UEC | Revenue | −61.4% | +301.4% | +159.3% |
| EPS | +50.7% | −74.9% | −447.4% | |
UUUU | Revenue | +128.1% | +88.3% | +62.7% |
| EPS | −37.3% | −160.5% | +170.0% | |
OKLO | Revenue | — | +247.8% | +498.2% |
| EPS | +64.1% | +8.1% | +10.3% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% | |
NNE | Revenue | +1684.0% | +356.5% | +39.0% |
| EPS | −23.4% | +55.2% | +34.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
On Wednesday the contract that pays for the only high-assay low-enriched uranium cascade in the United States runs out. The Department of Energy amended it on 30 June to run only through 30 September, exercising a three-month option worth a fixed $15.0m for cascade maintenance and storage of already-produced material — with no enrichment at all — and its proposed fiscal 2027 budget contains no funding to operate the Piketon cascade, with the department having told Centrus Energy it does not currently intend to exercise further options.
That is the hardest single fact behind a year in which enrichers and miners fell while the commodity they exist to supply made highs. Uranium spot sat near $90 a pound in mid-September, up roughly a fifth year on year, with the long-term contract price at a nominal record in the mid-$90s. The two can move apart because nobody in this business is paid for "demand." Centrus is paid per separative work unit out of an order book priced in earlier years; Cameco is paid for pounds it committed years ago; BWX Technologies is mostly paid cost-plus by the US Navy. Three meters, and they do not agree.
Centrus: volume down, unit cost up
Centrus Energy, the Bethesda enricher that sells separative work units and natural uranium to utilities and runs the American Centrifuge program, grew June-quarter revenue 14% to $176.1m and lost most of the profit anyway. Gross margin fell to 28.3% from 34.9% a year earlier and operating income dropped 69% to $10.4m. The mechanism is on its own face: total costs for units sold fell 23% on lower volumes while the average cost per unit sold rose 13%. Annual gross margin has now compressed four years running, from 40.1% in 2022 to 26.2% in 2025.
The forward book is not the problem. Backlog grew to $4.5bn extending to 2040, including roughly $3.0bn of contingent commitments tied to a Piketon build, and DOE signed a roughly $1bn fixed-price commercial award on 30 June requiring one metric ton of HALEU by March 2032 and an initial 12 tons of annual capacity. "This was another strong quarter of financial and operational progress for Centrus," chief executive Amir Vexler said on 5 August. Paying for it is the issue: guided capital spending of $350m–$500m against a $2.79bn market value, negative free cash flow, and a $500m offering priced 10 September creating up to about 9.5m potential new shares against roughly 22m diluted — after which the stock fell 17.5% in two sessions. At 58.6x trailing and 57.8x forward earnings on consensus 2026 earnings per share set to fall 43%, the multiple has barely moved from the 53x recorded in May; falling earnings did the work the price fall would otherwise have done.
Cameco: pounds already sold
Cameco, the Saskatoon miner that also owns 49% of Westinghouse, is up 2.8% over twelve months. Its slide dates from late August. On the uranium leg it raised 2026 realized-price guidance to $91–$96 a pound from $85–$89 and reaffirmed 19.5–21.5 million pounds of production, against commitments averaging about 28 million pounds a year through 2030. "Those old contracts are showing that upward leverage to the market that we said they would," chief executive Tim Gitzel told analysts on the second-quarter call.
The 92% fall in second-quarter net income came from the reactor side: its share of Westinghouse adjusted earnings before interest, tax, depreciation and amortization dropped to US$163m from US$352m, against a year-earlier quarter carrying the Dukovany construction project, and Cameco scrapped its five-year Westinghouse outlook in favor of current-year guidance only. Price to gross profit has risen to 56.6x from about 38x in May because gross profit fell faster than the shares. The live counter-anchor is a listing: Westinghouse is reported to be seeking above $50bn and could file as soon as October, which would mark Cameco's stake above $24.5bn against its own $38.4bn.
BWXT: the one nothing happened to
BWX Technologies, sole supplier of naval reactors and fuel to the US Navy's propulsion program and a maker of steam generators and medical isotopes, raised all four 2026 guidance lines on 3 August — adjusted earnings per share to $4.70–$4.80 — with backlog at $8.4bn, up 40%. Revenue grew 18% in the June quarter. Its one blemish is mix: operating income has fallen year on year for four straight quarters and operating margin slipped to 10.0% from 13.4% as cost-reimbursable work grew. "The industry is in the early stages of a multi-decade super cycle of growth," chief executive Rex Geveden said on the same call. The shares are down 21% over twelve months and 32% from March, and the forward multiple is 29.2x against roughly 46–47x in May, on consensus earnings growth of 24%.
What the decline earns
Centrus earns its de-rating: unit costs rising into falling volumes, the government leg reduced to caretaking, and dilution priced at a discount are contract economics and financing, not a demand failure. Cameco's is mostly arithmetic on a comparable quarter plus the removal of a five-year forecast, with its mined product selling for more. BWXT's is unexplained by anything it has disclosed. All three fell together between 8 and 25 September, alongside the Global X Uranium ETF's 14.7% loss, in a window when the 10-year Treasury yield crossed 5% for the first time since 2023 and investors repriced AI capital intensity — which is why the smaller reactor developers, NuScale down 78% and Oklo down 68% over the year, led and the fuel names followed.
The useful conclusion is that "nuclear fuel" is not one exposure. Kazatomprom is holding output below even its own reduced ceiling and says no spot price would make it accelerate, which keeps the pound scarce and Cameco's escalators working regardless of what a cascade in Ohio does. On Wednesday that cascade stops being paid to run at all, and the commercial contract meant to replace the government one does not owe a delivery until 2032.