

Florida Fixed NextEra's Return at 10.95% Until 2029, and Its Funding Cost Kept Rising
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The three biggest utility builders serving American data centers all fell together this week while the S&P 500 barely moved, and none of them reported anything to explain it. The cause sits in the bond market: the 10-year Treasury yield reached a 19-year high over three sessions to September 25, and utilities were the worst-hit sector of the day.
The businesses do not agree with the selling. NextEra's June quarter grew revenue 12.4% and operating income 17.1%, and it is aiming at the top of its 2026 earnings range — yet the market now pays 7.93 times gross profit for it, against 11.73 in May. Entergy is the one with a genuine problem, and the problem is dilution: per-share earnings slipped to $1.03 on a 4.6% higher share count. Dominion no longer prices itself at all — it is a fixed-ratio stub on NextEra's bid.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
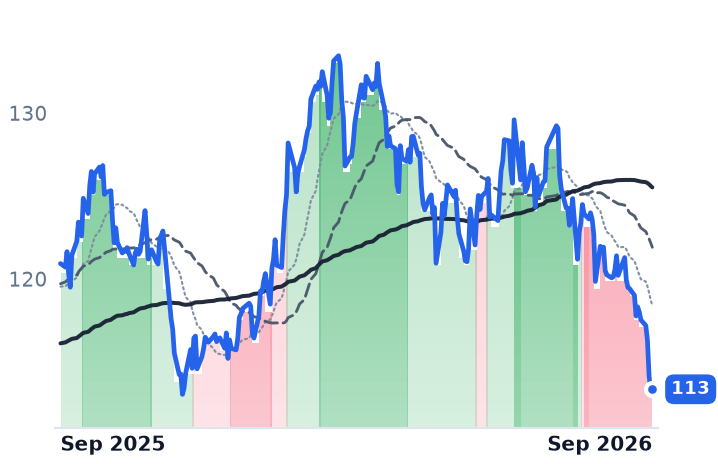
NEE | NextEra Energy | Vertically Integrated Utilities | 🔴 Cont. Bear | −8.9% | +1.7% |
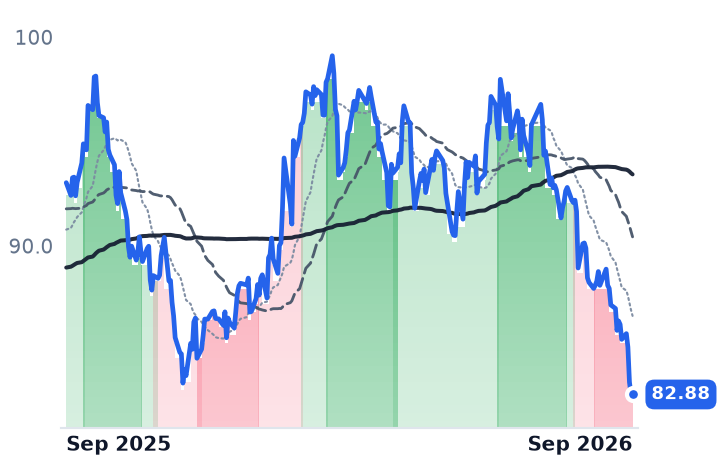
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −8.5% | +2.8% |
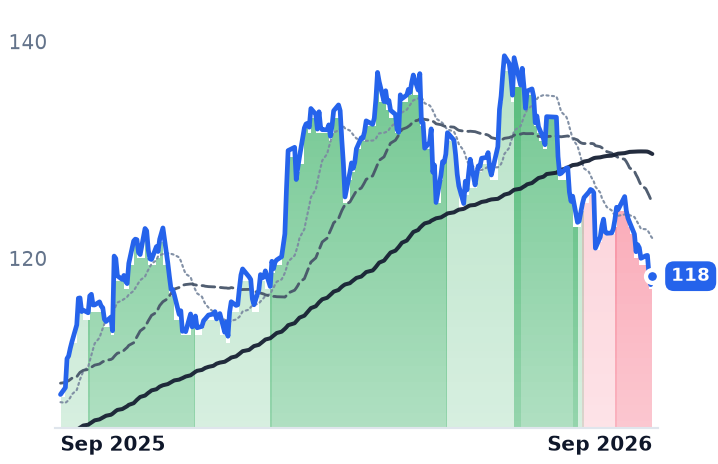
ETR | Entergy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −7.2% | +8.3% |
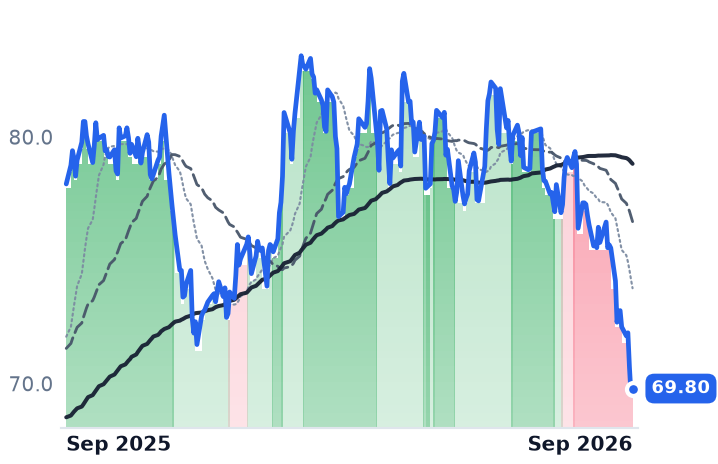
PCG | PG&E | Vertically Integrated Utilities | 🟢 Cont. Bull | −29.8% | −16.9% |
DUK | Duke Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −5.9% | −6.3% |
SO | The Southern | Vertically Integrated Utilities | ⚠️ Emerging Bear | −6.3% | −10.9% |
AEP | American Electric Power | Vertically Integrated Utilities | ⚠️ Emerging Bear | −3.3% | +10.2% |
XEL | Xcel Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −9.1% | −10.6% |
PEG | Public Service Enterprise Group Incorporated | Vertically Integrated Utilities | 🔴 Cont. Bear | −8.4% | −17.3% |
PPL | PPL | Transmission & Distribution Only | 🔴 Cont. Bear | −7.0% | −11.4% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.1% | +17.2% |
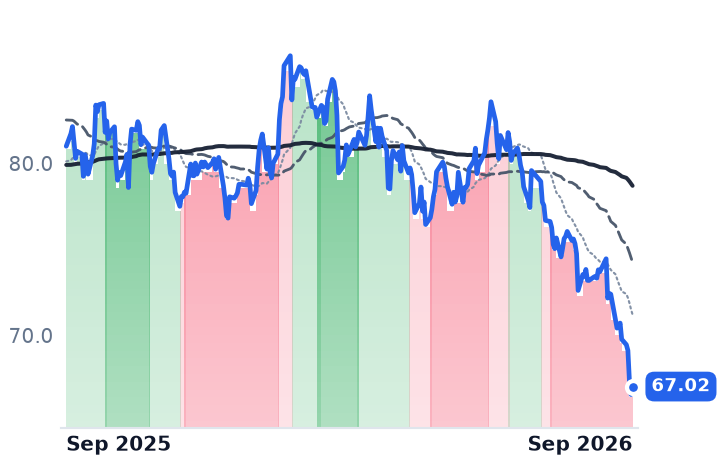
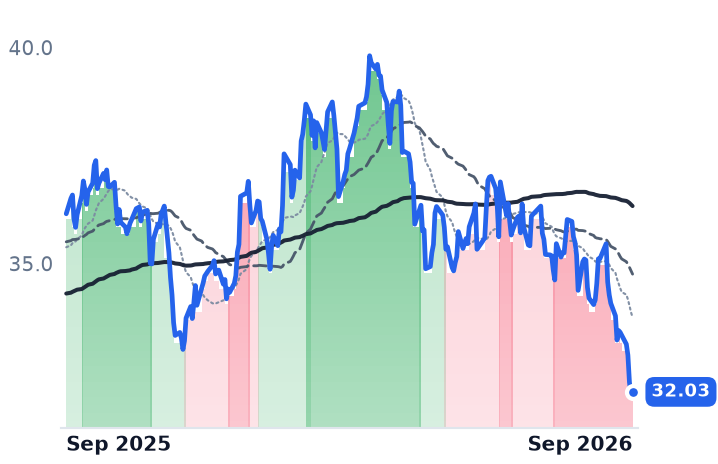
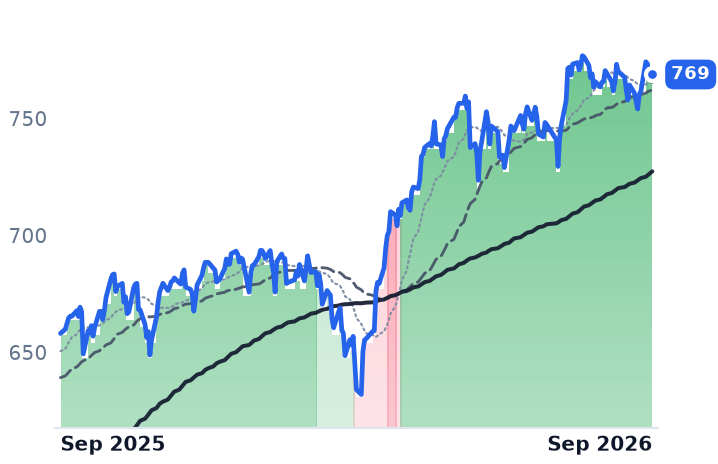
12-month price & trend
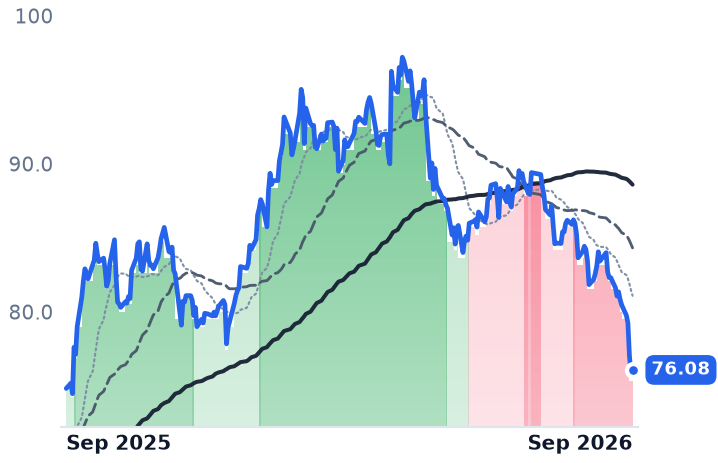
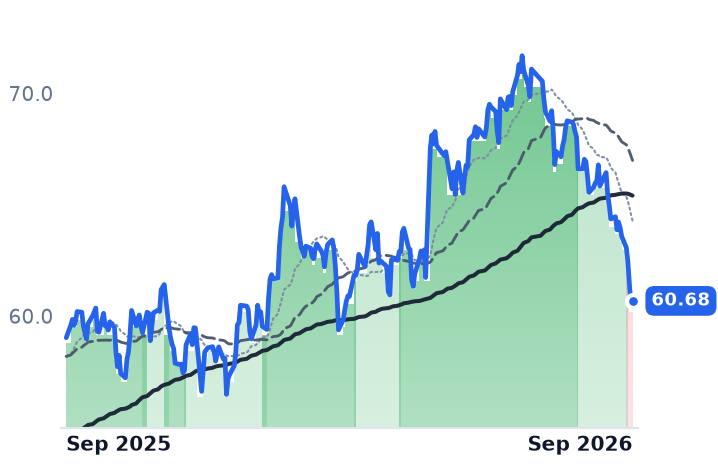
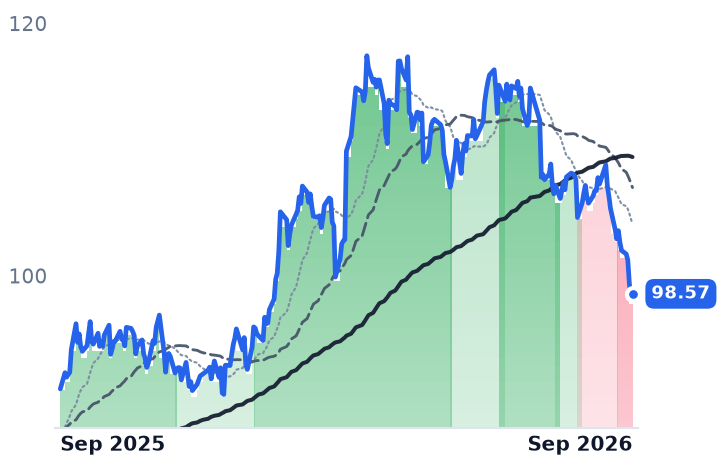
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEE | $165.4B | 17.7x | 19.7x | 5.7x | 5.3x | 7.9x | 7.4x | 15.4x | -6.2% |
D | $55.1B | 21.7x | 17.5x | 3.0x | 3.0x | 6.1x | 6.1x | 14.7x | -12.4% |
ETR | $47.3B | 25.6x | 23.0x | 3.5x | 3.4x | 9.0x | 8.7x | 14.0x | -6.7% |
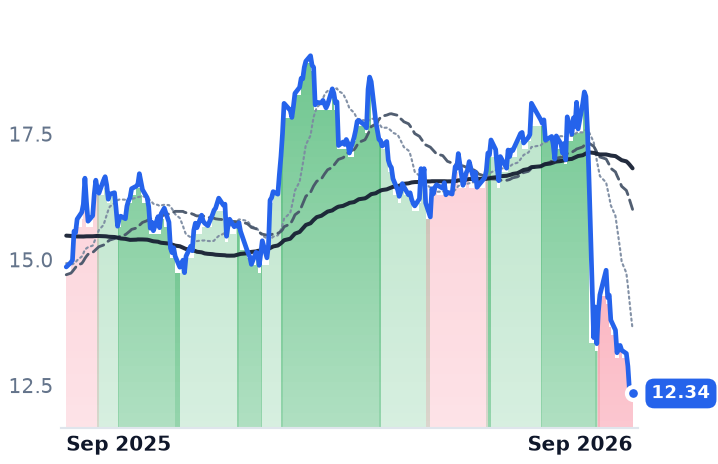
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCG | $37.7B | 10.2x | 8.5x | 1.5x | 1.4x | 2.6x | 2.6x | 9.6x | -11.3% |
DUK | $93.7B | 18.1x | 17.9x | 2.8x | 2.8x | 4.1x | 4.1x | 11.4x | 1.6% |
SO | $106.6B | 22.2x | 20.2x | 3.5x | 3.5x | 8.1x | 8.0x | 12.7x | 2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AEP | $67.8B | 21.4x | 19.5x | 3.0x | 2.9x | 6.1x | 5.9x | 14.1x | 13.2% |
XEL | $48.6B | 23.3x | 19.0x | 3.3x | 3.1x | 17.4x | 16.2x | 13.9x | -6.7% |
PEG | $37.7B | 18.7x | 17.3x | 3.0x | 3.0x | 3.5x | 3.5x | 14.2x | 5.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PPL | $25.6B | 27.1x | 17.5x | 3.6x | 2.6x | 10.5x | 7.6x | 13.7x | 1.0% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.1% | +8.5% | |
D | Revenue | +13.9% | +6.6% | +5.9% |
| EPS | +5.0% | +6.3% | +7.0% | |
ETR | Revenue | +8.6% | +9.8% | +9.8% |
| EPS | +12.3% | +16.1% | +13.6% | |
PCG | Revenue | +2.8% | +3.9% | +3.9% |
| EPS | +10.1% | +9.0% | +9.2% | |
DUK | Revenue | +5.8% | +4.6% | +4.2% |
| EPS | +6.3% | +6.9% | +7.0% | |
SO | Revenue | +7.7% | +5.5% | +6.1% |
| EPS | +6.8% | +7.5% | +9.2% | |
AEP | Revenue | +9.5% | +5.9% | +7.6% |
| EPS | +7.9% | +7.6% | +10.6% | |
XEL | Revenue | +7.8% | +8.9% | +8.1% |
| EPS | +8.0% | +10.4% | +10.1% | |
PEG | Revenue | +6.5% | +3.5% | +4.9% |
| EPS | +8.1% | +7.0% | +7.7% | |
PPL | Revenue | +10.9% | +5.8% | +5.4% |
| EPS | +7.7% | +8.7% | +8.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Florida's regulators set the profit Florida Power & Light is allowed to earn at 10.95%, on a 59.6% equity layer, and locked it there through 2029. The money that pays for the plant reprices every morning.
Over three sessions ending September 25 the 10-year Treasury yield reached about 5.20%, its highest in nearly two decades, on a hotter-than-expected September flash purchasing managers' survey and roughly two-to-one odds of an October Federal Reserve increase. Utilities and property trusts led the losses, the Utilities Select Sector SPDR fund falling 1.9% on September 24 alone. NextEra Energy shares fell 4.0% across the three days, Dominion Energy 2.8% and Entergy 2.6%, against 0.3% for the S&P 500 exchange-traded fund.
Why a yield move lands on the income statement
None of that is a demand event. All three spend more on construction than their operations generate — Dominion's trailing free cash flow is negative by 12.4% of its market value, NextEra's by 6.2% — so each dollar of the buildout arrives from the securities markets at whatever they charge and is repaid at a return a commission fixed years earlier. Duke Energy's August sale of $1.75bn of equity units priced at an all-in distribution rate of 7.75% against a 9.8% allowed return: roughly two points of spread, and narrowing. Virginia's commission set Dominion's authorized return at 9.8% against the 10.4% asked, and trimmed its 2026 base-rate increase to $565.7m from $822m sought.
The awkward case
NextEra owns Florida Power & Light's 5.7m customer accounts and the largest contracted clean-energy development book in the country. Its June quarter grew revenue 12.4% to $7.53bn and operating income 17.1% — faster than sales — on a diluted share count up 1.3%. "NextEra Energy delivered a strong second quarter, with adjusted earnings per share increasing by 9.5% year-over-year," chairman and chief executive John Ketchum said of results reported July 24; the September investor presentation aims at the high end of $3.92 to $4.02 in adjusted earnings a share. At the September 23 close the shares were about 22% below the $98.75 high set May 1. The price the market pays for each dollar of NextEra's gross profit has fallen to 7.93 from 11.73 in May.
Dominion is no longer setting its own price. Since May 18 it has been the target of an all-stock NextEra offer at a fixed 0.8138 shares, a $66.8bn combination both shareholder bases approved on September 3; at the September 25 closes the implied ratio was 0.7976, a 2.0% discount to terms. Its quarter — revenue up 19.6%, operating income down 2.4% — now feeds an arbitrage spread rather than a valuation. The live variable is Richmond: Virginia attorney general Jay Jones asked the State Corporation Commission on September 21 to restart the review clock, arguing the companies "have put a different deal on the table", which would push a January 11 decision deadline into March.
Entergy, the New Orleans utility serving about 3m customers across Arkansas, Louisiana, Mississippi and Texas, is where the "failing to earn it" case has teeth. June-quarter revenue rose 5.9% while operating income was flat, and diluted earnings slipped to $1.03 a share from $1.05 because the share count rose 4.6%. That dilution funds a $67bn five-year plan whose largest contracted block still has no approved rate behind it: Louisiana regulators decide in December on seven more gas plants for Meta's Hyperion campus. "We continue to have seven to 12 gigawatts of hyperscale data center potential in our pipeline," chair and chief executive Drew Marsh told investors on July 29. At 25.6 times trailing earnings, down from 29.9 in May, Entergy still sits well above the roughly 16.8 long-run median for vertically integrated utilities.
The verdict
The de-rating splits three ways. Entergy's is largely earned — an expensive starting point, flat operating income, real dilution. NextEra's is not explained by anything in its own results; the business accelerated through the four months its gross-profit multiple lost a third. And the sector averages that make the whole group look wrecked lean on PG&E, down 32.4% in thirty days on California wildfire-liability legislation, which has no load or allowed-return content whatever. What binds the three is the spread between the cost of the next dollar and a return already fixed by order. A demand failure would show up as cancelled contracts; this one shows up in the coupon.
Virginia's new rate class for customers above 25 megawatts, effective January 2027, obliges a data center to sign for 14 years and pay for 85% of its contracted delivery demand whether it draws the power or not. The load has been made contractual. The financing has not.