

Solid Power's Revenue Went Negative. Its BMW-Samsung Evaluation Phase Ends September 30
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A battery developer whose entire revenue line is partner milestone payments has run out of milestones, and its balance sheet is now most of what the equity is worth. Solid Power reversed previously recognized revenue on its SK On licence in the June quarter, leaving the reported line below zero; the last paid milestone under that agreement was finished in April.
Consensus now models 2026 revenue of $5.5m against $21.7m in 2025, and Phase 1 of the joint evaluation with Samsung SDI and BMW expires on September 30 with the follow-on unsigned. Against $419.3m of liquidity and no debt, a $537.7m market value ascribes roughly $118m to the solid-state technology itself.
EnerSys and Eos Energy fell over the same three months with their operating numbers improving. Their decline is financing cost; Solid Power's is contract flow.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
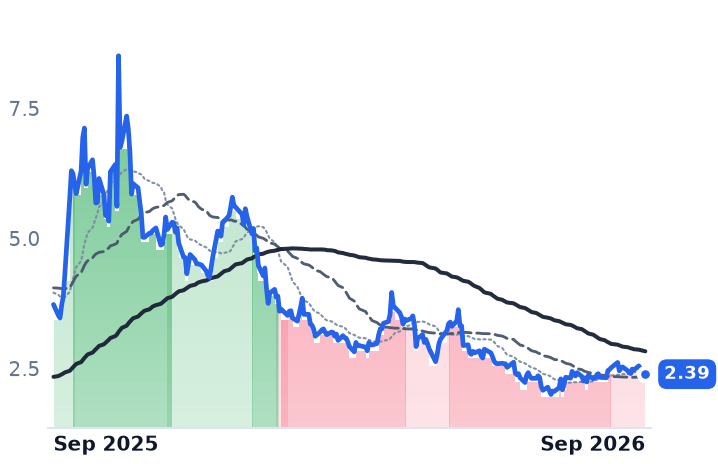
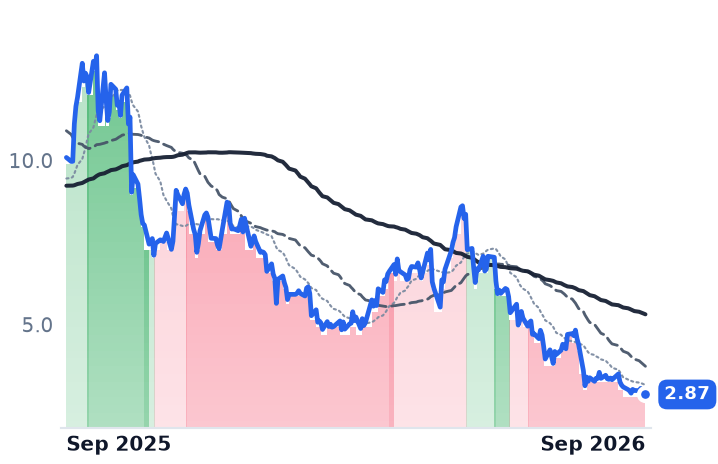
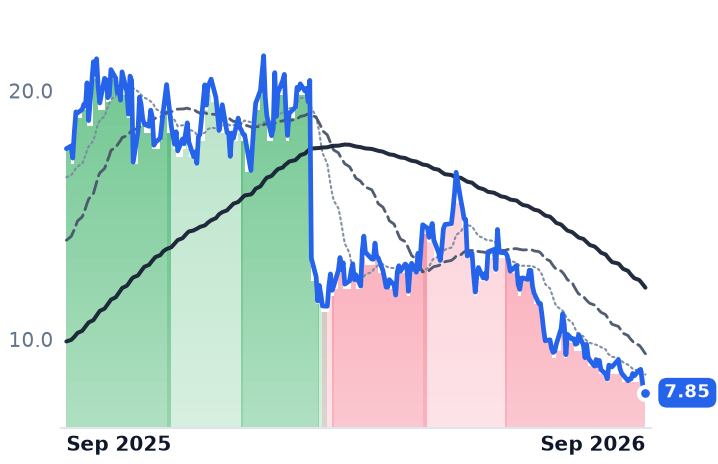
SLDP | Solid Power | Energy Storage & Batteries | 🔴 Cont. Bear | −0.4% | −35.9% |
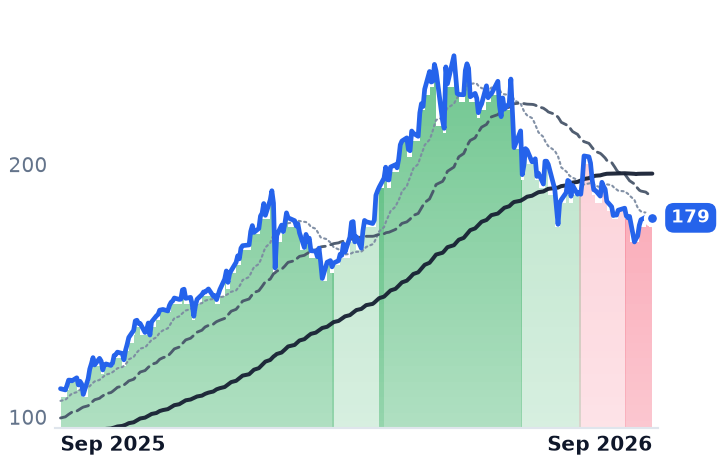
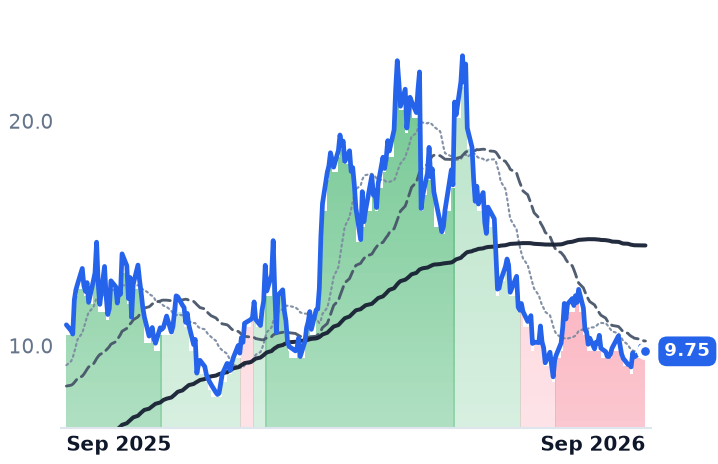
ENS | EnerSys | Energy Storage & Batteries | ⚠️ Emerging Bear | −5.9% | +60.8% |
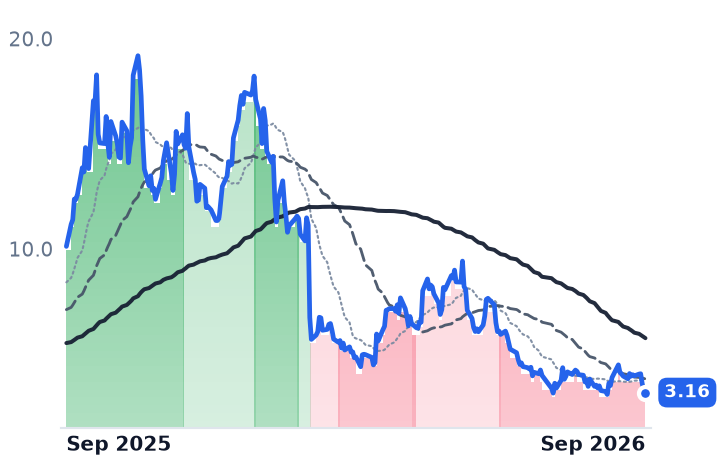
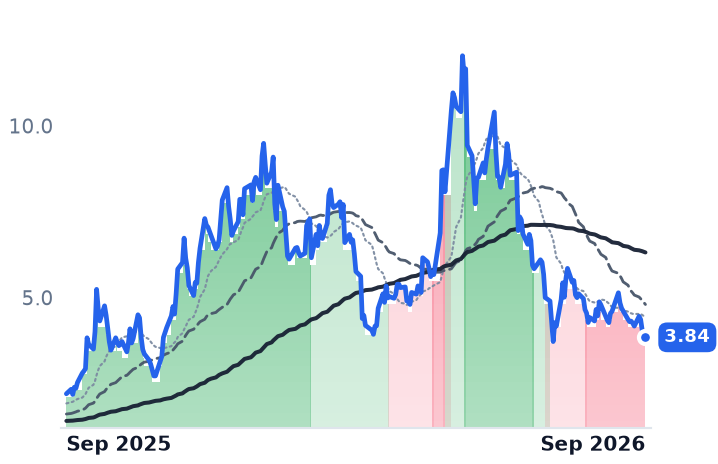
EOSE | Eos Energy Enterprises | Energy Storage & Batteries | 🔴 Cont. Bear | −9.2% | −68.7% |
| Compared against · context, not the story | |||||
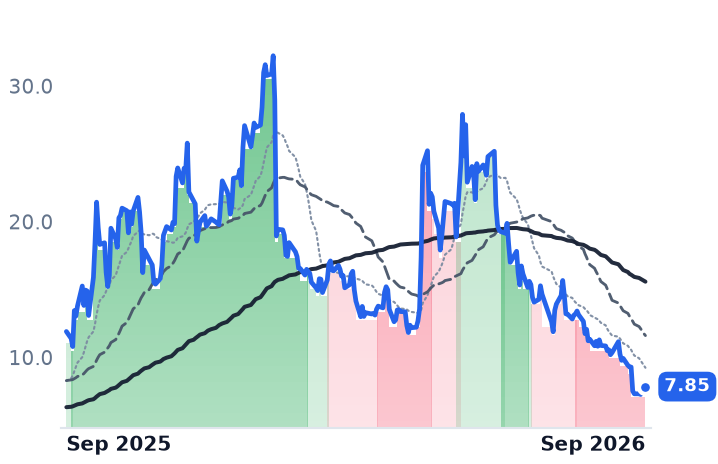
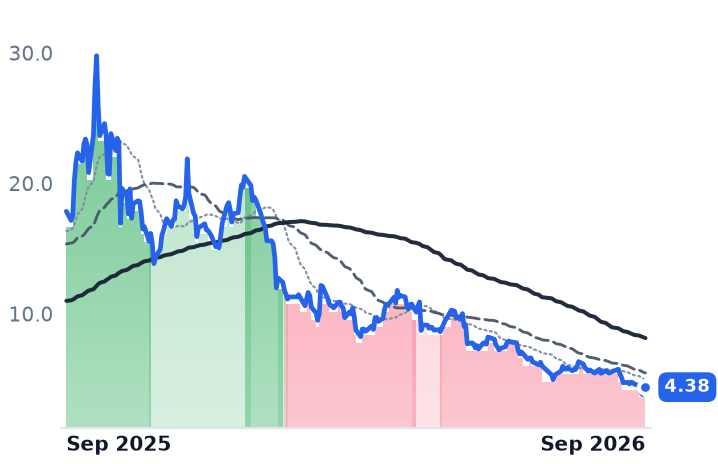
FLNC | Fluence Energy | Energy Storage Systems | ⚠️ Emerging Bear | −30.5% | −34.1% |
ENVX | Enovix | Energy Storage & Batteries | 🔴 Cont. Bear | −19.0% | −71.6% |
AMPX | Amprius Technologies | Energy Storage & Batteries | ⚠️ Emerging Bear | −6.8% | −10.8% |
TE | T1 Energy | Energy Storage & Batteries | ⚠️ Emerging Bear | −21.2% | +74.7% |
STEM | Stem | Renewable Utilities | 🔴 Cont. Bear | −23.8% | −75.5% |
RUN | Sunrun | Residential Solar Installers | 🔴 Cont. Bear | −14.2% | −55.6% |
FSLR | First Solar | Solar Module Manufacturers | ⚠️ Emerging Bear | −15.8% | −19.2% |
ENPH | Enphase Energy | Inverters & Power Electronics | 🔴 Cont. Bear | −16.8% | −11.2% |
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −6.8% | +81.1% |
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | +4.7% | +21.1% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.2% | +16.8% |
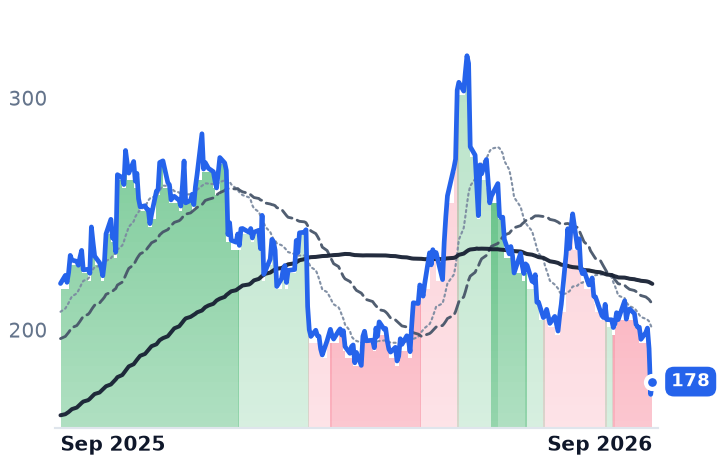
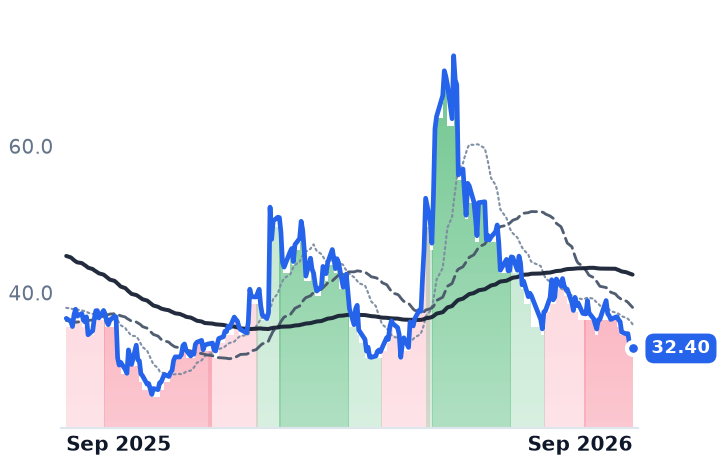
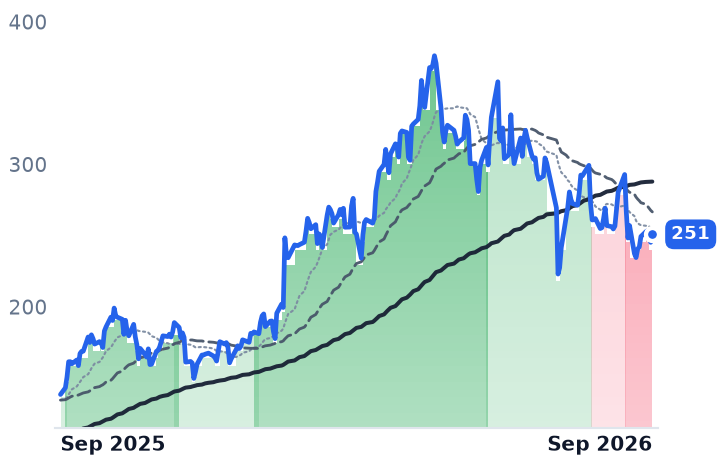
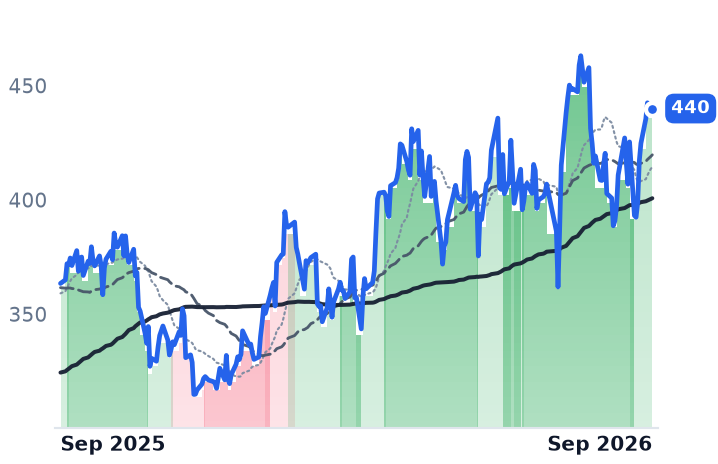
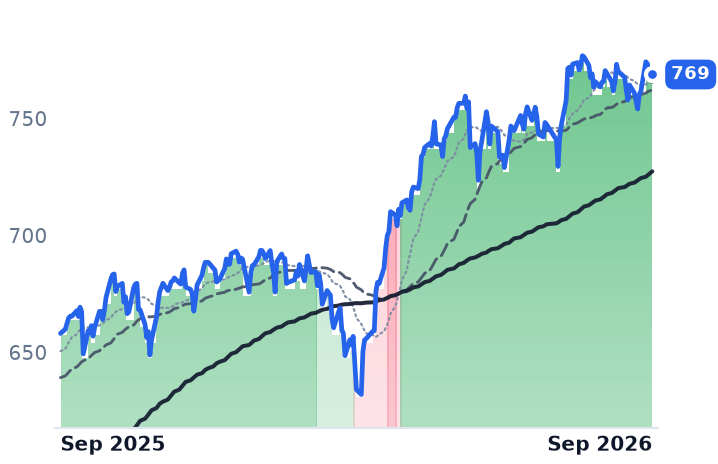
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SLDP | $537.7M | n/m | — | 52.5x | 97.7x | — | — | n/m | -13.4% |
ENS | $6.5B | 18.7x | 13.4x | 1.7x | 1.7x | 5.6x | 5.5x | 12.0x | 11.0% |
EOSE | $916.5M | n/m | — | 4.3x | 3.0x | — | — | n/m | -45.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLNC | $1.4B | n/m | — | 0.5x | 0.5x | 5.6x | 5.8x | n/m | -9.7% |
ENVX | $737.4M | n/m | — | 20.6x | 19.1x | — | — | n/m | -16.8% |
AMPX | $1.5B | n/m | — | 13.8x | 11.1x | 61.9x | 49.7x | n/m | -3.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TE | $1.3B | n/m | — | 1.3x | 1.3x | 15.3x | 15.7x | n/m | -14.6% |
STEM | $49.4M | n/m | — | 0.3x | 0.3x | 0.9x | 0.9x | n/m | 11.8% |
RUN | $2.1B | 5.1x | 6.9x | 0.6x | 0.7x | 1.7x | 1.9x | 23.4x | -65.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLR | $22.5B | 12.9x | 12.0x | 4.2x | 4.5x | 9.5x | 10.2x | 8.6x | 6.7% |
ENPH | $4.9B | 36.1x | 18.4x | 3.7x | 4.1x | 7.8x | 8.7x | 27.9x | 3.1% |
VRT | $100.8B | 58.0x | 39.0x | 8.8x | 7.2x | 23.4x | 19.2x | 40.1x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETN | $165.2B | 43.1x | 31.4x | 5.5x | 5.0x | 15.3x | 14.0x | 28.8x | 2.7% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SLDP | Revenue | −73.3% | +19.4% | +617.7% |
| EPS | −23.1% | +12.5% | +13.3% | |
ENS | Revenue | +3.3% | +4.6% | +4.9% |
| EPS | +3.5% | +29.2% | +7.5% | |
EOSE | Revenue | +104.1% | +87.2% | +86.5% |
| EPS | −82.9% | −69.8% | −181.4% | |
FLNC | Revenue | −2.2% | +29.5% | +23.4% |
| EPS | +268.3% | −77.1% | −167.6% | |
ENVX | Revenue | +25.5% | +100.3% | +187.8% |
| EPS | −4.7% | +4.2% | −71.5% | |
AMPX | Revenue | +92.7% | +54.9% | +72.8% |
| EPS | −63.2% | −183.2% | +445.7% | |
TE | Revenue | +31.5% | +41.3% | +25.5% |
| EPS | −57.7% | −92.0% | −1302.6% | |
STEM | Revenue | +0.1% | +17.5% | +22.8% |
| EPS | +31.7% | −13.6% | −43.0% | |
RUN | Revenue | +29.7% | +3.5% | +12.9% |
| EPS | −8.2% | −65.9% | −38.3% | |
FSLR | Revenue | −1.7% | +17.1% | +11.8% |
| EPS | +19.5% | +34.3% | +25.9% | |
ENPH | Revenue | −19.1% | +6.2% | +10.8% |
| EPS | −28.8% | +14.0% | +18.9% | |
VRT | Revenue | +37.0% | +29.7% | +21.9% |
| EPS | +62.8% | +36.4% | +27.1% | |
ETN | Revenue | +19.7% | +10.7% | +9.8% |
| EPS | +12.4% | +18.7% | +17.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Solid Power, a development-stage maker of sulfide solid electrolytes for electric-vehicle batteries based in Louisville, Colorado, reported a June quarter in which its revenue line pointed the wrong way past zero. The company recorded revenue and grant income of minus $0.3m, after a $1.2m catch-up reversal of revenue previously booked on a research-and-development licence with the Korean cell maker SK On, it disclosed on August 4. Stripped of grant income, the revenue line alone was minus $1.0m against $7.5m a year earlier. Operating loss was $30.3m.
The reversal matters less than what it exposes. Solid Power sells nothing; every dollar it has ever recognized is a partner payment tied to a milestone, and the milestones have run out. Site acceptance testing, the final milestone under the SK On line-installation agreement, was completed in early April, and the $3.1m of March-quarter revenue came mostly from progress toward it. Phase 1 of the Joint Evaluation Agreement with Samsung SDI and BMW expires on September 30 with later phases still in negotiation. That makes this the cleanest listed read on whether carmakers are still paying for next-generation cell chemistry or quietly letting the contracts lapse.
Asked on the August 4 call about a replacement collaboration with SK On, chief executive John Van Scoter said: "I wish I could report out more. I really can't right now. It's still early stages. So I think next quarter, we'll be able to give you some more color on that." The sell side has taken the hint and modelled a drought rather than a gap: consensus revenue of $5.5m for 2026, down 73% from $21.7m in 2025, and only $6.6m in 2027. Industry timing has slipped the same way — pilots in 2026, first commercialization in 2027-2028, and BMW itself targeting mass production only before 2030.
What the price is paying for
Solid Power held $419.3m of liquidity at the end of June with no debt, against guided 2026 cash investment of $85m-$100m for operations and capital projects: roughly four years at that pace. The equity's problem is contract flow, not solvency. Sales multiples on a collapsing milestone line are meaningless, so the usable anchor is price-to-book at 1.08x — and against a $537.7m market value, the arithmetic leaves about $118m for the electrolyte technology. The burn erodes the book by about a fifth a year, which is rational work for a discount to do. The shares are down 9.5% over three months and 39.2% over twelve.
The two nearby storage names fell harder on better news. EnerSys, which builds uninterruptible power supplies for data centers and batteries for electric forklifts, lifted first-quarter operating income 75.1% to $151.4m on a gross margin of 33.5%, and trades at 13.4x forward earnings against 18.7x trailing — falling while getting cheaper, with the caveat that Section 45X manufacturing credits supply roughly 37.5% of guided second-quarter adjusted earnings. Eos Energy, which sells zinc-based grid systems, grew June-quarter revenue 351% to $68.8m, carries a record $807m backlog and drew $87m on September 14 under the second tranche of its Department of Energy loan — yet still trades at 4.28x trailing sales against Fluence Energy's 0.52x, eight times the direct grid-storage rival's multiple. Both dropped alongside a clean-energy complex where Fluence fell 60.3% and Sunrun 45.6% over three months, while the market rose; the likelier reading is the cost of the upfront capital these projects need, with long yields at levels the paper noted this week.
So the group is not one trade. EnerSys and Eos are being repriced for financing conditions their operating results contradict. Solid Power is being repriced for something its own filings confirm: a revenue line that exists only when a partner signs, and no partner currently signed for next year.
Four more years of cash buys management time to negotiate. The clock that runs out first is the one on the Samsung SDI and BMW evaluation, and it stops this week.