

Fervo Energized Cape Station With 1,054 MW Contracted and $113,000 of Quarterly Revenue
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The first utility-scale enhanced-geothermal plant reached the grid this week, and the stock that owns it fell 9.2% the session after. Fervo Energy synchronized Cape Station in Utah on 24 September, with its first 33-megawatt block due at its contractual commercial operations date by 1 October, against 1,054 MW of binding offtake and a June quarter that booked $113,000 of revenue.
At the incumbent, Ormat, the delivery meter that the data-center story rests on is barely moving: first-half electricity revenue rose 3.1% while the fast-growing lines were merchant batteries, up 195.1%, and a one-off turbine delivery. Ormat's cheapening is real against cash profit and not against earnings, where consensus has 2027 profit falling. Neither company is yet being paid a premium for a 90% capacity factor.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
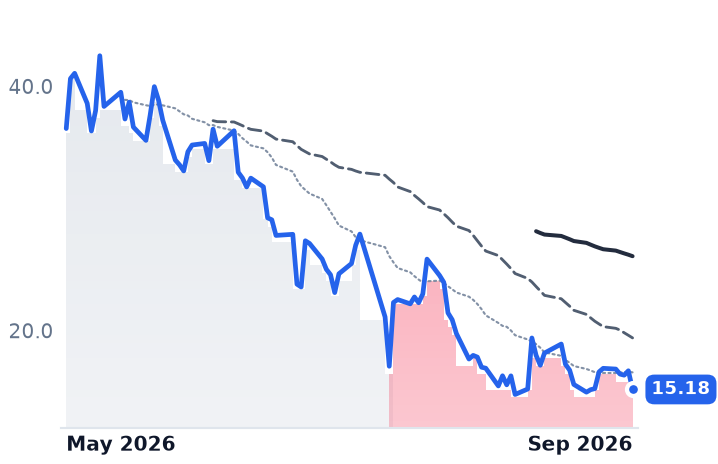
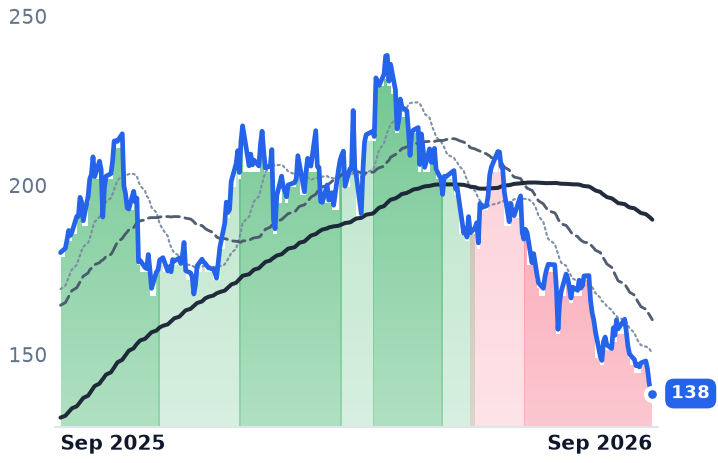
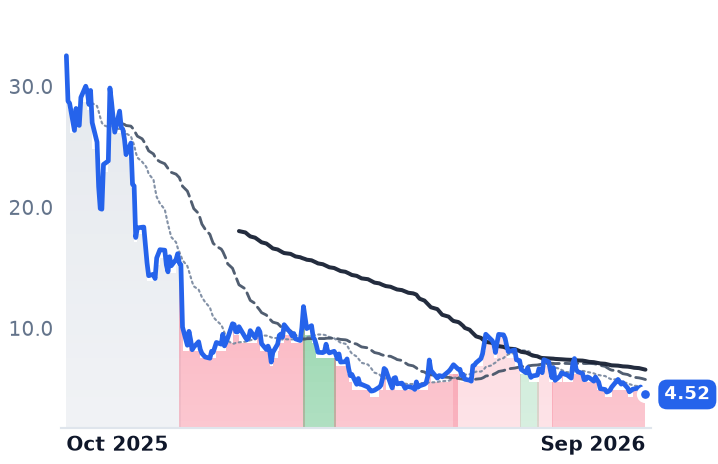
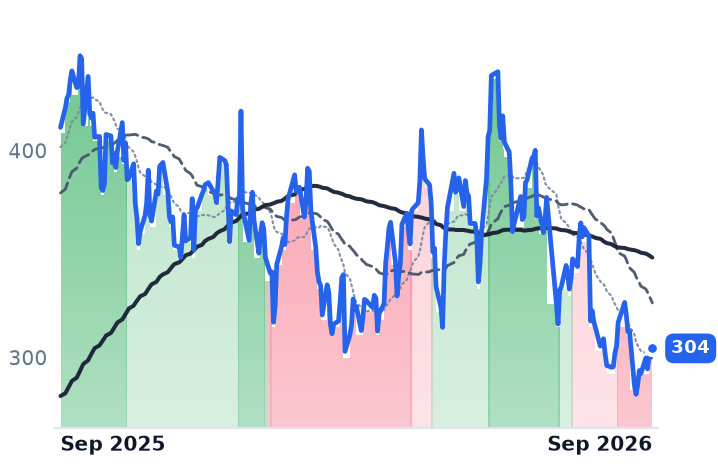
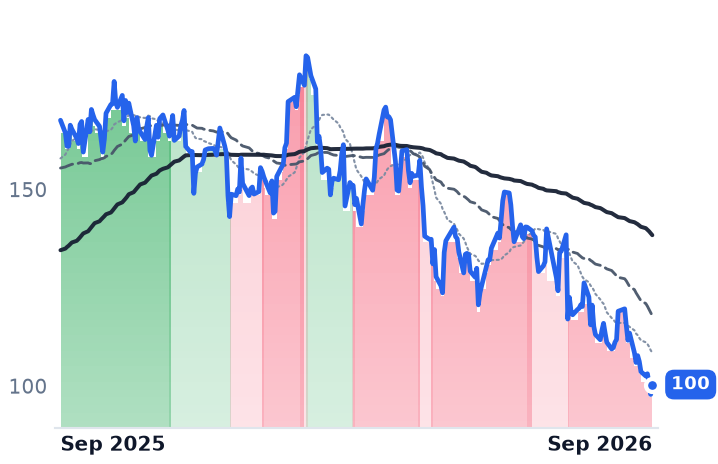
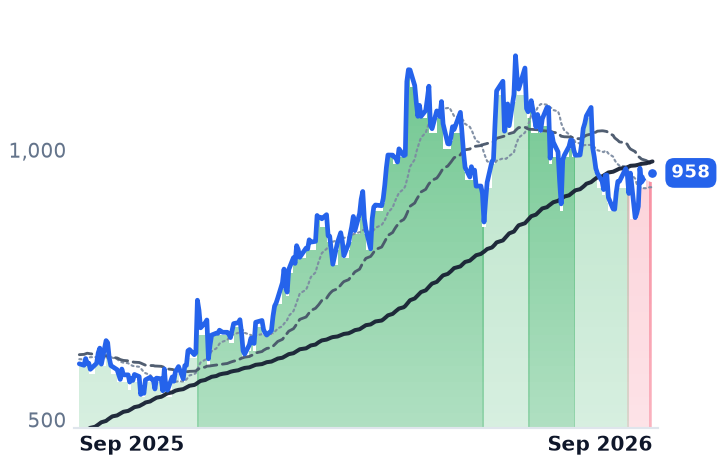
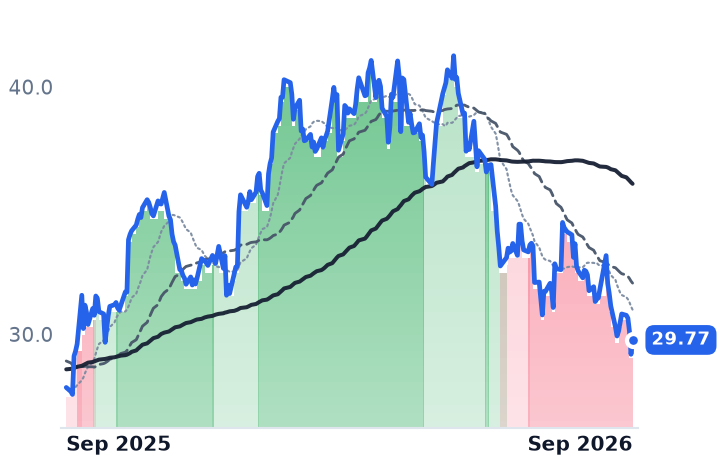
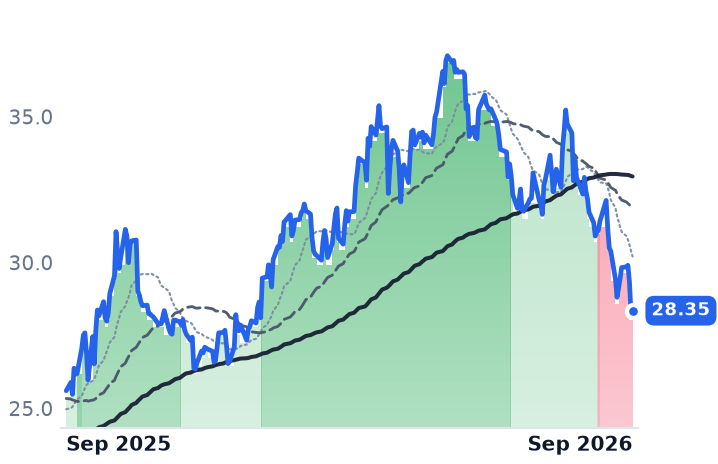
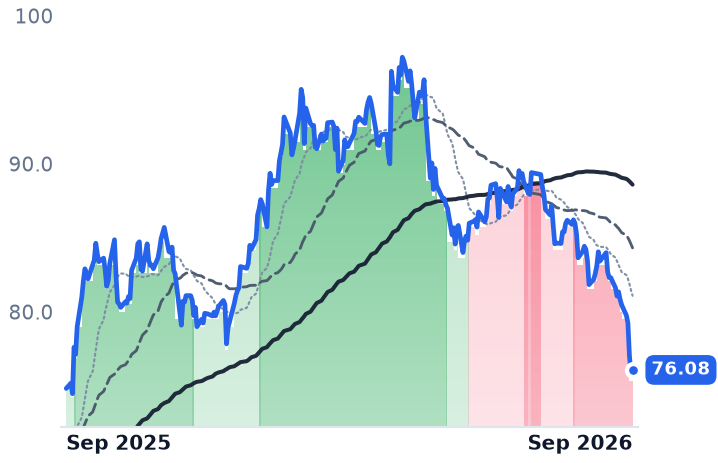
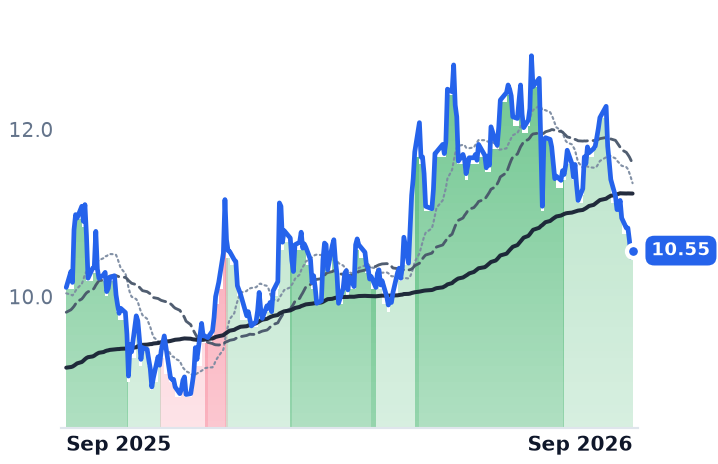
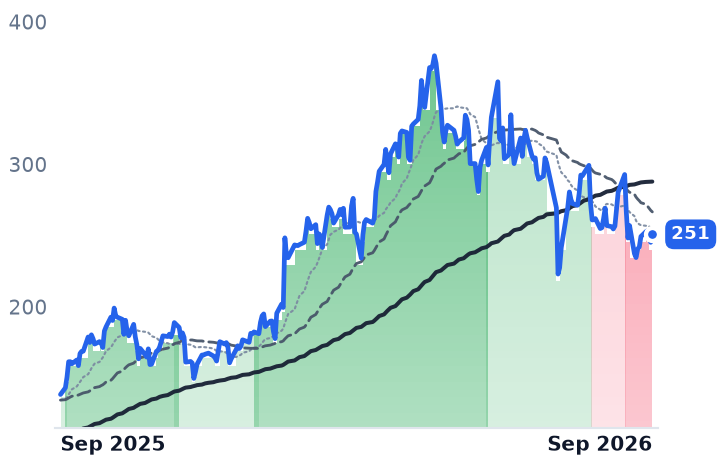
FRVO | Fervo Energy | Emerging & Specialized Energy | 🔴 Cont. Bear | −6.8% | −58.5% |
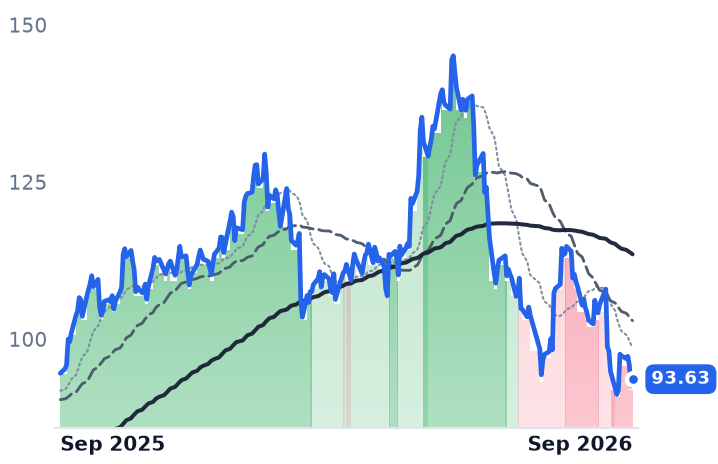
ORA | Ormat Technologies | Geothermal & Specialized | ⚠️ Emerging Bear | −10.2% | −1.0% |
| Compared against · context, not the story | |||||
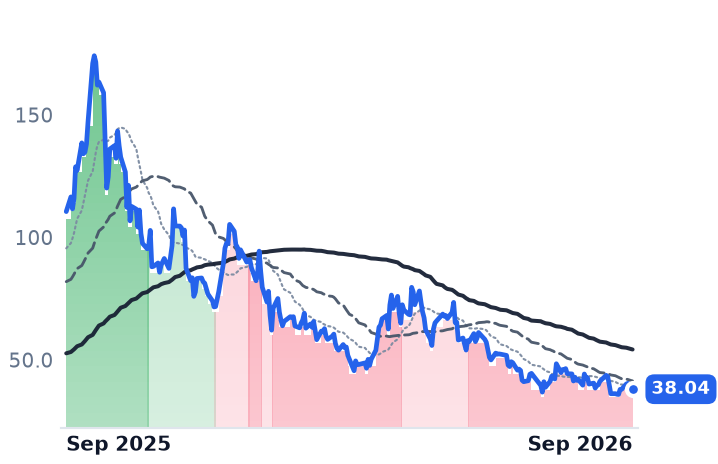
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −11.0% | −65.6% |
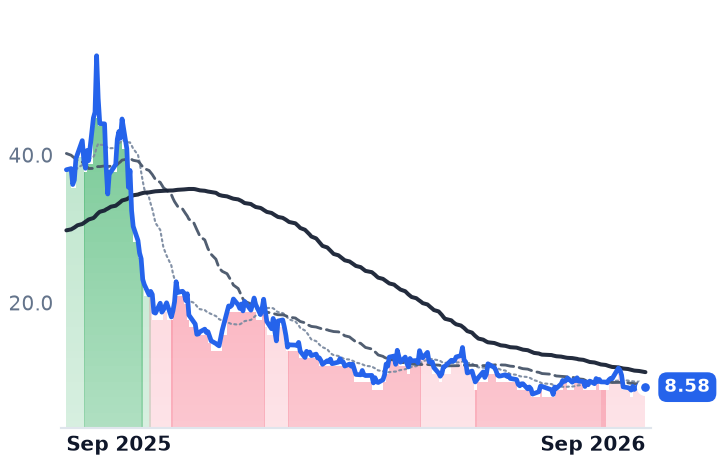
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | −12.5% | −77.8% |
BWXT | BWX Technologies | Naval & Shipbuilding | 🔴 Cont. Bear | −10.8% | −23.1% |
FRMI | Fermi | Emerging & Specialized Energy | 🔴 Cont. Bear | −18.4% | −86.1% |
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | −5.8% | −20.3% |
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | −1.0% | −33.0% |
TLN | Talen Energy | Wholesale Power Producers | ⚠️ Emerging Bear | +0.9% | −26.0% |
NRG | NRG Energy | Integrated Retail & Generation | 🔴 Cont. Bear | −11.5% | −40.1% |
GEV | GE Vernova | GE Vernova Integrated | ⚠️ Emerging Bear | +0.4% | +58.6% |
CWEN | Clearway Energy | Wind & Solar Developers | ⚠️ Emerging Bear | −8.1% | +6.9% |
BEP | Brookfield Renewable Partners | Diversified Renewable Generators | ⚠️ Emerging Bear | −11.9% | +10.7% |
NEE | NextEra Energy | Vertically Integrated Utilities | 🔴 Cont. Bear | −8.9% | +1.7% |
XIFR | XPLR Infrastructure | Renewable & Infrastructure Assets | 🟢 Cont. Bull | −10.5% | +4.4% |
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −5.9% | +82.8% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.1% | +17.2% |
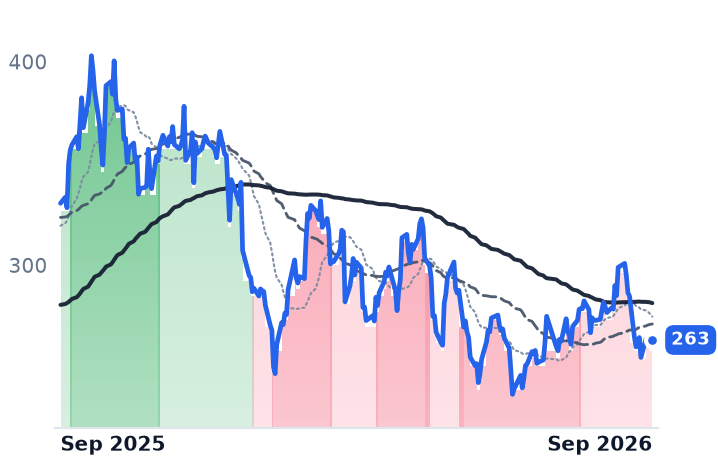
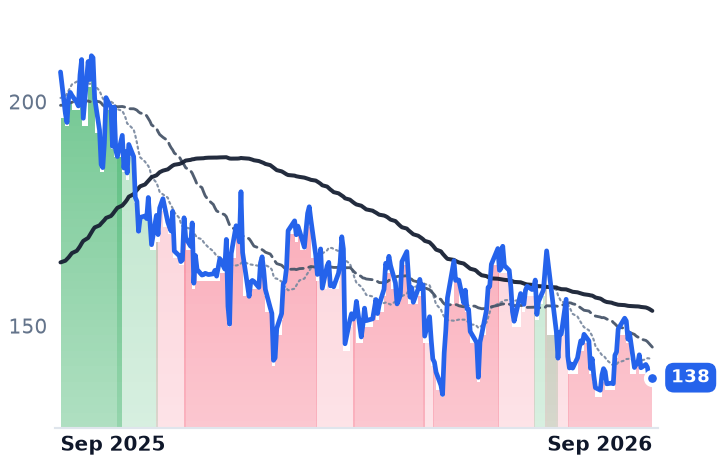
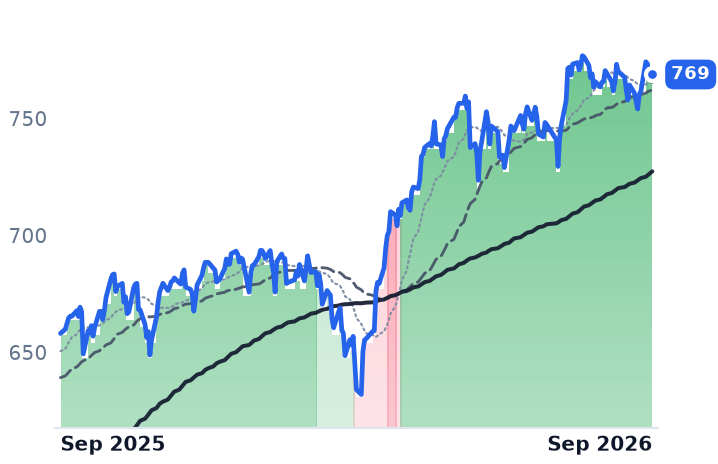
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FRVO | $4.4B | n/m | — | — | 779.1x | — | — | n/m | -10.2% |
ORA | $5.8B | 45.0x | 36.8x | 4.8x | 4.9x | 17.3x | 17.5x | 19.9x | -4.6% |
OKLO | $6.6B | n/m | — | — | — | — | — | n/m | -4.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
BWXT | $12.7B | 35.7x | 29.2x | 3.6x | 3.3x | 16.4x | 15.1x | 25.5x | 2.5% |
FRMI | $3.8B | n/m | — | n/m | 208.4x | — | — | n/m | -31.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEG | $94.6B | 25.6x | 21.8x | 3.0x | 2.8x | 3.2x | 3.0x | 13.9x | 0.3% |
VST | $47.3B | 23.4x | 16.5x | 3.0x | 2.1x | 22.8x | 16.4x | 10.3x | 2.9% |
TLN | $14.2B | n/m | 15.2x | 4.0x | 3.2x | 9.0x | 7.2x | 29.6x | 3.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NRG | $21.7B | 26.9x | 11.6x | 0.6x | 0.6x | 3.6x | 3.8x | 10.6x | 1.6% |
GEV | $242.9B | 25.9x | 29.7x | 5.9x | 5.2x | 29.0x | 26.0x | 27.0x | 5.1% |
CWEN | $6.3B | 40.3x | — | 4.0x | 3.8x | 7.6x | 7.2x | 14.3x | 10.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BEP | $9.1B | 64.8x | — | 1.4x | 1.4x | 5.9x | 5.6x | 9.7x | -51.7% |
NEE | $165.4B | 17.7x | 19.7x | 5.7x | 5.3x | 7.9x | 7.4x | 15.4x | -6.2% |
XIFR | $1.0B | 16.1x | 9.5x | 0.9x | 0.8x | 4.9x | 4.4x | 8.8x | -62.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $100.8B | 58.0x | 39.0x | 8.8x | 7.2x | 23.4x | 19.2x | 40.1x | 2.9% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FRVO | Revenue | +3950.2% | +1194.6% | +180.9% |
| EPS | −91.5% | −23.2% | −20.3% | |
ORA | Revenue | +21.4% | −1.7% | +11.1% |
| EPS | +16.3% | −3.5% | +28.4% | |
OKLO | Revenue | — | +247.8% | +498.2% |
| EPS | +64.1% | +8.1% | +10.3% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% | |
BWXT | Revenue | +20.6% | +9.8% | +7.3% |
| EPS | +24.1% | +11.2% | +11.8% | |
FRMI | Revenue | +14.5% | +2797.8% | +327.6% |
| EPS | +326.2% | −116.4% | +1983.0% | |
CEG | Revenue | +36.6% | +2.7% | +5.5% |
| EPS | +28.9% | +10.4% | +26.4% | |
VST | Revenue | +15.7% | +10.2% | +4.8% |
| EPS | +78.3% | +20.0% | +18.4% | |
TLN | Revenue | +84.0% | +15.8% | +4.6% |
| EPS | +247.6% | +48.4% | +17.8% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.5% | +15.8% | |
GEV | Revenue | +23.9% | +14.8% | +15.0% |
| EPS | +321.7% | −19.5% | +40.7% | |
CWEN | Revenue | +14.5% | +11.5% | +12.2% |
| EPS | −116.0% | −318.9% | +60.4% | |
BEP | Revenue | +3.9% | +7.6% | −11.5% |
| EPS | +5.7% | −20.9% | −6.6% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.1% | +8.5% | |
XIFR | Revenue | +0.8% | +4.7% | +1.3% |
| EPS | −849.6% | −44.0% | −144.3% | |
VRT | Revenue | +37.0% | +29.7% | +21.9% |
| EPS | +62.8% | +36.4% | +27.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Fervo Energy, a Houston developer that drills geothermal wells with the horizontal-drilling and fiber-optic sensing methods of the shale patch, put power on the grid at its Cape Station project in Beaver County, Utah on 24 September — the first utility-scale enhanced-geothermal plant to do so. The first of three 33-megawatt blocks in the roughly 100 MW first phase is due at its contractual commercial operations date by 1 October. The shares rose 2.2% on the announcement and fell 9.16% the next session.
What that milestone puts to the test is whether always-on clean generation actually collects a scarcity price. Geothermal's entire pitch to data centers is a capacity factor near 90%, and there are two listed ways to own it, paid in incompatible ways. Ormat Technologies sells megawatt-hours into twenty-year contracts signed years ago; Fervo sells capacity that bills only once wells are drilled, financed and energized. Ormat realized roughly $91.5 per megawatt-hour across its portfolio in the first half. Fervo has told investors its behind-the-meter economics stay competitive in a $100–130 range.
Ormat's growth came from batteries and a turbine
On the consolidated line Ormat is doing well. June-quarter revenue rose 10.6% to $258.8m, gross profit rose 20.7%, and on 5 August management raised full-year guidance to $1.15–1.20bn. On the line the clean-firm-power thesis rests on, it is not. First-half electricity revenue rose 3.1% to $350.9m as generation rose 2.0% to 3.83 million megawatt-hours — an implied price barely above last year's. Operating income fell 3.2% in the quarter.
The growth sat elsewhere. Merchant energy storage revenue rose 195.1% to $42.8m on favorable spot pricing, at a margin management guided down toward 40–50%, and the first quarter carried a $105m turbine delivery for the Topp 2 project at engineering-and-construction margins. That delivery is why the product backlog fell to about $203m. "Demand for reliable, carbon-free baseload power continues to strengthen, particularly from data centers," chief executive Doron Blachar told investors, citing a 15-year portfolio contract of up to 150 MW to serve Google through NV Energy — a deal whose deliveries begin in 2028 and whose price is not disclosed.
Ormat now trades at 17.3 times trailing gross profit, against 20.1x in August and 25.9x in May, while that gross profit grew. Sales multiples flatter a business shifting into third-party construction work, so cash profit is the comparison that holds. On earnings the compression is harder to call unearned: 36.8 times forward profit rests on a consensus that has 2027 revenue down 1.7% and earnings per share down 3.5%, because the lumpy turbine year does not repeat.
Fervo's meters all improved
Every disclosed operating number at Fervo moved the right way. Binding offtake reached 1,054 MW and a $7.2bn revenue backlog after Google contracted 396 MW on 1 September. Its Sawtooth 7 well hit 19,500 feet and 460°F in 21 days, against more than 70 days for the original Project Red wells at shallower depth and lower heat. The 2030 capacity target went up to 1.1 gigawatts. "This is a gamechanger for the geothermal industry," chief executive Tim Latimer said on 24 September.
The shares are 43.8% below the $27 May listing price anyway. The binding constraint is money, not contracting: $2.1bn of cash against $228.4m of debt, second-half capex guided to $850–900m, and a Phase II target of $5,500 per kilowatt of installed capacity. Book value is the only multiple that means much here — 1.60 times, with most of the book being IPO cash — since consensus puts revenue at $72.4m in 2027 and first profit in 2029. Bank of America's Ross Fowler cut his target on 25 September while keeping a Buy, citing a lower peer group multiple of 12.8 times against 14.2 times — the analyst's own words for a re-rating rather than a forecast cut. Wolfe Research upgraded the stock the same day.
What the discount is for
Neither de-rating is an operating failure. The whole capital-intensive power complex fell together as the 30-year Treasury yield reached 5.49%, its highest since 2004, and cash flows arriving in 2029 lose the most present value when the long end moves. What is specific to geothermal sits underneath that: Ormat's incremental dollar now comes from low-margin construction and merchant batteries rather than contracted firm power, and Fervo's revenue line cannot begin converting its backlog until Phase II wells are funded and drilled. A 90% capacity factor is not yet showing up in either company's realized price in a way an investor can read.
About one in ten of Cape Phase II's roughly 80 planned wells is finished. The next number that matters is not a multiple — it is the first invoice Fervo sends.