

Brown-Forman Is Cutting New Barrel Fills Another 30% as the Whiskey Glut Drains
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Drinks shares have de-rated for two and a half years on the belief that the drinkers are gone. At the two largest US-listed names the operating line is going the other way: Brown-Forman's organic operating income rose 4% last quarter, and Constellation Brands' beer shipments grew 1.8% while depletions were roughly flat.
Diageo is the genuine deterioration — organic net sales fell 2.0% on negative price/mix, North America its worst region, and the dividend halved. Brown-Forman is instead withdrawing supply, cutting barrel fills and capital spending, which is how a glut ends.
What none of that fixes is participation: the share of US adults who drink sits at a record-low 54%. And Brown-Forman's 15.3x forward earnings is being paid for flat profits, not a recovery.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
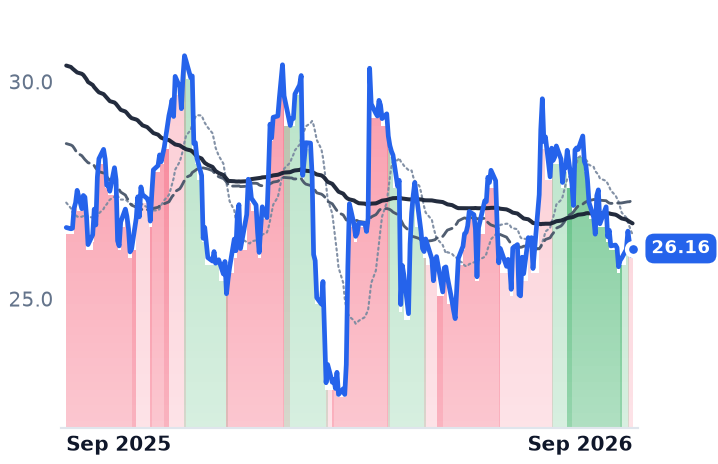
BF-B | Brown-Forman | Beverages - Wineries & Distilleries | 🔴 Cont. Bear | −5.7% | −1.8% |
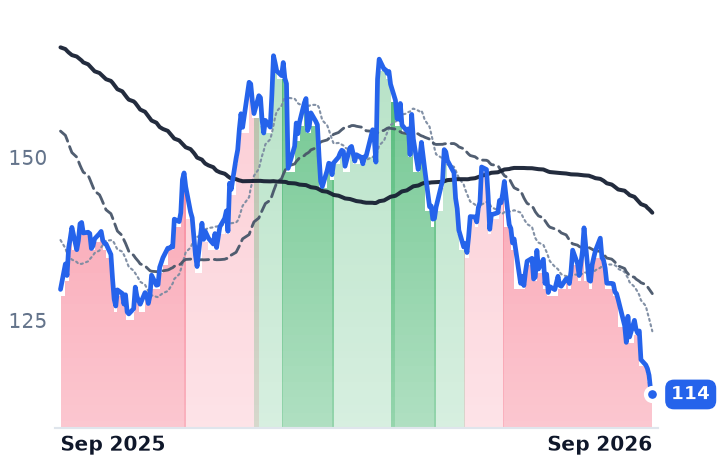
STZ | Constellation Brands | Beverages - Alcoholic | 🔴 Cont. Bear | −14.6% | −12.4% |
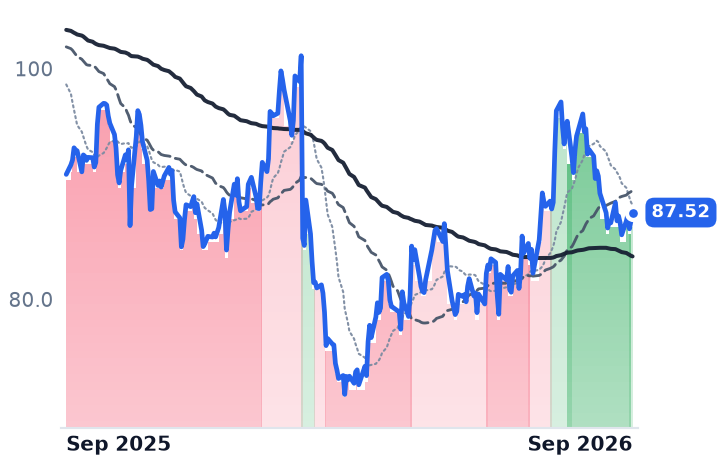
DEO | Diageo | Beverages - Alcoholic | 🌱 Emerging Bull | −5.5% | −3.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BF-B | $12.2B | 17.0x | 15.3x | 3.1x | 3.1x | 5.1x | 5.1x | 13.5x | 7.6% |
STZ | $19.4B | 10.8x | 9.7x | 2.1x | 2.1x | 4.1x | 4.1x | 9.0x | 9.5% |
DEO | $48.7B | 27.9x | 17.5x | 2.5x | 2.5x | 4.1x | 4.3x | 10.9x | 6.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BF-B | Revenue | −3.7% | +1.0% | +1.7% |
| EPS | −4.1% | −2.0% | +0.4% | |
STZ | Revenue | −10.5% | −0.1% | +1.8% |
| EPS | −13.5% | +0.8% | +4.7% | |
DEO | Revenue | −2.7% | −2.7% | +1.1% |
| EPS | +2.7% | +4.3% | +6.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Kentucky is distilling less on purpose
Brown-Forman, the Louisville distiller of Jack Daniel's, Old Forester, Herradura tequila and Korbel sparkling wine, is deliberately shrinking the amount of whiskey it puts into wood. "In calendar 2025, there is a term called new fills, which is basically, I guess it is what it sounds like. It is filling up a new barrel. It was down 30% in calendar 2025," Lawson Whiting, president and chief executive, told investors on the September 2 call. "We do not know what the number is, but I can almost guarantee you it is going to be at least 30% this year." Capital spending has been guided to $60-70m for the current year, against $125-135m set for the year before.
That matters because a distiller's revenue line is mostly history. It books a sale when a distributor takes delivery of liquid the company committed capital to four to twelve years earlier. Brown-Forman, Diageo and Constellation Brands are all down more than 40% from their 2024 highs — Constellation by 58%, the worst of the three — and priced as though demand has broken permanently. Two of the three are reporting the opposite at the profit line, and the supply that created the American whiskey glut is now being withdrawn.
The channel explains most of the top line
Brown-Forman's quarter ended July 31 showed net sales down 1% to $911m and organic operating income up 4%, with gross margin 40 basis points better at 60.2%. Shipments trailed depletions — what distributors actually sell on to retail — by roughly four points, because a year earlier the company was filling the warehouses of newly appointed distributors and launching Jack Daniel's Tennessee Blackberry. It expects depletions to run ahead of shipments for the full year, and guidance has now been reaffirmed at three consecutive reports. "We have increased confidence that results will trend toward the more favorable end of the range," chief financial officer Jim Peters said on the same call.
A second, less visible drag is the barrel itself. Sales of used barrels and bulk whiskey collapsed from over $100m two years ago to about $30m. "You are talking 80+ million dollars in less profitability from barrel sales in two years," Whiting said. Those buyers disappeared with the craft boom: the US craft distillery count has roughly halved from a peak near 4,000. Tariffs remain an unquantified line — the European Union's suspension of retaliatory duties on American spirits ran only to February 5, 2026, and the current rate is not documented.
A beer problem is not a whiskey problem
Constellation Brands, which imports Corona Extra, Modelo Especial and Pacifico into the United States and owns the Meiomi and Robert Mondavi wine labels, is filed alongside the distillers but earns nearly all its profit from Mexican beer. In its May quarter beer shipments rose 1.8% to 113.3 million case equivalents while depletions slipped 0.3%, Pacifico and Victoria more than covering declines at Modelo Especial and Corona Extra. Gross margin reached 54.3% against 50.8% a year earlier. Its demand problem is demographic: softness has been attributed to Hispanic consumers, roughly half its US beer volume. That reads across to aged American whiskey not at all.
Constellation's 15% slide over the past month arrived without company news. Piper Sandler cut its target to $200 from $245, Jefferies to $135 from $147 and BNP Paribas to $110 from $115; second-quarter results land October 6. At 9.7x forward earnings and 9.0x enterprise value to EBITDA, against roughly 26.5x its fiscal 2024 earnings at its March 2024 price, the multiple has more than halved while beer volumes grew.
Diageo earns its discount
Diageo — Johnnie Walker, Crown Royal, Don Julio, Guinness — is where the business genuinely broke. Organic net sales fell 2.0% in the year to June 30, with volume down only 0.4% and price/mix negative 1.6%; North America fell 8.4%. "North America remains our biggest challenge, where market conditions are soft and our offer needs to be more competitive," chief executive Sir Dave Lewis said. The dividend question was settled by halving the payout to 50 cents from $1.03 alongside about $1bn of three-year savings. Net debt of $20.5bn sits at 3.1x EBITDA, down from 3.4x. At 17.5x forward earnings it is the dearest of the three.
What the businesses do and do not explain
Pricing power failing is a different illness from a channel unwinding. Diageo has the first; Brown-Forman and Constellation, on their latest numbers, have the second, and neither one's most recent month of decline is explained by anything either company reported. The caveat is what is being bought: consensus has Brown-Forman earning $1.71 a share in fiscal 2027 and the same again in fiscal 2028, against $2.15 in fiscal 2024. At 15.3x forward and a 7.6% free-cash-flow yield, the price requires only that earnings stop falling. If they do not, the de-rating was correct.
Supply is the part management controls, and it is being cut hard. Demand is the part nobody can distil away: Gallup puts the share of US adults who drink at a record-low 54% for a second straight year, with adults under 35 now drinking less than their elders for the first time in the survey's history.