

Okta's $100,000-a-Year Customer Count Grew 6%; Cloudflare's Grew 27% and Datadog's 23%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Three vendors sell into the same AI build-out and meter it three different ways — per identity, per unit of network consumed, per unit of telemetry ingested. The usage-billed pair is winning the operational contest, and the seat-billed one is winning the share price.
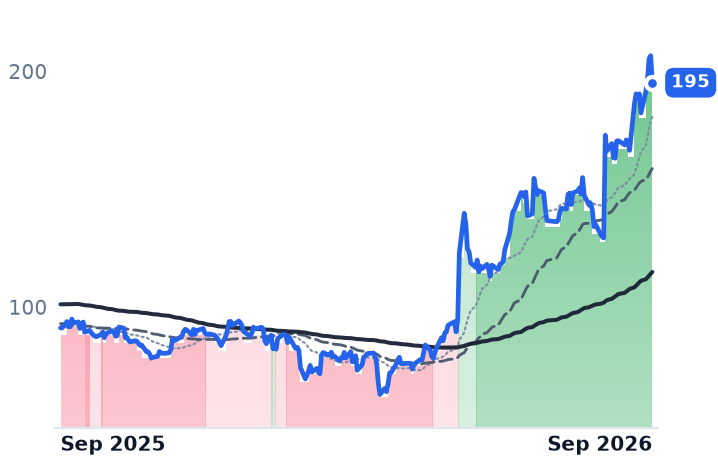
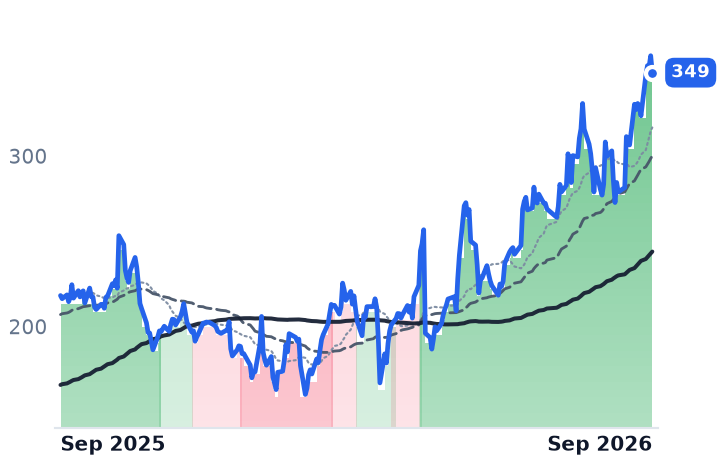
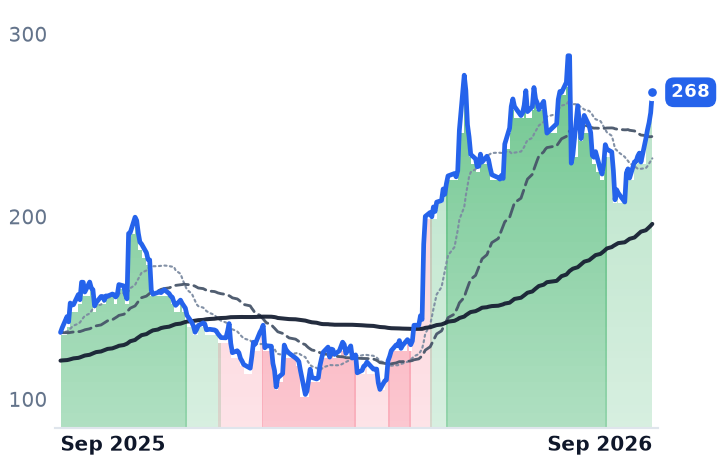
Okta's revenue growth decelerated for a fourth straight quarter, to 10.6%, while Cloudflare accelerated for a fourth straight quarter to 35.9% and Datadog to 35.6%. Yet since late July, Okta's valuation on trailing gross profit has expanded 31% and Cloudflare's 24%, while Datadog's — the fastest-accelerating business of the three, and the one whose largest customer cut usage — has not moved at all.
The mechanism test comes back mixed: Okta's gross margin expanded to 79.6% on seat billing, while Cloudflare's fell to 73.1% as paid traffic pushed network cost into cost of revenue.
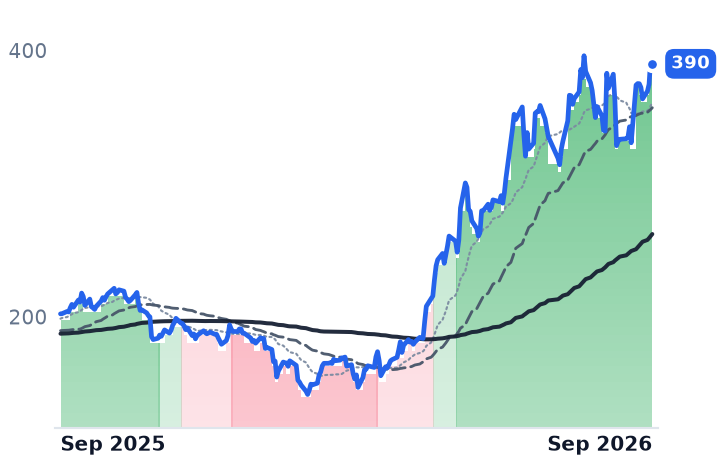
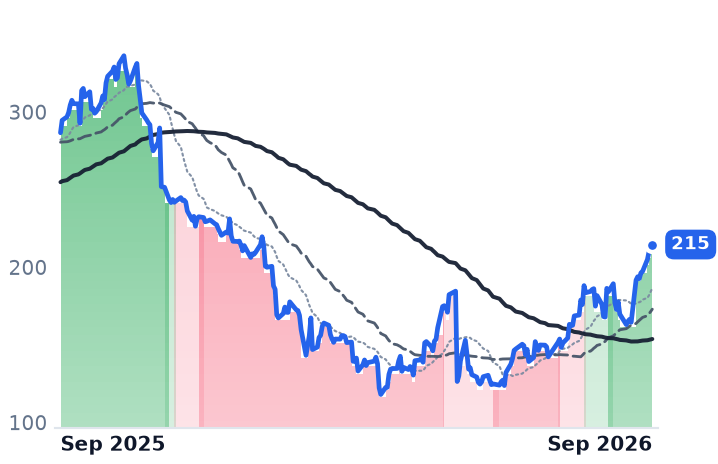
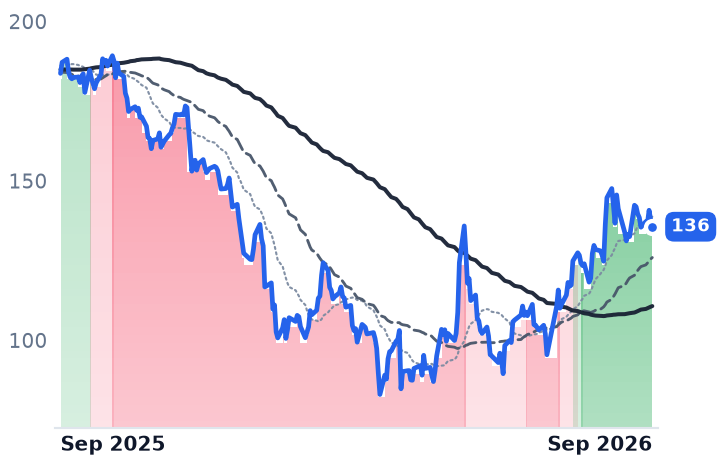
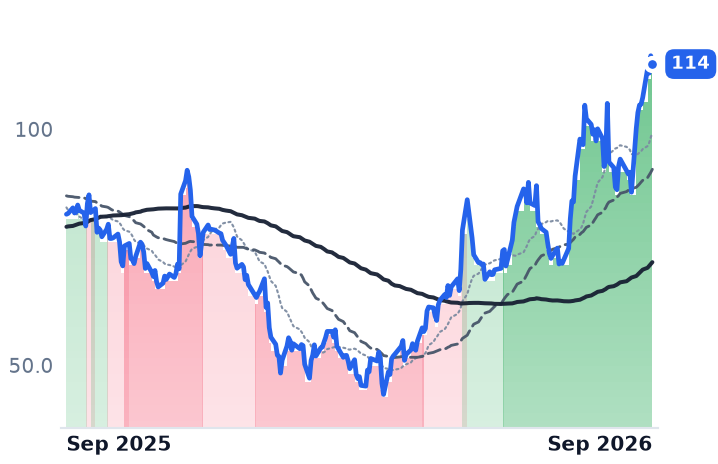
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
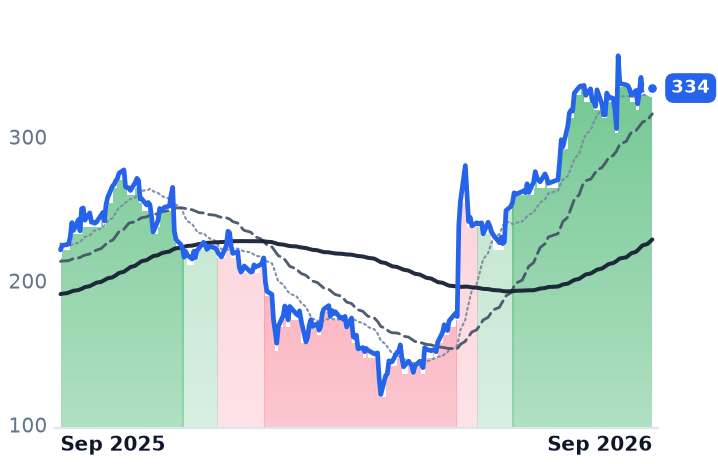
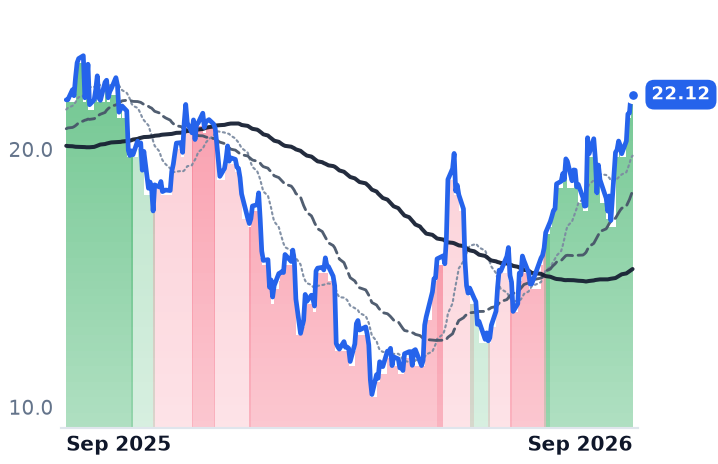
OKTA | Okta | Identity & Access Management | 🟢 Cont. Bull | +50.9% | +114.0% |
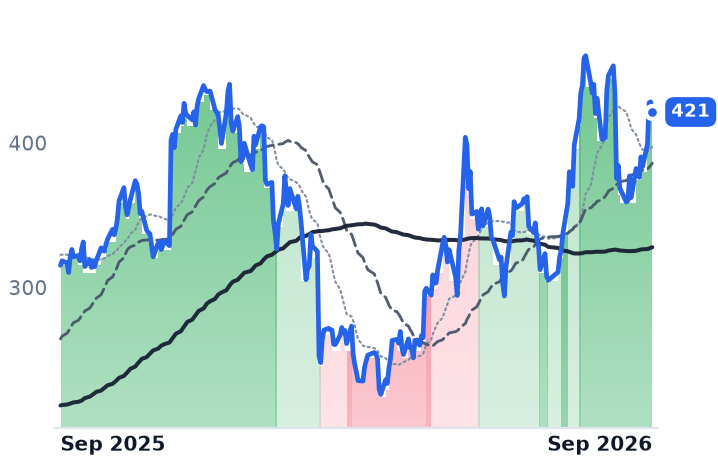
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | +23.0% | +59.9% |
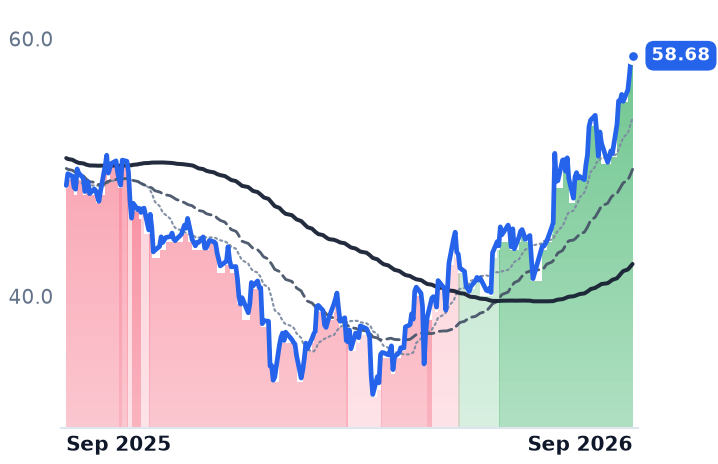
DDOG | Datadog | Data & Analytics Platforms | 🟢 Cont. Bull | +17.4% | +96.3% |
| Compared against · context, not the story | |||||
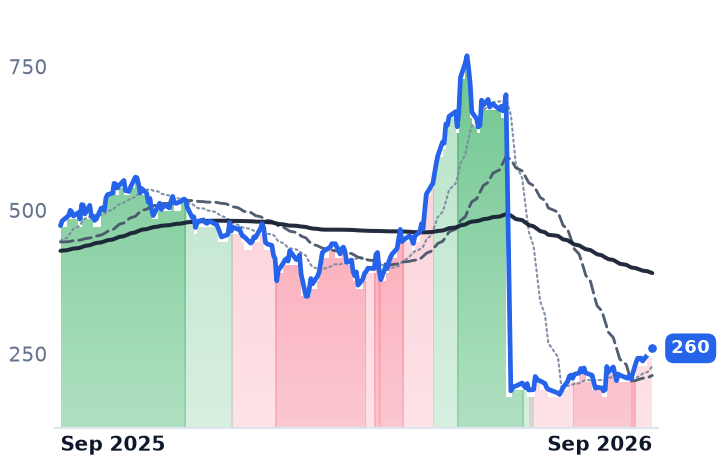
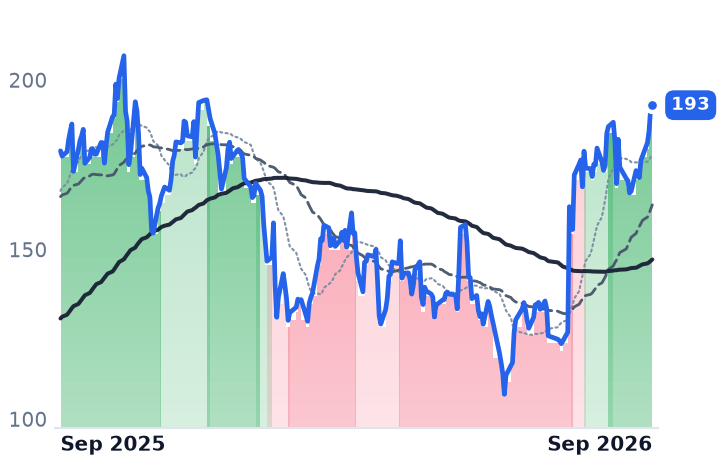
CRWD | CrowdStrike | Cybersecurity & Threat Protection | ⚠️ Emerging Bear | +38.2% | −45.1% |
PANW | Palo Alto Networks | Cybersecurity & Threat Protection | 🟢 Cont. Bull | +14.9% | +92.8% |
ZS | Zscaler | AI & Data Intelligence | 🌱 Emerging Bull | +27.8% | −25.1% |
NOW | ServiceNow | Specialized Enterprise Solutions | 🌱 Emerging Bull | +8.7% | −26.2% |
RBRK | Rubrik | Other | 🟢 Cont. Bull | +20.7% | +38.8% |
SNOW | Snowflake | Data & Analytics Platforms | 🟢 Cont. Bull | +5.9% | +50.7% |
MDB | MongoDB | Data Management & Analytics | 🟢 Cont. Bull | +4.4% | +33.6% |
DT | Dynatrace | Other | 🟢 Cont. Bull | +15.1% | +20.7% |
PLTR | Palantir Technologies | AI & Data Intelligence | 🟢 Cont. Bull | +10.2% | +7.5% |
SAIL | SailPoint | Identity & Access Management | 🌱 Emerging Bull | +24.2% | +0.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKTA | $32.4B | 115.5x | 49.7x | 10.6x | 10.1x | 13.5x | 12.9x | 80.5x | 3.0% |
NET | $123.8B | n/m | 276.6x | 49.3x | 43.2x | 67.9x | 59.5x | — | 0.3% |
DDOG | $95.4B | 539.3x | 105.9x | 24.1x | 21.3x | 30.3x | 26.8x | 365.7x | 1.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRWD | $242.0B | — | 189.5x | 44.8x | 40.3x | 59.6x | 53.5x | 544.3x | 0.7% |
PANW | $296.3B | 790.4x | 86.8x | 25.8x | 20.9x | 36.7x | 29.7x | 552.8x | 1.5% |
ZS | $31.9B | n/m | 40.4x | 9.5x | 8.1x | 12.4x | 10.6x | 176.0x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOW | $140.1B | 84.1x | 33.3x | 9.5x | 8.6x | 12.7x | 11.6x | 41.8x | 3.3% |
RBRK | $22.0B | n/m | 212.0x | 14.2x | 13.0x | 17.8x | 16.2x | n/m | 1.5% |
SNOW | $114.0B | n/m | 148.5x | 21.0x | 18.0x | 31.3x | 26.9x | n/m | 1.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MDB | $36.5B | n/m | 74.0x | 14.0x | 12.3x | 19.5x | 17.1x | — | 1.6% |
DT | $15.6B | 105.5x | 27.0x | 7.5x | 6.7x | 9.2x | 8.3x | 48.2x | 3.6% |
PLTR | $394.9B | 136.5x | 108.2x | 64.2x | 48.6x | 75.7x | 57.3x | 126.8x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SAIL | $11.5B | n/m | — | 9.9x | — | 14.9x | — | n/m | 1.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
OKTA | Revenue | +12.0% | +10.9% | +9.9% |
| EPS | +24.3% | +14.1% | +10.6% | |
NET | Revenue | +33.7% | +28.4% | +27.1% |
| EPS | +38.0% | +32.6% | +34.3% | |
DDOG | Revenue | +31.8% | +22.4% | +22.8% |
| EPS | +25.4% | +17.0% | +22.1% | |
CRWD | Revenue | +22.2% | +25.0% | +22.7% |
| EPS | −1.2% | +35.1% | +27.5% | |
PANW | Revenue | +24.3% | +24.1% | +14.4% |
| EPS | +15.5% | +10.8% | +16.3% | |
ZS | Revenue | +25.2% | +17.9% | +16.3% |
| EPS | +29.2% | +18.3% | +14.7% | |
NOW | Revenue | +22.4% | +18.7% | +18.6% |
| EPS | +17.1% | +23.2% | +21.4% | |
RBRK | Revenue | +48.7% | +32.0% | +21.5% |
| EPS | −90.5% | −389.4% | +52.5% | |
SNOW | Revenue | +29.4% | +35.7% | +28.9% |
| EPS | +72.3% | +82.7% | +36.2% | |
MDB | Revenue | +23.1% | +21.5% | +18.0% |
| EPS | +59.1% | +27.3% | +19.7% | |
DT | Revenue | +18.9% | +15.6% | +15.2% |
| EPS | +22.8% | +17.9% | +14.6% | |
PLTR | Revenue | +86.1% | +49.3% | +48.2% |
| EPS | +122.1% | +42.4% | +50.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Three vendors sell into the same artificial-intelligence build-out and bill for it three different ways, and the one whose meter is turning slowest has repriced the hardest.
Okta, which sells cloud identity — single sign-on, multi-factor authentication and lifecycle management — on annual per-user subscriptions, ended its July quarter with 5,255 customers paying more than $100,000 a year in annual contract value, 6% more than a year earlier. Cloudflare, which runs a global edge network sold as security, performance and serverless compute and charges for what crosses it, grew its count of customers above that same $100,000 threshold by 27%, to 4,698. Datadog, whose observability platform bills on telemetry volume consumed, grew its roughly 4,720-strong equivalent base about 23%.
That gap answers the question the whole group is being priced on: whether AI agents get billed as identities, as consumption, or not at all. Roughly $250bn of combined market value rides on it, and right now the market is paying it backwards.
The meters
Okta's revenue grew 10.6% to $805m, a fourth consecutive quarterly deceleration. Its forward meter is better than its reported one — current remaining performance obligation reached $2.585bn, up 14%, running ahead of billed revenue — but management guided that figure back down to 11-12% growth for the current quarter. What growth exists is concentrated: customers above $1m in annual contract value grew 22%, to more than 600, and newer governance, privileged-access and threat-protection products were 30% of bookings at roughly 40% average uplift per deal.
Cloudflare's revenue grew 35.9% to $696.1m, its fourth straight acceleration, with dollar-based net retention up six points year over year to 120%. Datadog's grew 35.6% to $1.121bn, also a fourth straight acceleration, and chief executive Olivier Pomel told investors on the August 13 call that "revenue growth for our non-AI customers also accelerated again this quarter to the high 20s percent year-over-year" — the acceleration is not confined to AI customers.
Does consumption billing scale like software?
Partly. Cloudflare's non-GAAP gross margin fell 320 basis points year over year to 73.1%, and chief financial officer Thomas Seifert attributed it to more network cost landing in cost of revenue as paid traffic grew relative to free traffic — the toll on selling compute at the edge, where non-human traffic passed half the network for the first time. It rose 30 basis points sequentially, the first such improvement in eight quarters. Datadog's slipped to 78.6%. Okta's, the seat-seller's, expanded 2.7 points to 79.6%, and its operating margin more than doubled to 13.3%.
The headcount irony runs the same direction. Cloudflare, the consumption vendor, cut roughly 1,100 jobs — about 20% of staff — on May 7 in an "agentic AI-first" restructuring costing up to $165m; the $150.7m charge is the main reason its GAAP operating loss widened to $205.7m. Okta, the per-seat vendor agents are supposed to destroy, employs 6,366 and shrank its diluted share count 1.2%. Both consumption names diluted about 2%.
What the price paid for
In late July, Okta traded at 10.29x trailing gross profit, Cloudflare at 54.90x and Datadog at 30.44x. Today Okta is 13.50x, Cloudflare 67.92x — and Datadog 30.26x, effectively unchanged. Okta was near 5x as recently as early May, when it was down 30% for the year; it bottomed at $62.93 on April 10. The claim that this corner of software never de-rated is false in both directions: CrowdStrike is down 45.5% over twelve months, ServiceNow 26.2% and Zscaler 24.5%.
Datadog's flat valuation has nameable causes. Snowflake is paying about $1bn for Observe, moving into its market, and chief financial officer David Obstler said on August 13: "Regarding our largest customer, we have seen a usage reduction, which is incorporated in our Q3 and full year 2026 guidance." The resulting third-quarter guide of $1.135bn-$1.145bn implies 28-29% growth. Consumption cuts both ways.
Okta's re-rating rests on a story rather than a number. At Oktane on September 22 it launched an agentic-enterprise reference architecture and confirmed Agent SSO is generally available inside the core product; six brokers lifted targets into a $215-$240 range this week. But finance chief Brett Tighe said on the August 26 call that agent-identity revenue is "still immaterial. Still very small. We're very early innings… for FY '27, we don't think it's going to be material." Consensus models 9.9% revenue growth for the year ending January 2028 — a fade, not an inflection. Cloudflare, meanwhile, costs about 2.4 times what Datadog does for each percentage point of gross-profit growth it delivers.
So the verdict splits. Datadog has earned its advance with accelerating revenue and no help from a re-rating; Cloudflare has earned part of one and is paying for the rest with network cost and dilution; Okta's business — decelerating revenue, 6% growth in its large-account base, margins genuinely inflecting — explains the profitability half of its move and none of the growth premium now attached to it. Billing model is not destiny, and the market has stopped treating it as evidence.
Todd McKinnon told the Oktane audience on September 23 that in agent identity "there is going to be massive growth and the market share is going to be set probably in three years." His own finance chief does not expect material revenue from it this fiscal year. The price has already paid for both.