

McDonald's Will Fund a $5bn Franchisee Rescue From Its 84.5%-Margin Rent Book
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
McDonald's equity case has rested for a decade on the claim that its profit comes from rent and royalties, not from selling hamburgers. On 23 September it told investors it will hand a large part of that profit back to the operators who pay it.
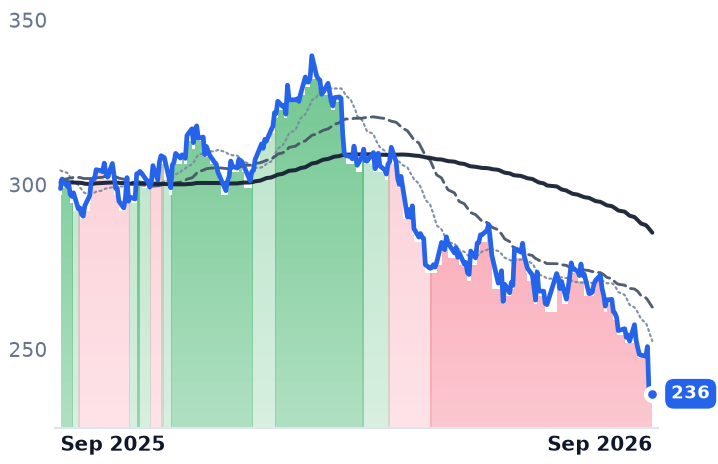
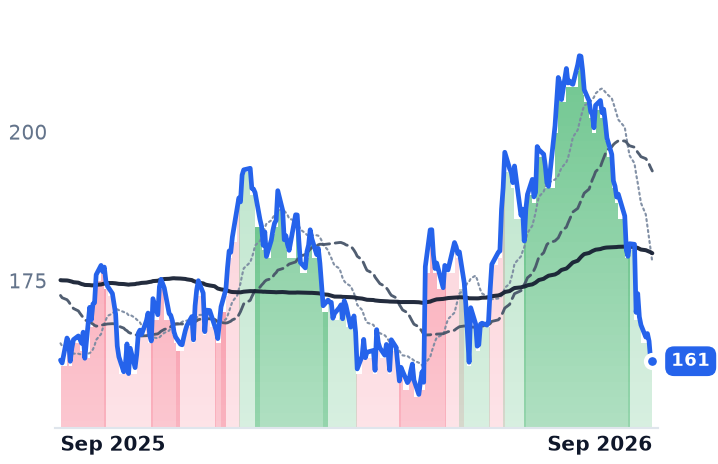
The majority of roughly $8.5bn of franchisee support committed through 2036 arrives as rent relief, and free cash flow conversion was guided down to the mid-to-high 80% range by 2030. The shares fell to four-year lows on the heaviest volume of the whole drawdown.
The business now explains most of the de-rating: McDonald's trades at 18.3x forward earnings against 22.2x trailing five weeks earlier. What it does not explain is consensus, which still models 2026 earnings up 6.4% and has not absorbed the rent disclosure. Wendy's, whose largest US franchisee filed for bankruptcy on 17 September, is the reason the bill exists.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MCD | McDonald's | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −11.2% | −20.9% |
WEN | The Wendy's | Quick Service - Burgers & Sandwiches | 🌱 Emerging Bull | −25.9% | −25.9% |
SHAK | Shake Shack | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −22.1% | −38.9% |
| Compared against · context, not the story | |||||
QSR | Restaurant Brands International | Quick Service - Pizza | 🟢 Cont. Bull | −11.3% | +12.9% |
YUM | Yum! Brands | Quick Service - Pizza | ⚠️ Emerging Bear | −11.7% | −8.0% |
DPZ | Domino's Pizza | Quick Service - Pizza | 🔴 Cont. Bear | −15.0% | −30.3% |
CMG | Chipotle Mexican Grill | Quick Service - Mexican & Bowls | 🌱 Emerging Bull | −16.2% | −20.3% |
WING | Wingstop | Quick Service - Chicken & Wings | 🔴 Cont. Bear | −12.4% | −60.2% |
TXRH | Texas Roadhouse | Casual Dining - Steakhouse & Seafood | 🟢 Cont. Bull | −20.8% | −0.1% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.4% | +17.5% |
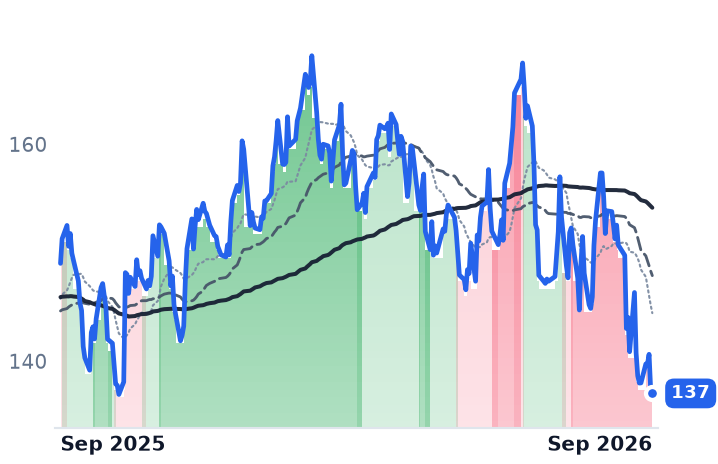
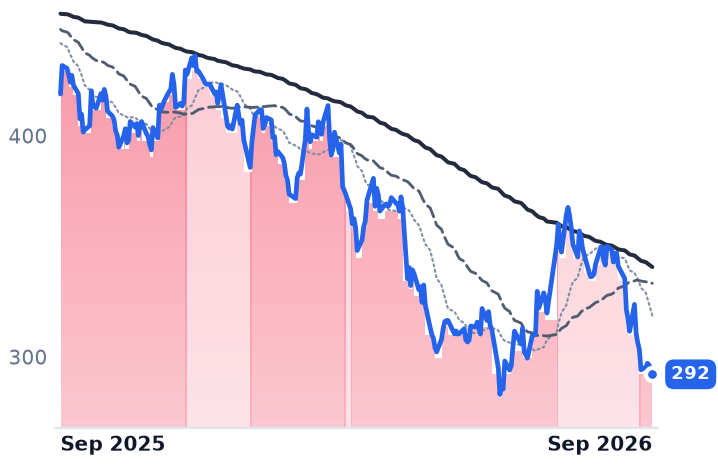
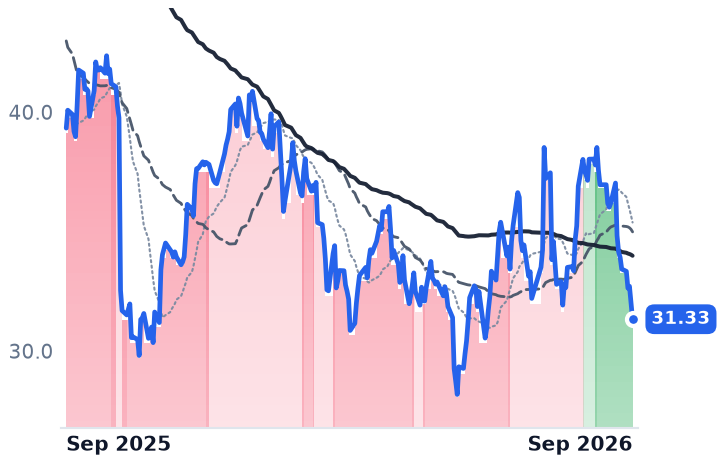
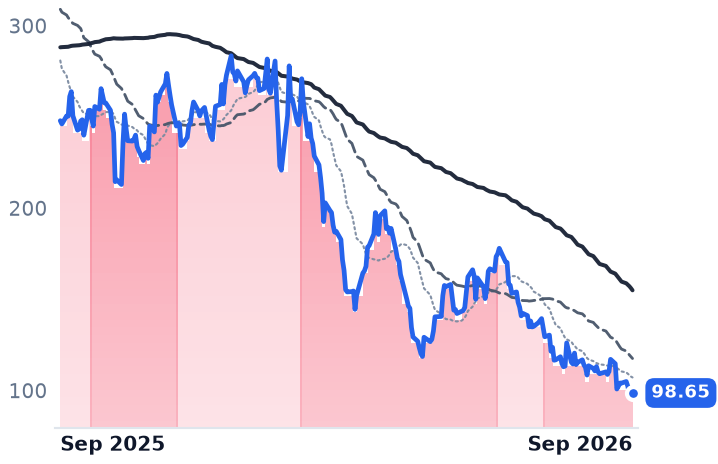
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MCD | $168.0B | 19.2x | 18.3x | 6.1x | 6.0x | 10.6x | 10.4x | 14.8x | 4.6% |
WEN | $1.2B | 9.9x | 12.9x | 0.6x | 0.6x | 2.1x | 2.1x | 10.2x | 21.2% |
SHAK | $2.2B | 56.5x | 49.0x | 1.4x | 1.4x | 5.6x | 5.3x | 12.3x | 0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
QSR | $25.0B | 17.6x | 17.8x | 2.6x | 2.5x | 5.8x | 5.7x | 14.2x | 6.3% |
YUM | $38.0B | 17.2x | 21.0x | 4.4x | 4.3x | 9.5x | 9.3x | 17.2x | 4.4% |
DPZ | $11.1B | 18.9x | 17.7x | 2.2x | 2.1x | 5.5x | 5.3x | 16.2x | 5.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CMG | $41.9B | 29.2x | 28.7x | 3.5x | 3.2x | 9.5x | 8.9x | 20.5x | 3.6% |
WING | $3.5B | 31.7x | 28.3x | 5.0x | 4.5x | 6.0x | 5.5x | 15.4x | 3.8% |
TXRH | $11.9B | 28.9x | 27.4x | 1.9x | 1.8x | 12.5x | 11.9x | 16.7x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MCD | Revenue | +5.7% | +4.9% | +3.1% |
| EPS | +6.4% | +7.9% | +6.6% | |
WEN | Revenue | +1.3% | −0.5% | +3.3% |
| EPS | −41.7% | +3.9% | +11.8% | |
SHAK | Revenue | +14.1% | +14.7% | +13.3% |
| EPS | −12.2% | +22.8% | +27.3% | |
QSR | Revenue | +5.2% | +0.5% | +0.4% |
| EPS | +10.3% | +9.1% | +9.4% | |
YUM | Revenue | +9.4% | +3.2% | +5.8% |
| EPS | +8.1% | +10.2% | +11.0% | |
DPZ | Revenue | +5.4% | +2.4% | +3.9% |
| EPS | +7.6% | +9.8% | +8.0% | |
CMG | Revenue | +9.0% | +11.0% | +10.9% |
| EPS | −1.6% | +19.6% | +18.0% | |
WING | Revenue | +11.6% | +15.4% | +14.1% |
| EPS | +17.0% | +22.2% | +24.3% | |
TXRH | Revenue | +11.0% | +9.3% | +8.6% |
| EPS | +4.7% | +18.3% | +20.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
McDonald's told investors at its Chicago investor day on 23 September that it will commit approximately $8.5bn of franchisee support through 2036, about $5bn of it by 2030, delivered as a combination of rent relief and capital support. The chain that sells burgers, chicken sandwiches, fries and breakfast across more than 40,000 restaurants collects most of its profit not from food but from its operators: in the June quarter the franchised line produced $3,713m of margin at an 84.5% rate, against 15.3% on the restaurants McDonald's runs itself. Rent relief shrinks the first number on purpose.
That is the disclosure the shares had been anticipating and could not see. The cost squeeze in fast food — a beef cow herd down to 27.6 million head, the smallest since 1961 — has been landing in franchisees' profit and loss statements all year, and the question was whether it would ever reach the franchisor. It has, by invitation. McDonald's guided free cash flow conversion down to the mid-to-high 80% range by 2030 and flagged $1.5bn to $2bn of incremental capital spending from 2027 through 2030 on top of roughly $3bn a year of normal capital expenditure. The company also intends to raise its franchised mix from about 95% to 98% by the end of 2028 — more of the cost exposure pushed onto operators it is simultaneously subsidizing.
The stock fell 5.80% that session, from $250.85 to $236.29, on 11.1m shares against a normal tape closer to 2m: the largest single-day fall and the heaviest volume of the drawdown, and it left the shares at four-year lows in a seventh consecutive losing week, down 20.7% for 2026. The dividend was raised 4% to $1.93 a quarter on 17 September, a fiftieth straight annual increase, which at the current price yields 3.26% — below the 3.75%-4.00% federal funds target set the day before, the rate backdrop this page has already described.
Why the bill exists
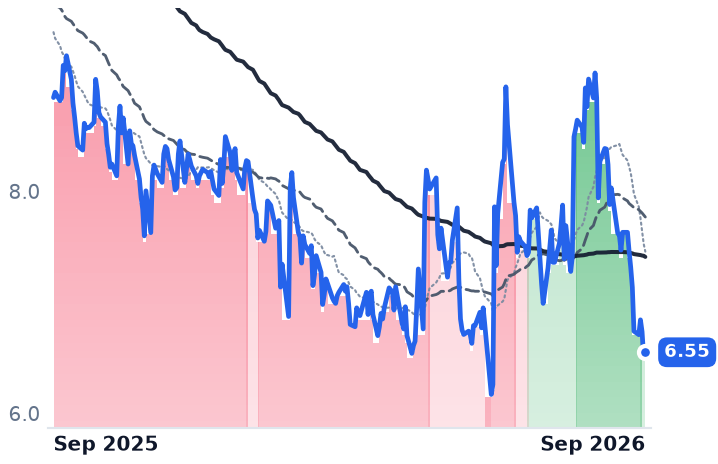
Wendy's supplies the proof. Its US same-restaurant sales fell 7.0% on a 12.5% traffic decline, 289 US closures in the first half swamped 21 openings, and 5% to 6% of its US restaurants are slated to close. Meritage Hospitality, its largest US franchisee with 314 restaurants, filed for Chapter 11 on 17 September, blaming beef costs, weak traffic and aggressive promotional discounting. Wendy's trades at 12.9x forward earnings against 9.9x trailing — the market saying earnings fall faster than the price, with consensus 2026 earnings per share 41.7% below 2025.
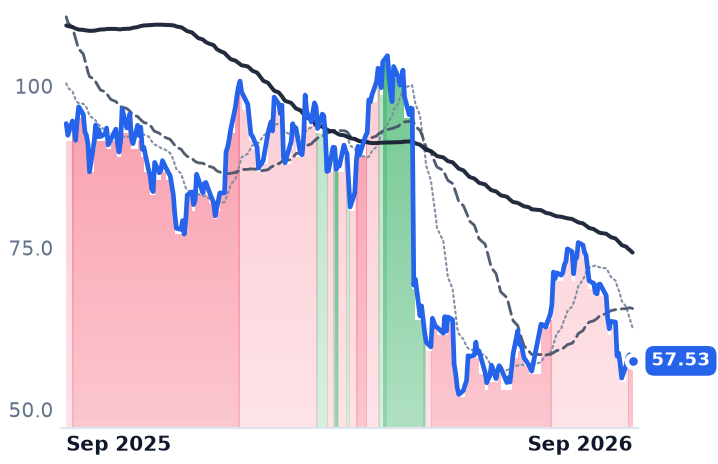
Shake Shack, which operates rather than franchises almost all its Shacks, is the cost meter. June-quarter revenue rose 17.2% purely on new openings while average weekly sales held flat at $78,000; food and paper reached 28.8% of Shack sales and operating margin fell to 4.97% from 6.28%. Its trailing enterprise value to earnings before interest, taxes, depreciation and amortization of 12.3x has now slipped below McDonald's 14.8x.
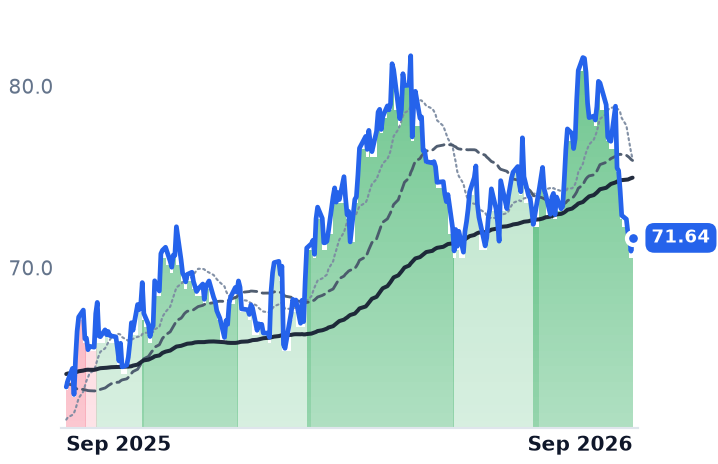
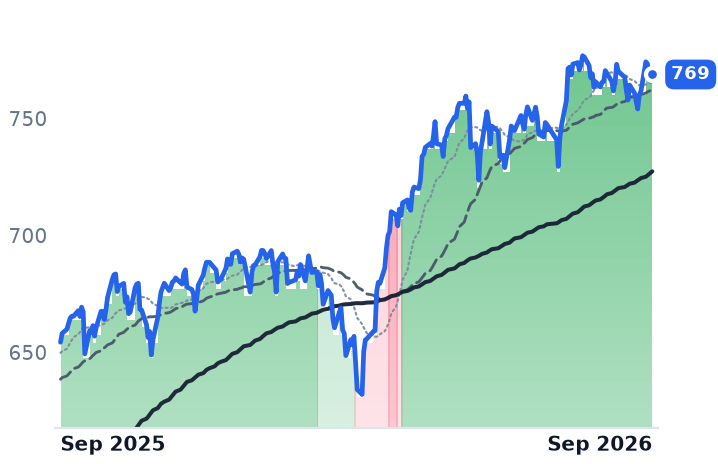
This was not a burger-specific month. Over the same thirty days Texas Roadhouse fell 20.6%, Chipotle 16.6%, Domino's 16.5% and Yum Brands 12.9% while the S&P 500 tracker rose 0.4%. McDonald's 11.9% decline was the mildest in the complex.
The verdict
At 19.2x trailing and 18.3x forward earnings on consensus 2026 earnings per share of $12.91, McDonald's has given back most of a multiple that stood at 22.2x on 18 August and near 26x a year ago — with reported earnings still growing, June-quarter net income up 4.8%. Until 23 September that gap looked like sentiment. The investor update closed it: the franchisor has agreed to fund the operator's fix out of the highest-margin line it owns, and analysts flagged that rent relief may more than offset the general and administrative savings in 2028 through 2030 estimates. What nothing yet explains is consensus, which still has 2026 earnings up 6.4% and 2027 up 7.9%. One of those two readings has to move.
Chief executive Chris Kempczinski, on CNBC's "Squawk on the Street" on 23 September, declined to forecast a recovery: "We're not expecting that the industry all of a sudden is going to go to having robust traffic growth. We think that's going to be largely flat. We do think inflation is going to be with us for, unfortunately, I think many more years at an elevated level." He added that the industry should stop calling it a difficult environment and accept that it is the environment. A company whose entire appeal is being what people buy when money is tight has just conceded it must pay its own operators to keep serving them.