

Waste Management Hauled 1.8% Less and Generated 34.5% More Free Cash Flow
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A hauler whose margins, cash flow and leverage all improved in the June quarter has spent two months being sold, and nothing in its filings explains it. Waste Management trimmed its 2026 revenue outlook in late July because it expects less tonnage, held its profit guidance anyway, and lifted its margin target to 31.0-31.2%.
Price and volume are separate meters in this business: core price ran 5.7% last quarter while collection and disposal volume shrank, and operating margin still widened to 18.7%. Consensus 2026 earnings of $8.11 a share sit 19% above what the company reported for 2024, yet the stock is unchanged across those two years — the move is entirely a lower multiple, now 25.5x forward.
The group does not split evenly. Republic Services, which raised guidance in August, has barely de-rated. Casella, whose operating income fell 22.4%, has earned its decline.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
WM | Waste Management | Residential & Commercial Collection | 🔴 Cont. Bear | −6.0% | −3.6% |
RSG | Republic Services | Residential & Commercial Collection | 🌱 Emerging Bull | −4.0% | −5.6% |
CWST | Casella Waste Systems | Residential & Commercial Collection | 🌱 Emerging Bull | −11.6% | −6.8% |
| Compared against · context, not the story | |||||
WCN | Waste Connections | Residential & Commercial Collection | 🌱 Emerging Bull | −6.7% | −8.5% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.4% | +17.5% |
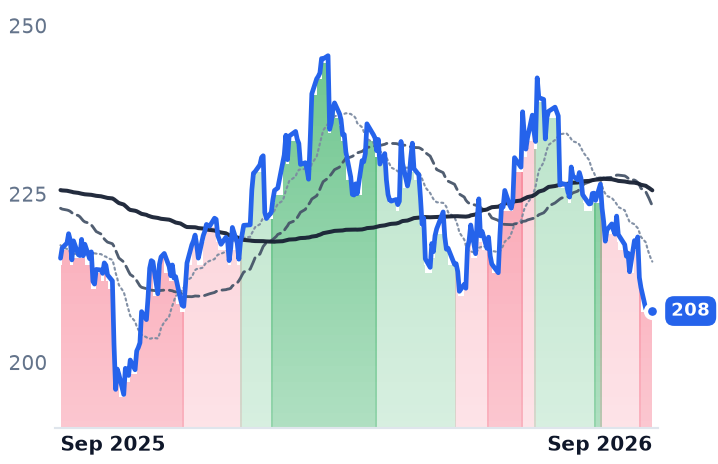
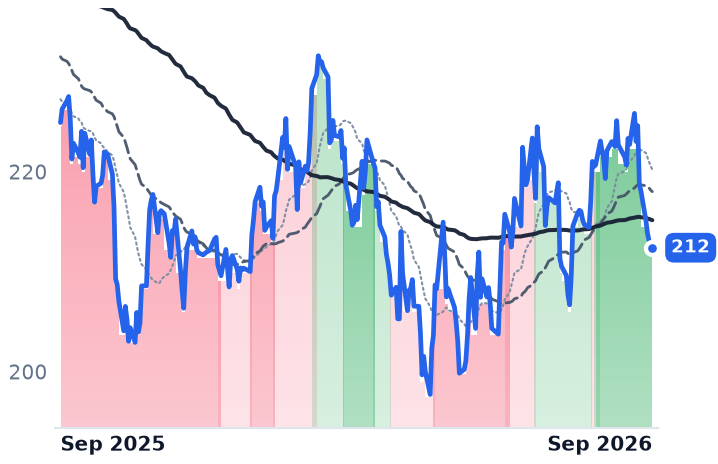
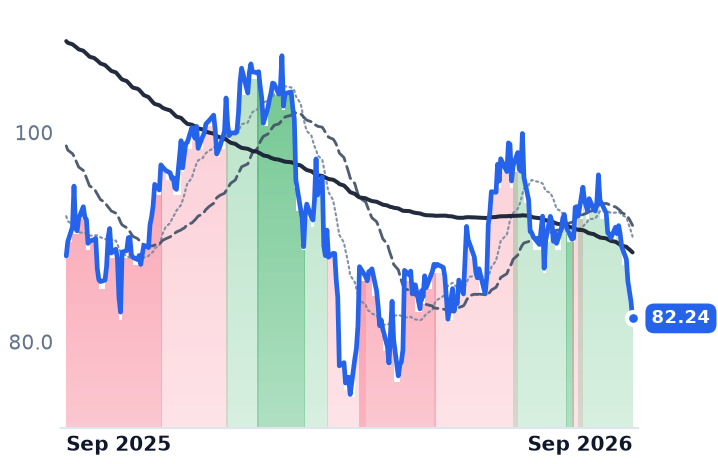
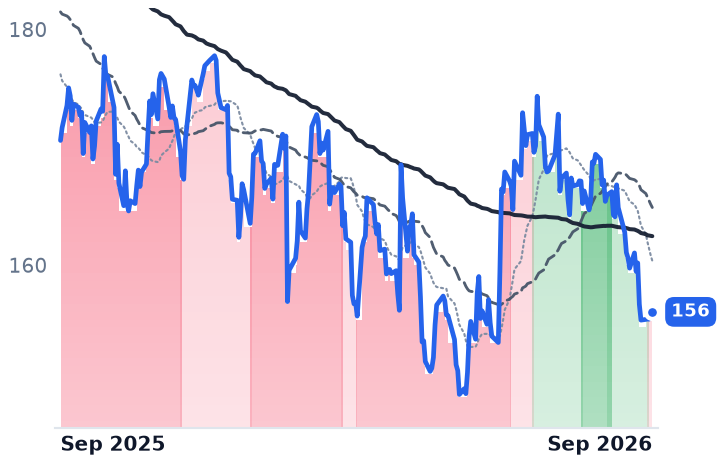
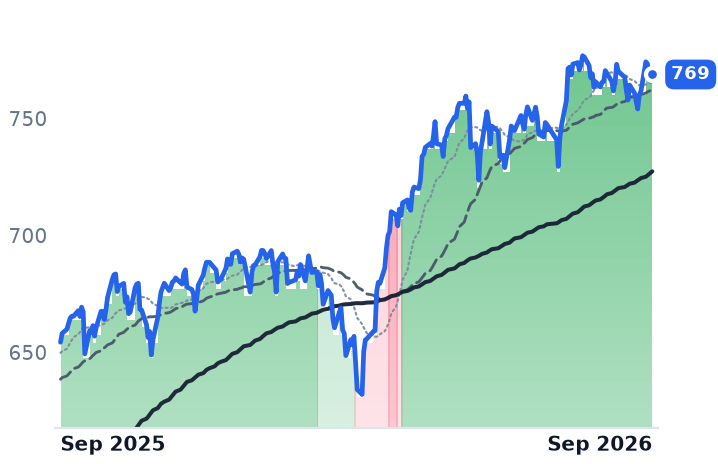
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WM | $82.7B | 29.2x | 25.5x | 3.2x | 3.1x | 9.2x | 8.9x | 14.0x | 4.3% |
RSG | $65.3B | 30.0x | 29.2x | 3.9x | 3.8x | 9.9x | 9.7x | 14.1x | 5.2% |
CWST | $5.2B | 882.4x | 61.5x | 2.6x | 2.5x | 10.4x | 9.7x | 15.9x | 2.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WCN | $39.2B | 37.6x | 27.7x | 4.0x | 3.9x | 10.2x | 10.0x | 15.7x | 4.6% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
WM | Revenue | +4.3% | +5.4% | +4.7% |
| EPS | +8.1% | +11.8% | +9.3% | |
RSG | Revenue | +3.7% | +4.7% | +4.6% |
| EPS | +5.6% | +11.1% | +10.2% | |
CWST | Revenue | +14.3% | +7.2% | +7.5% |
| EPS | +11.8% | +20.2% | +19.3% | |
WCN | Revenue | +4.8% | +5.5% | +4.9% |
| EPS | +8.4% | +9.7% | +9.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Waste Management told investors in late July that it would collect less waste this year than it had planned to, and make more money doing it. The company, which hauls household, commercial and industrial refuse to transfer stations and landfills it owns, cut its 2026 revenue outlook to $26.275-26.475bn on a roughly $250m shortfall in collection and disposal work, held adjusted earnings before interest, taxes, depreciation and amortization guidance at $8.15-8.25bn, and raised its margin target to 31.0-31.2%.
That trade — tonnage for price — is the whole equity case for the business, and it has stopped being paid for. Waste Management closed at $207.63 on 25 September against $207.69 exactly two years earlier, while consensus 2026 earnings of $8.11 a share now sit 19% above the $6.81 it reported for 2024. Nothing in the operating record explains a flat two years; a lower multiple, 25.5x forward against 29.2x trailing, does all of the work.
Two meters, pointing apart
A collection dollar is billed per lift and per ton, not per unit of economic activity, so price and volume move independently. In the June quarter core price was 5.7% and collection-and-disposal yield 3.6%, against volume down 1.8% — down 0.4% excluding prior-year wildfire cleanup — with full-year volumes guided toward a decline of about 1% on the same basis. "Volumes were softer than we anticipated," John Morris, the president and incoming chief executive, told investors on the 29 July call, noting residential volumes down 2.9%, partly from continued shedding of lower-margin contracts.
The result was operating margin of 18.7% against 18.5% a year earlier, revenue up 4.0%, and free cash flow of $1.10bn, up 34.5%. Healthcare Solutions, the segment built on the $7.2bn Stericycle purchase, lifted its adjusted EBITDA margin to 19% from 17% and has produced $32m of annualized cross-selling EBITDA; leverage is back to 2.96x, inside the company's target range. The renewable natural gas program is the one growth line management does not price — some $600m of planned 2026 EBITDA billed at gas and credit values that fell this year, prompting executives to defer selling some credits into the fourth quarter.
What the escalators do next
Republic Services, which collects and disposes of non-hazardous solid waste across 41 states, discloses the contract machinery most plainly. Just under 20% of its restricted book is indexed to headline consumer price inflation and about 35% to other indices, with roughly a 12-month lag — so billed increases step down a year after inflation does. It shows up as open-market pricing of 7.8% against restricted pricing of 4.1%. "We're always going to take price over volume," chief executive Jon Vander Ark said on the 6 August call, with residential volumes down 4.3%. Republic raised full-year guidance that day, helped by lifting its recycled-commodity assumption to about $135 a ton. Its shares carry 29.2x forward earnings against 30.0x trailing and a 5.2% free-cash-flow yield: barely a de-rating at all, on 5.6% expected earnings growth.
Casella Waste Systems, the northeastern collector and landfill owner roughly one-sixteenth Waste Management's size, is the opposite case. Revenue rose 16.9% last quarter on five acquisitions adding some $165m of annualized revenue, while operating income fell 22.4% and net leverage sits at 2.7x. It trades on the highest enterprise value to EBITDA of the four listed collection names, 15.9x, at a 2.1% free-cash-flow yield against Waste Management's 4.3%, and BofA Securities cut it to Underperform with a price target of $81 on 23 September.
The verdict
One chart, three situations. Casella's decline is operating deterioration and the market has read it correctly. Republic's multiple has scarcely moved, so calling the whole group de-rated overstates it. Only Waste Management shows margins, cash and leverage all improving into a falling share price, with no downgrade wave behind it — UBS lifted its target to $270. The likelier reading is rate competition: a mid-single-digit free-cash-flow yield behaves like a bond substitute when long-dated Treasury yields hold at levels unseen since 2006. What investors will no longer pay a premium for is the price-over-volume trade itself — they are marking the risk that indexed escalators reset lower while tonnage keeps shrinking, and price stops covering the gap.
The executive who called the volumes soft takes over as chief executive on 4 January, with a single quarterly print between now and then to show that the softness was the shedding and not the economy.