

BWX Technologies Raised Its 2026 Guidance; Centrus Sold 23% Fewer Enrichment Units
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Everything filed under "nuclear fuel cycle" fell together over six months while the fuel itself went the other way: the long-term uranium contract price reached a nominal record near $96 a pound in September, above a spot price around $90. Inside the decline, the three businesses split three ways.
BWX Technologies, paid for naval reactors under long-cycle Navy contracts, grew June-quarter revenue 18% and lifted all four of its 2026 guidance lines. Centrus Energy, paid per separative work unit, sold 23% fewer of them and watched operating income fall 69%. Cameco's pounds improved — it raised realised-price guidance — but its 49%-owned Westinghouse swung to a $10m loss on Cameco's share.
Regulated utilities fell nearly as hard over the same thirty days, so the recent leg is largely a rates move. What is genuinely nuclear-specific is narrower than the grouping implies.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
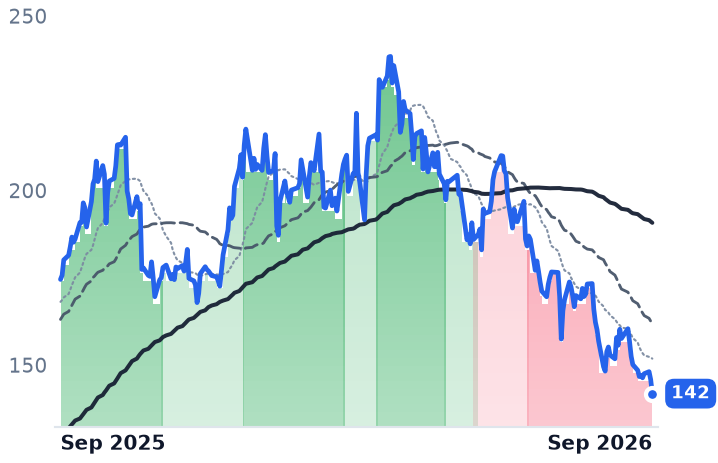
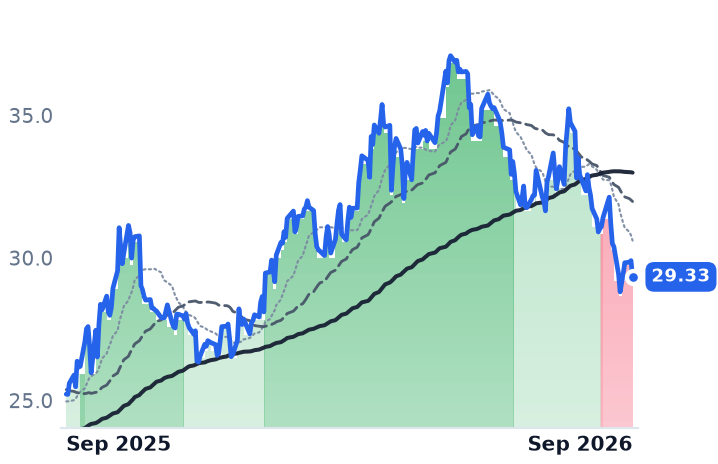
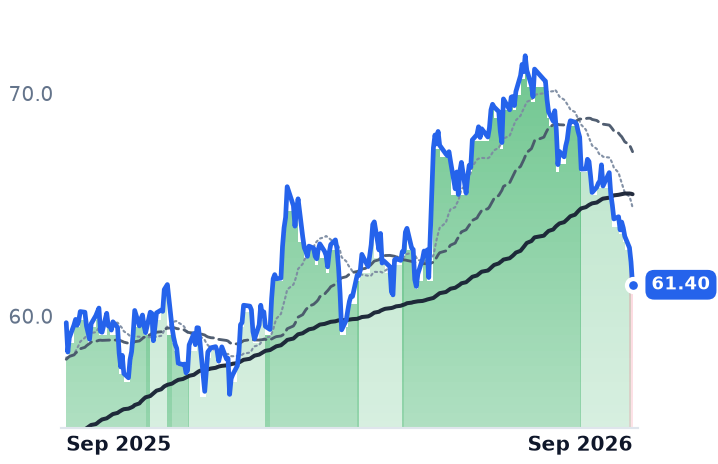
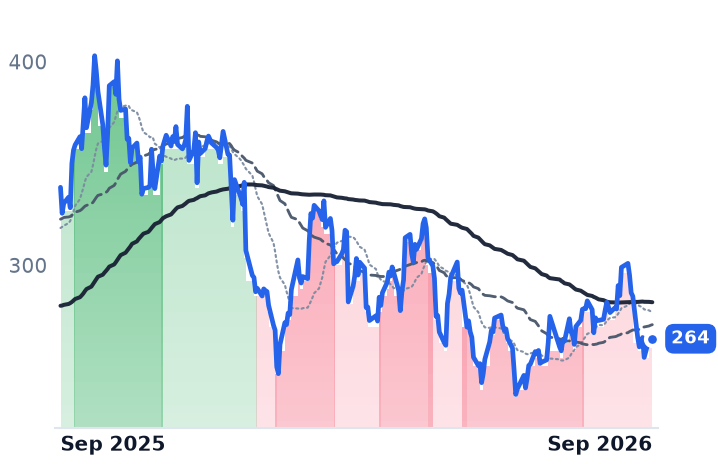
BWXT | BWX Technologies | Naval & Shipbuilding | 🔴 Cont. Bear | −4.4% | −18.7% |
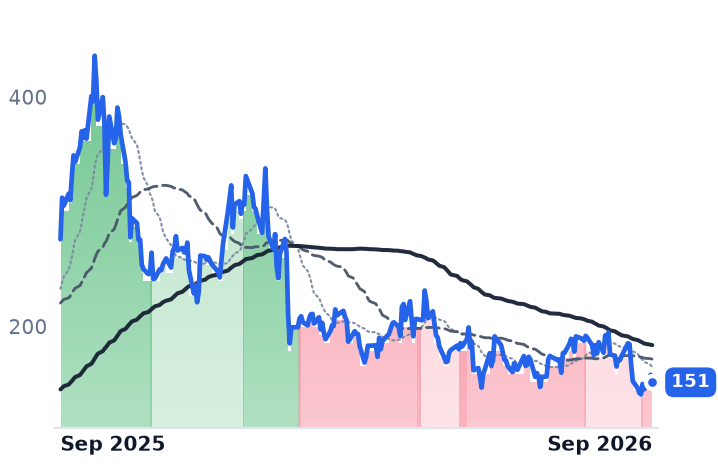
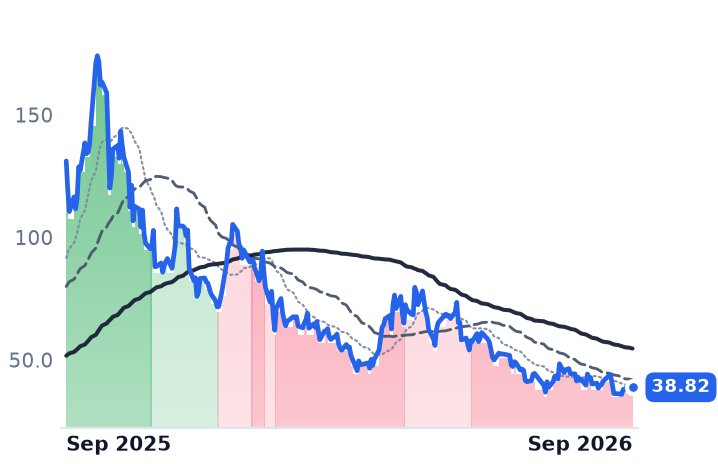
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −21.3% | −45.2% |
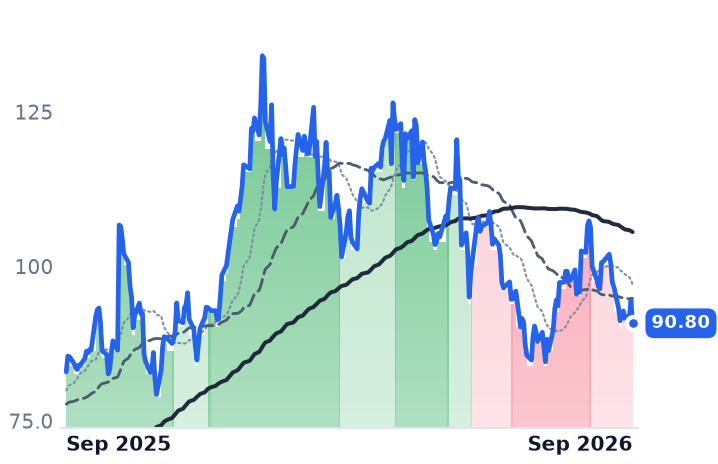
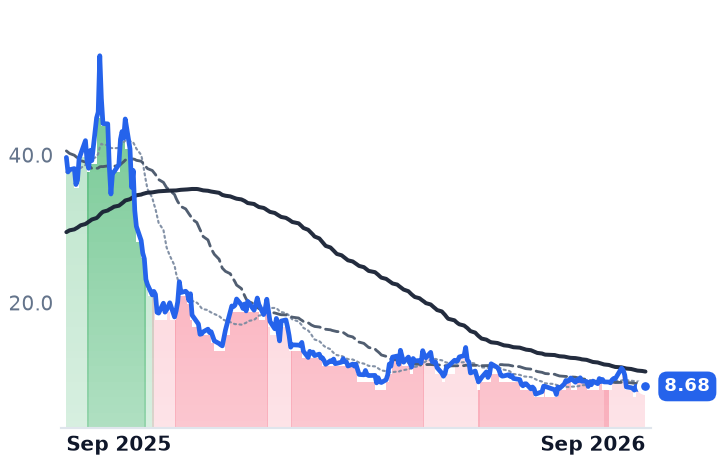
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −14.8% | +9.5% |
| Compared against · context, not the story | |||||
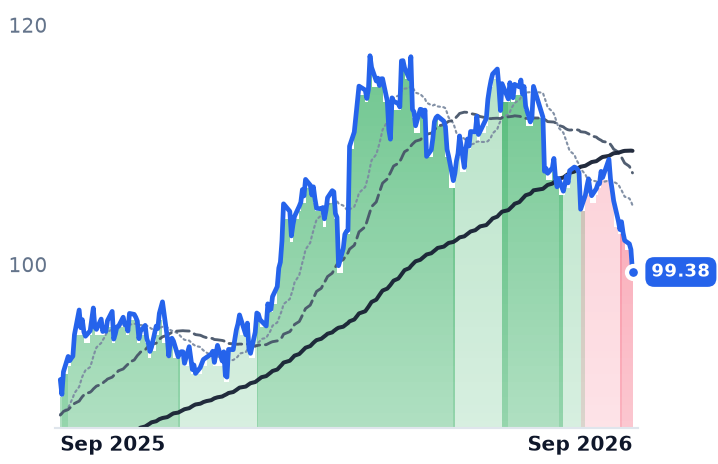
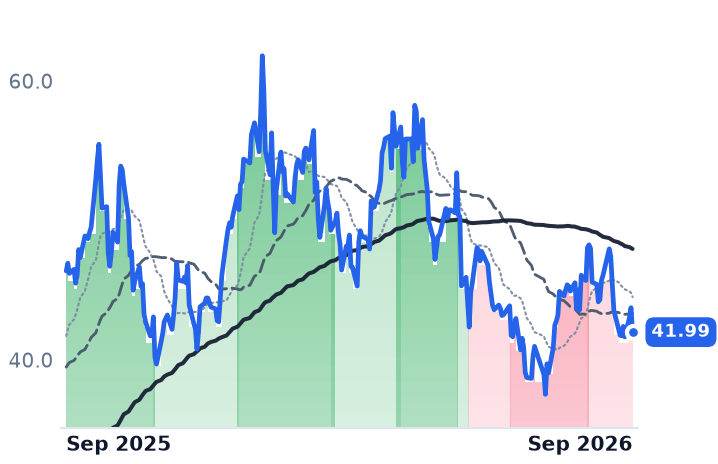
BN | Brookfield | Real Estate & Infrastructure | 🔴 Cont. Bear | −11.8% | −19.9% |
BEP | Brookfield Renewable Partners | Diversified Renewable Generators | ⚠️ Emerging Bear | −10.9% | +16.3% |
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −8.4% | +2.9% |
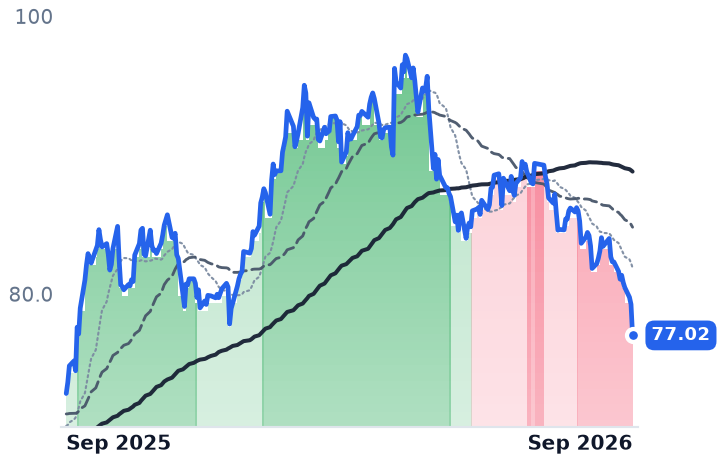
ETR | Entergy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −6.7% | +9.9% |
NEE | NextEra Energy | Vertically Integrated Utilities | 🔴 Cont. Bear | −8.8% | +5.7% |
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | −5.1% | −22.0% |
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −12.3% | −70.4% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | −10.9% | −78.1% |
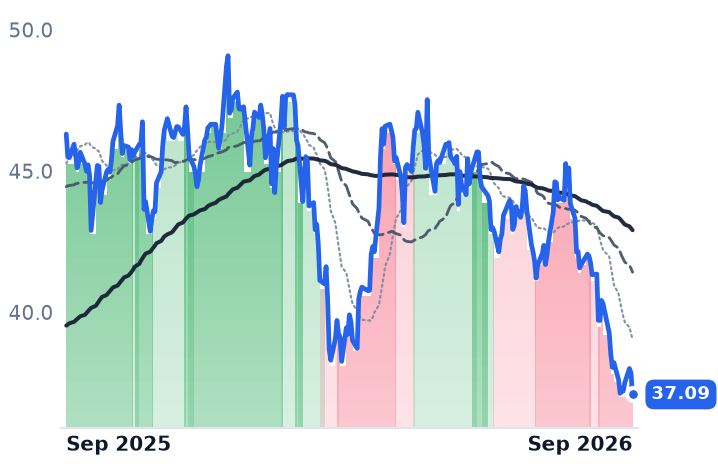
URA | Global X - Uranium ETF | Asset Management | 🔴 Cont. Bear | −12.6% | −9.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $13.0B | 36.5x | 29.9x | 3.7x | 3.4x | 16.8x | 15.5x | 26.0x | 2.4% |
LEU | $2.9B | 60.3x | 59.4x | 6.1x | 6.1x | 26.0x | 26.2x | 29.9x | -7.7% |
CCJ | $39.5B | 156.6x | 60.9x | 16.0x | 11.4x | 58.2x | 41.3x | 64.5x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BN | $85.4B | 68.1x | 13.8x | 1.1x | 11.3x | 3.8x | 39.1x | 10.0x | -9.7% |
BEP | $9.1B | 64.8x | — | 1.4x | 1.4x | 5.9x | 5.6x | 9.7x | -51.7% |
D | $55.1B | 21.7x | 17.5x | 3.0x | 3.0x | 6.1x | 6.1x | 14.7x | -12.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETR | $47.3B | 25.6x | 23.0x | 3.5x | 3.4x | 9.0x | 8.7x | 14.0x | -6.7% |
NEE | $165.4B | 17.7x | 19.7x | 5.7x | 5.3x | 7.9x | 7.4x | 15.4x | -6.2% |
CEG | $94.6B | 25.6x | 21.8x | 3.0x | 2.8x | 3.2x | 3.0x | 13.9x | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKLO | $6.9B | n/m | — | — | — | — | — | n/m | -4.0% |
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
URA | $3.9B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWXT | Revenue | +20.6% | +9.8% | +7.3% |
| EPS | +24.1% | +11.5% | +11.8% | |
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.2% | +13.2% | −23.3% | |
CCJ | Revenue | +1.3% | +12.3% | +8.4% |
| EPS | +3.8% | +70.4% | +24.8% | |
BN | Revenue | −7.3% | +23.6% | +22.3% |
| EPS | +14.3% | +23.1% | +12.0% | |
BEP | Revenue | +3.9% | +7.6% | −11.5% |
| EPS | +5.7% | −20.9% | −6.6% | |
D | Revenue | +13.9% | +6.6% | +5.9% |
| EPS | +5.0% | +6.3% | +7.0% | |
ETR | Revenue | +8.6% | +9.8% | +9.8% |
| EPS | +12.3% | +16.1% | +13.6% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.1% | +8.5% | |
CEG | Revenue | +36.6% | +2.7% | +5.5% |
| EPS | +28.9% | +10.4% | +26.4% | |
OKLO | Revenue | — | +252.7% | +552.9% |
| EPS | +57.1% | +9.6% | +13.5% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
BWX Technologies ended June with $8.4bn of orders on its books, up 40% from a year earlier, and a month later raised every line of its 2026 outlook. "We had strong second quarter 2026 results that were ahead of our expectations," said Rex D. Geveden, president and chief executive, on 3 August, lifting adjusted EBITDA guidance to $662m-$672m, earnings to $4.70-$4.80 a share and free cash flow to $345m-$360m. The shares are down 31% over ninety days.
That is the problem with the label. Three companies sit under one nuclear-fuel-cycle heading and are paid in three unrelated ways — by billable progress against a defence book, by the unit of enrichment work, and by the pound of uranium under contracts written years in advance. Only one of the three has a business that actually deteriorated, and it is not the one the fuel price would predict.
Paid by the Navy
Roughly three-quarters of BWXT's revenue comes from its Government Operations segment — about $2.35bn in 2025 against roughly $853m commercial — making precision naval propulsion reactors and components as a security-cleared sole-source supplier. June-quarter revenue rose 18% to $901.6m, but reported operating income fell 12.2%, the fourth straight quarter of that pattern, with gross margin down to 22.4% from 25.1%. The mix explains it: commercial work, grown largely by acquisition, carries an 8.0% operating margin, and management guided Government Operations to high-single-digit revenue growth rather than low teens because cost-reimbursable naval contracts book less revenue when costs fall — while raising that segment's margin target to about 20.5%. The company also agreed on 31 July to sell its medical isotope business to Nordic Capital in a deal valued at up to $800m, and the US Army picked its BANR design in late August for the Janus microreactor program, worth up to $2.2bn across five vendors. Consensus 2026 earnings went up during the decline, to $4.74 a share. The stock trades at 29.9x forward earnings against roughly 47x in May, and 16.8x trailing gross profit against 25.9x in February — on gross profit that grew.
Paid by the separative work unit
Centrus Energy, with 467 employees, is the only US-based producer of high-assay low-enriched fuel and sells enrichment services to utilities. Here the physical meter genuinely contracted: the volume of separative work units sold fell 23% year over year, with average unit cost up 13%. Revenue still rose 14% to $176.1m on uranium resales, but operating income fell 69% to $10.4m and gross margin compressed to 28.3% from 34.9%. "This was another strong quarter of financial and operational progress," chief executive Amir Vexler said on 5 August, citing commercial wins and a contingent enrichment backlog grown to $3.0bn. On 9 September the company priced $500m of stock and warrants, the common warrants covering 6,992,382 shares. Consensus has 2026 earnings at $2.55 a share against $3.90 in 2025 — roughly a third lower — and the stock trades at 59.4x forward earnings versus 60.3x trailing: no growth priced at all. Urenco announced a roughly 50% expansion of the largest US commercial enrichment plant in June, which dates the scarcity.
Paid by the pound
Cameco's uranium book improved. It realised US$67.79 a pound in the June quarter against a spot indicator near US$89.50, and lifted 2026 realised-price guidance to C$91.00-96.00 from C$85.00-89.00, with production held at 19.5-21.5 million pounds. "The long-term uranium price strengthened further, supported by increased on and off-market contracting activity," chief executive Tim Gitzel said on 30 July. Reported net income still fell 92% to $25.2m, because the damage sits in the reactor affiliate: Westinghouse, 49%-owned, swung from a $126m contribution to a $10m loss on Cameco's share as the Czech Dukovany construction contribution lapped, and is guided to a full-year net result between a $75m loss and a $10m loss. Cameco now trades at 58.2x trailing gross profit against 38.3x in May — dearer after a 21% fall in market value, because profit shrank faster than price.
What the rest of the complex did
The thirty-day leg is mostly not a nuclear story. The 30-year Treasury yield sat near 5.3-5.4% in late September, its highest in about two decades, and regulated utilities fell almost as hard as the nuclear names — NextEra down 8.4%, Dominion 7.8%, Entergy 6.1% — after the sector gave back an early-year gain of more than 11% to finish among the worst of the eleven main industry groups. The pre-revenue reactor developers took it worst: Oklo down 73% and NuScale 79% over twelve months, against BWXT's 20%.
So the verdict divides cleanly. The fuel meter is not deteriorating — term uranium reached roughly US$96 a pound in September on Kazakh supply constraints, a nominal record, some $6 above spot. Centrus's decline is earned: fewer units sold, thinner margins, dilution, and a flat trailing-to-forward multiple on falling earnings. Cameco's is half-earned, concentrated in Westinghouse rather than in pounds, and its valuation has not yet done its work. BWXT's is the one nothing in the reported numbers explains, beyond a discount rate applied to payoffs dated 2028 and later and a margin line that has ground down for four quarters.
The tightest constraint is a calendar, not a price. Waivers permitting Russian enriched uranium into the United States all terminate by 1 January 2028, and Centrus's own centrifuges at Piketon are not scheduled to produce commercially until 2029.