

Danaher's Bioprocessing Orders Grew Mid-Teens While $100m of Resin Slid Into 2027
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The part of the laboratory-supply recovery that was supposed to arrive first is arriving last. Danaher's Cytiva franchise sells the resins, filters and single-use bags consumed per batch of biologic drug made — an annuity metered to production volumes — and it grew low single digits last quarter, with consumables no faster than equipment, after customers asked for shipments to land when their plants are ready.
What is inflecting is order books and instrument placements: Waters' legacy instruments grew 8% in constant currency and Mettler-Toledo raised full-year local-currency guidance to about 4-5% on pharmaceutical reshoring inquiries. Capital spending came back before consumption did.
The market has already paid for the sequel. Danaher trades at 26.1 times forward earnings against 22.3 times a year ago — the re-rating arrived within ten weeks of a guidance cut, and before the revenue that justifies it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
DHR | Danaher | Life Sciences Instruments & Consumables | 🟢 Cont. Bull | +3.0% | +17.4% |
WAT | Waters | Life Sciences Instruments & Consumables | 🟢 Cont. Bull | +2.4% | +40.6% |
MTD | Mettler-Toledo International | Life Sciences Instruments & Consumables | 🟢 Cont. Bull | +6.7% | +18.7% |
| Compared against · context, not the story | |||||
TMO | Thermo Fisher Scientific | Life Sciences Instruments & Consumables | 🟢 Cont. Bull | +5.8% | +41.9% |
RVTY | Revvity | Life Sciences Instruments & Consumables | 🟢 Cont. Bull | +15.5% | +66.2% |
A | Agilent Technologies | Life Sciences Instruments & Consumables | 🟢 Cont. Bull | +7.7% | +32.1% |
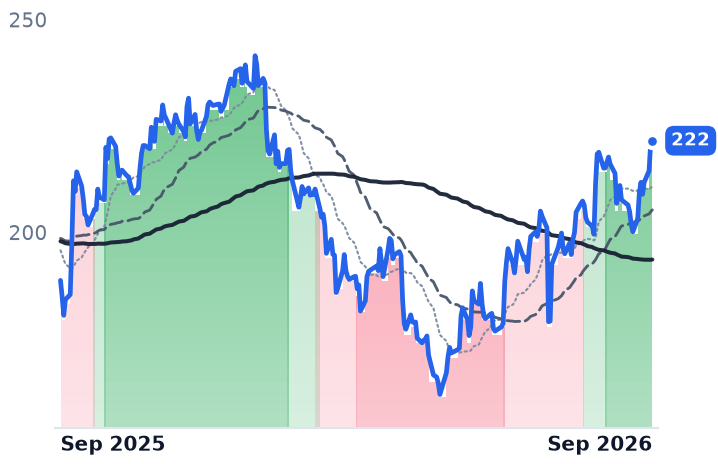
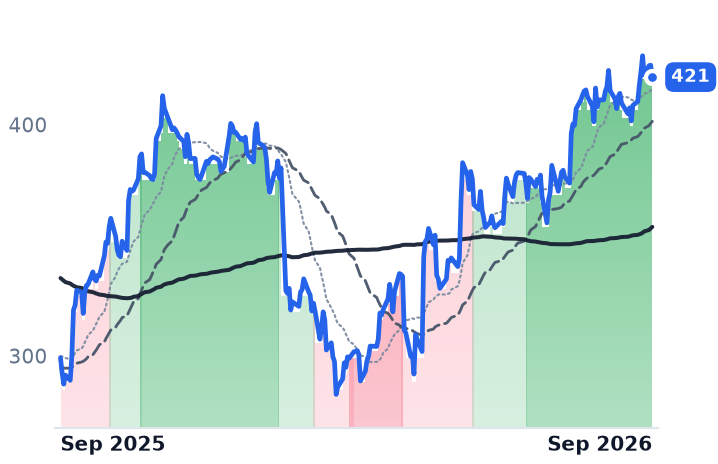
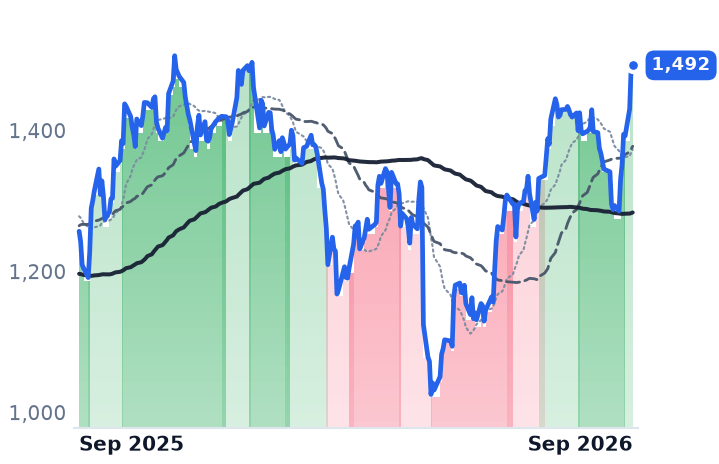
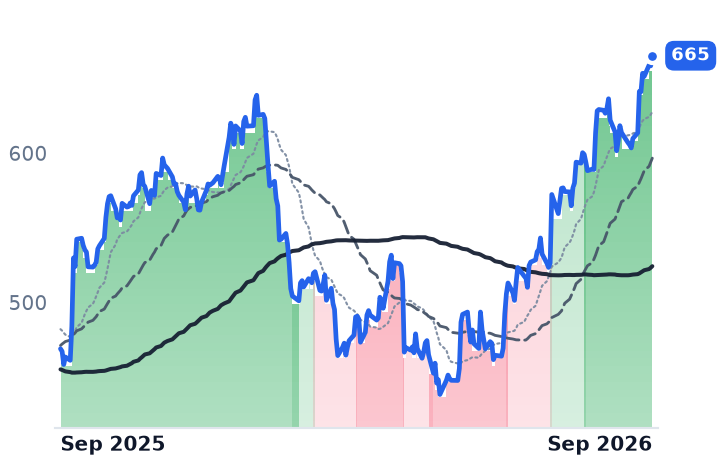
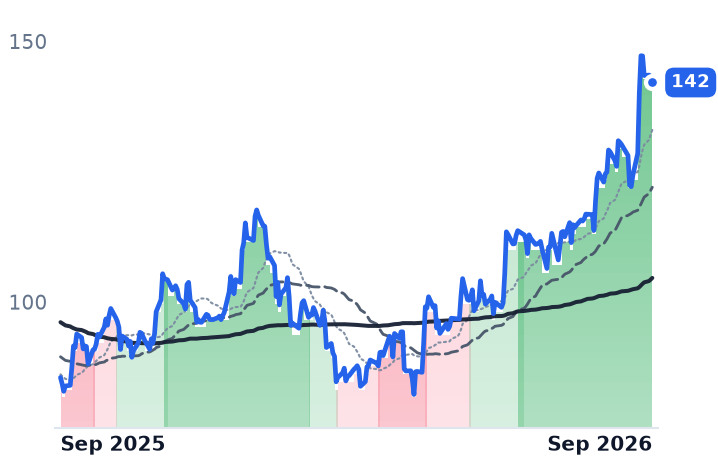
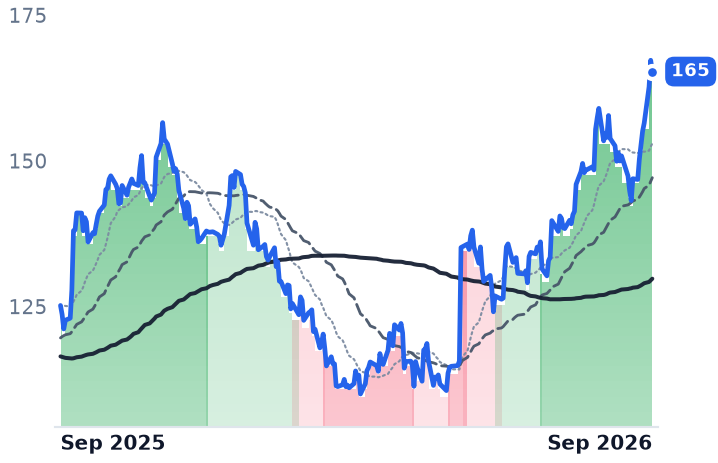
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DHR | $155.9B | 39.2x | 26.1x | 6.2x | 5.9x | 10.6x | 10.1x | 24.9x | 3.5% |
WAT | $41.3B | 104.6x | 28.9x | 8.9x | 6.4x | 17.5x | 12.6x | 51.4x | 1.0% |
MTD | $30.2B | 33.5x | 31.5x | 7.3x | 7.1x | 12.5x | 12.2x | 24.7x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TMO | $162.9B | 23.8x | 17.6x | 3.6x | 3.4x | 9.1x | 8.7x | 18.2x | 4.1% |
RVTY | $10.5B | 43.6x | 17.9x | 3.6x | 3.7x | 7.0x | 7.2x | 16.8x | 4.7% |
A | $31.6B | 24.5x | 18.7x | 4.5x | 4.3x | 8.6x | 8.2x | 18.2x | 3.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DHR | Revenue | +7.3% | +8.0% | +6.6% |
| EPS | +10.0% | +9.3% | +9.9% | |
WAT | Revenue | +104.2% | +10.4% | +5.9% |
| EPS | +11.1% | +13.2% | +11.5% | |
MTD | Revenue | +5.9% | +4.7% | +5.2% |
| EPS | +12.2% | +9.1% | +11.3% | |
TMO | Revenue | +7.9% | +5.5% | +6.3% |
| EPS | +9.3% | +9.5% | +10.3% | |
RVTY | Revenue | −0.2% | +5.3% | +6.3% |
| EPS | +6.4% | +10.8% | +10.7% | |
A | Revenue | +6.9% | +6.1% | +6.7% |
| EPS | +7.2% | +10.1% | +11.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Danaher's order book has turned, and its revenue line has not yet agreed. In the second quarter the bioprocessing business inside its Biotechnology segment — Cytiva, which sells the chromatography resins, filters and single-use bags consumed per batch of biologic drug manufactured — booked mid-teens order growth while core revenue there grew only low single digits, with consumables no faster than equipment. Roughly $50-60m of resin shipments slipped out of the quarter and more than $100m out of 2026 into 2027 at commercial customers' request, on when their plants would be ready to receive it.
That sequence matters because it is backwards from the way this recovery was supposed to run. The consumables annuity — three-quarters of Danaher's revenue is recurring, and recurring revenue typically runs two to five times instrument revenue over an installed base's life — is metered to other companies' production volumes and should move before anyone signs a capital budget. Instead the capital budgets moved first.
The meters read capex
Waters, which sells liquid chromatography and mass-spectrometry systems plus the columns and service contracts consumed on them, is the cleanest read. Its legacy Analytical Sciences division grew 9% in constant currency, and instruments grew 8% against chemistry consumables at 10% and service at 9% — placements recovering alongside consumption rather than trailing it. Waters raised organic growth guidance to 6.5-8.0% and adjusted earnings to $14.40-$14.60 a share. "With momentum building across our portfolio, end markets, and synergies, we are raising every component of our full-year 2026 guidance," chief executive Udit Batra said on August 4. Its reported figures are unreadable without adjustment: the $18.8bn combination with BD's Biosciences and Diagnostic Solutions businesses closed on February 9, leaving BD holders with 39.2% of the company, and the resulting purchase accounting makes trailing earnings meaningless. Forward, the shares fetch 28.9 times earnings against 22.8 times a year ago. Integration is running ahead of plan, with $75m of savings banked toward a $200m run-rate.
Mettler-Toledo is nearly pure instrument capital spending — laboratory balances, titrators, process analytics — and it is accelerating where Danaher deferred. Local-currency sales rose 6%, and full-year guidance went up to about 4-5%. Operating income grew 18.3% on revenue up 4.5%, with gross margin 4.2 points wider; the share count fell 2.8%, so this is operating leverage rather than buyback arithmetic. Chief executive Patrick Kaltenbach told investors on the July 30 call that with US pharmaceutical reshoring, "we see some activity there with RFQs that are related to reshoring, again, as customers are expanding manufacturing in the United States" — while cautioning it is still early innings. Laboratory demand, he said, was "a bit more modest."
What Danaher is actually owed
Danaher's quarter was $6.3bn of revenue on 3.0% core growth, with the Biotechnology segment at $1.92bn and full-year core growth guided to 3-4%. The bioprocessing outlook was cut from high- to mid-single-digit. Respiratory testing, at roughly $250m, was down about 15% and a drag rather than a crutch. "Our Life Sciences businesses delivered their strongest quarter in several years and while customer project timing impacted bioprocessing revenue, underlying order trends remained strong," chief executive Rainer Blair said on July 21.
The deferral is a timing problem, not a share problem. Cytiva holds roughly 35.7% of the Protein A affinity resin market against Merck KGaA at 16.2% and Repligen at 13.6%, and once a resin is written into a regulatory filing, switching requires revalidation. Volumes deferred are volumes owed.
The shares have already collected. Danaher fell 11.0% on July 21 and is 23.8% above that close; the six listed suppliers — Thermo Fisher, Agilent and Revvity alongside the three here — averaged under 4% over the first nine months of the past year and roughly 31% in the last ninety days, with Mettler and Waters moving from downtrends to uptrends only in June. The likelier trigger is regulatory clarity rather than a demand surprise: more than a dozen drugmakers have struck most-favored-nation pricing deals carrying three-year tariff reprieves, restoring the budget visibility that precedes capacity commitments. Biotech venture funding backs it: at least 68 companies raised more than $9.1bn in the first half, the best first half since 2022, with 76% of it in rounds of $100m or more — the mature programs that build plants.
So the businesses earn part of this. Waters earns the most of it, Mettler earns its margin expansion, and Danaher earns an order book. What nothing in the reported numbers yet earns is Danaher's move from 22.3 to 26.1 times forward earnings, or consensus pencilling 7.3% revenue growth this year against 3-4% core guided by the company. The multiple has been paid for a conversion that has not happened.
The resin is the tell. It ships when someone else's plant is ready, which means the third and fourth quarters will show whether the mid-teens orders were customers building capacity or customers rescheduling it.