

Hawaiian Electric Raised $29.5m Selling Bank Stock; Its Next Wildfire Payment Is $479m
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Only one of Hawaiian Electric's four Maui wildfire settlement payments was funded in advance, and the market has spent September pricing how the other three get paid. The company monetized part of its leftover American Savings Bank stake into the bank's initial public offering; the entire residual position is worth roughly $73.5m against an installment due next April. Management plans debt and possibly convertible debt for that one, and a mix of debt and equity thereafter.
The business underneath earns about 6.1% on equity against the 9.5% Hawaii allows, and core quarterly earnings fell to $0.13 a share from $0.20. The shares have now slipped below the roughly $10.21 of book value behind them — which makes equity the most expensive of the three ways left to pay.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
HE | Hawaiian Electric Industries | Regional/Municipal Utilities | 🔴 Cont. Bear | −17.3% | −17.8% |
| Compared against · context, not the story | |||||
EIX | Edison International | Regional/International Utilities | 🟢 Cont. Bull | −25.6% | +3.7% |
PCG | PG&E | Vertically Integrated Utilities | 🟢 Cont. Bull | −28.9% | −11.9% |
AEE | Ameren | Vertically Integrated Utilities | ⚠️ Emerging Bear | −5.1% | +2.2% |
ED | Consolidated Edison | Vertically Integrated Utilities | ⚠️ Emerging Bear | −3.6% | +8.0% |
PNW | Pinnacle West Capital | Vertically Integrated Utilities | 🟢 Cont. Bull | −4.7% | +10.1% |
XEL | Xcel Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −6.8% | +0.2% |
SO | The Southern | Vertically Integrated Utilities | ⚠️ Emerging Bear | −5.5% | −7.7% |
DUK | Duke Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −4.6% | −3.9% |
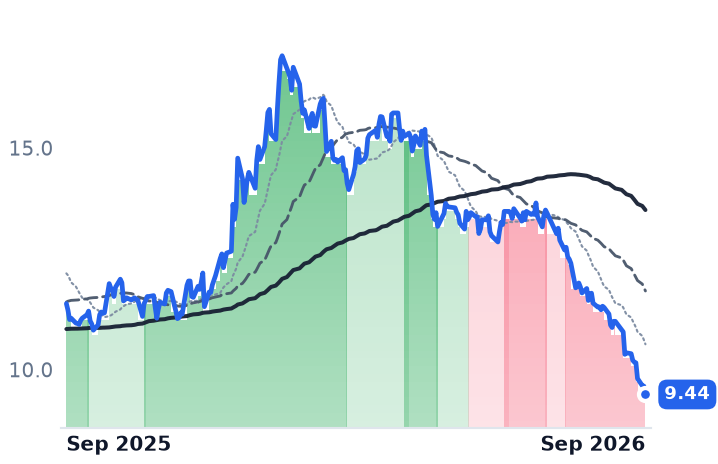
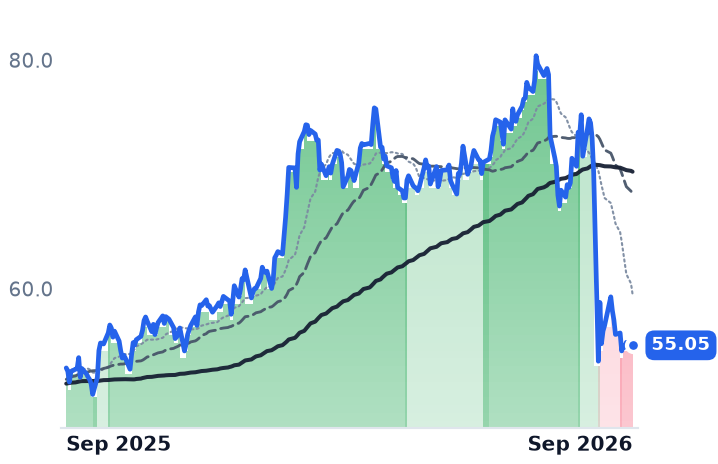
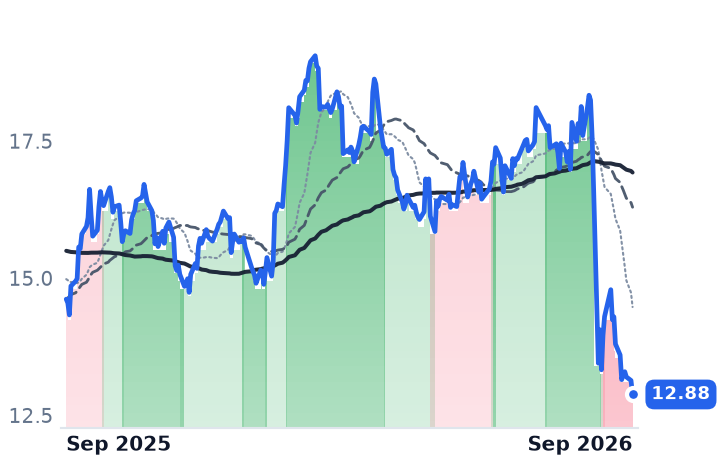
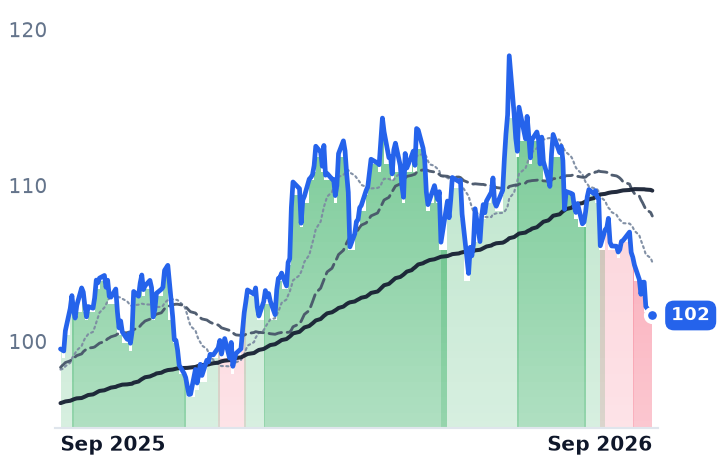
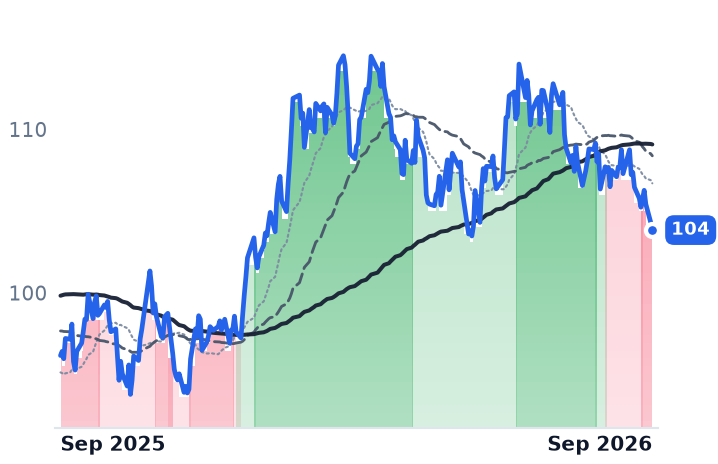
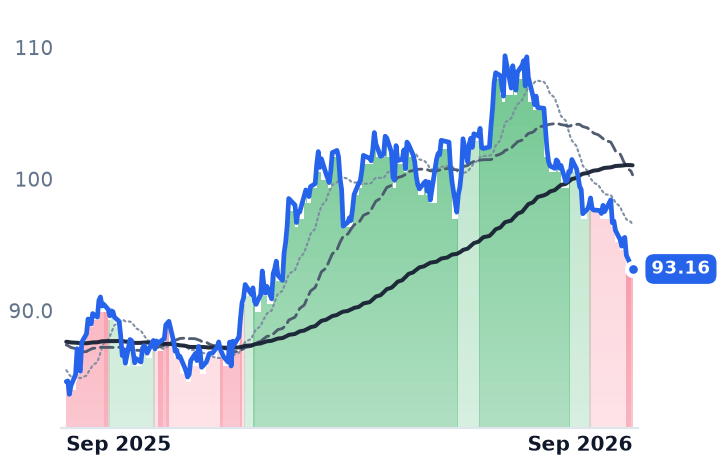
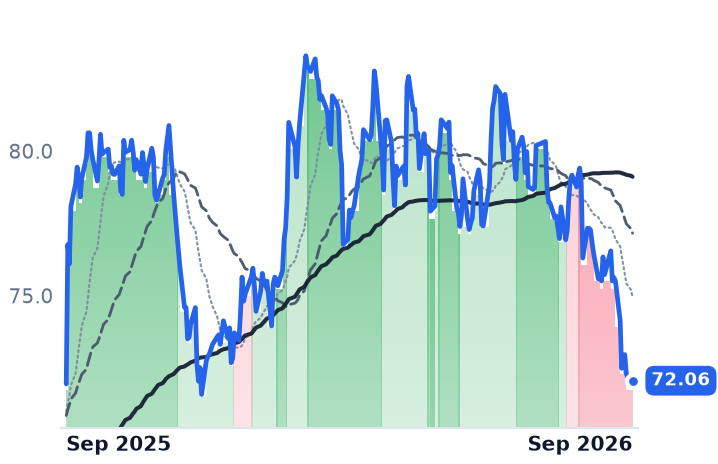
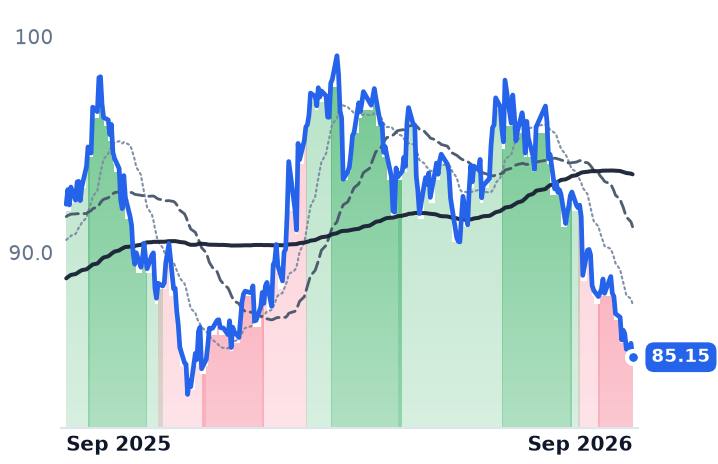
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HE | $1.6B | 7.3x | 13.6x | 0.5x | 0.5x | 4.3x | 4.5x | 4.2x | -34.7% |
EIX | $20.7B | 5.5x | 8.8x | 1.1x | 1.1x | 2.7x | 2.7x | 8.2x | -1.9% |
PCG | $37.7B | 10.2x | 8.5x | 1.5x | 1.4x | 2.6x | 2.6x | 9.6x | -11.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AEE | $27.8B | 17.5x | 18.6x | 3.2x | 3.1x | 7.7x | 7.5x | 11.8x | -5.1% |
ED | $38.8B | 17.7x | 17.3x | 2.3x | 2.2x | 3.5x | 3.4x | 9.4x | 7.2% |
PNW | $11.9B | 18.3x | 20.8x | 2.1x | 2.2x | 3.8x | 3.9x | 10.6x | -7.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
XEL | $48.6B | 23.3x | 19.0x | 3.3x | 3.1x | 17.4x | 16.2x | 13.9x | -6.7% |
SO | $106.6B | 22.2x | 20.2x | 3.5x | 3.5x | 8.1x | 8.0x | 12.7x | 2.4% |
DUK | $93.7B | 18.1x | 17.9x | 2.8x | 2.8x | 4.1x | 4.1x | 11.4x | 1.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
HE | Revenue | −15.9% | +4.6% | +4.0% |
| EPS | −23.1% | +37.9% | −9.4% | |
EIX | Revenue | +1.9% | +3.3% | +3.3% |
| EPS | +0.8% | +6.1% | +5.5% | |
PCG | Revenue | +2.8% | +3.9% | +3.9% |
| EPS | +10.1% | +9.0% | +9.2% | |
AEE | Revenue | +5.0% | +6.0% | +6.4% |
| EPS | +7.4% | +8.0% | +8.4% | |
ED | Revenue | +6.9% | +4.2% | +3.9% |
| EPS | +7.3% | +6.2% | +6.5% | |
PNW | Revenue | +3.1% | +7.3% | +5.5% |
| EPS | −5.4% | +17.5% | +10.5% | |
XEL | Revenue | +7.8% | +8.9% | +8.1% |
| EPS | +8.0% | +10.4% | +10.1% | |
SO | Revenue | +7.7% | +5.5% | +6.1% |
| EPS | +6.8% | +7.5% | +9.2% | |
DUK | Revenue | +5.8% | +4.6% | +4.2% |
| EPS | +6.3% | +6.9% | +7.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Hawaiian Electric Industries put part of its leftover stake in American Savings Bank into the Honolulu lender's initial public offering on 16 September, netting $29.5m with underwriters holding a short option on a little more.
Against what is coming, it is small change. The company paid the first of four equal $479m installments of the Maui wildfire settlement on 10 April 2026, after the judgment on subrogation claims brought by more than 200 insurers became final. Three remain, in April of 2027, 2028 and 2029. The bank position still held — 6.4%, worth about $73.5m at American Savings Bank's 18 September close and locked up for 180 days — covers roughly a sixth of one of them. The rest has to come from borrowing, from stock, or from rates.
What the utility earns
Hawaiian Electric supplies electricity to homes, resorts, military bases and farms on Oahu, Maui, Hawaii Island, Lanai and Molokai. There is no interconnection to any other grid and no wholesale rival for the load; the only competitor is the rooftop solar that Hawaii's high retail rates and its 2045 renewable mandate encourage. So the earnings question is regulatory. The Hawaii Public Utilities Commission set an allowed return on common equity of 9.5% for Oahu and shares earnings symmetrically outside a three-percentage-point band around it. The utility has been earning about 6.1%.
The reported second quarter hides that. Net income of $123.2m and diluted earnings of $0.71 a share reflect a remeasurement of the settlement liability to present value, from $1.44bn to $1.3bn, a $153.9m pre-tax benefit that unwinds over the next three years as interest accretes. On the company's own core measure, earnings were $0.13 a share against $0.20 a year earlier. Chief executive Scott Seu called 2026 "a transitional year as we prepare for our expected reset of rates in 2027" on the 7 August call.
What rates might add
That reset is filed. In July the Hawaiian Electric companies asked the commission for about $170m, or 5.3%, of additional annual revenue in two steps — roughly $125m from January 2027 and $45m a year later — worth about $11 a month on a typical Oahu residential bill. The commission has been holding statewide public hearings on it through September, in the same weeks the stock made new lows. Separately the commission approved up to $350m of wildfire-mitigation spending for 2025-2027 but barred the utility from recovering it until it rules on a securitization application the company says it will file this year, using the state law that authorizes up to $500m of resilience-cost securitization. "Securitization will allow us to implement these critical investments at the least possible cost to customers," Seu said on the same call.
Who pays the next installment
Management's plan is debt and possibly convertible debt for the April 2027 payment, and a mix of debt and equity after that depending on markets. Consolidated liquidity was $1.3bn at 30 June, but roughly $1.1bn of it is undrawn credit-facility capacity and an unissued at-the-market equity program — future borrowing and future dilution, counted as today's cushion.
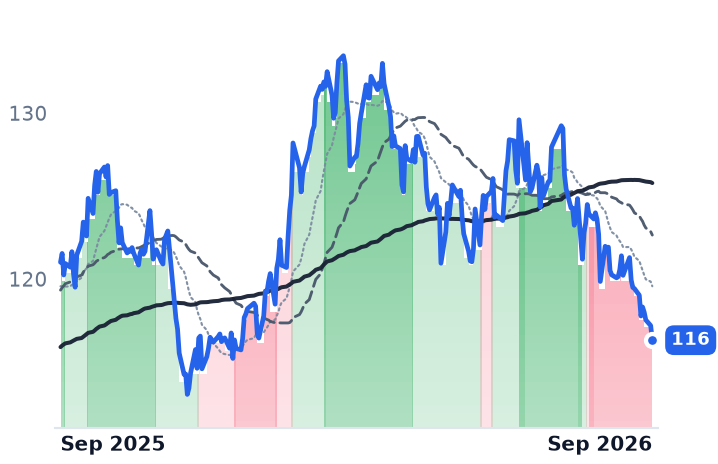
The dilution people expect has, oddly, already happened. A $558m offering at $9.25 a share in September 2024 pre-funded the first installment and took the diluted share count from 120.6m to 172.8m; it has sat near 173.2m for five quarters since. What has changed is the price of the next one. The shares fell about 16% in the month to 22 September while Ameren, Consolidated Edison, Pinnacle West, Xcel, Southern and Duke fell around 4%. Edison International and PG&E fell harder, but almost entirely in a single session on 31 August, when California lawmakers introduced a wildfire bill without the liability shield the governor had proposed; Hawaiian Electric moved 1.3% that day. This is neither a bond-yield story nor a California story.
It is a currency story. Hawaiian Electric trades at 0.92 times book value, implying about $10.21 of book behind a $9.44 share — cheaper on that basis than Edison International at 1.18 times or Ameren at 2.03 times, though Ameren earns its authorized return and Hawaiian Electric does not. The trailing price-to-earnings of 7.3 is an artifact of the remeasurement gain; on consensus 2026 earnings of $0.69 the shares are at 13.6 times, above Edison's forward 8.8. Creditors have already been repriced the other way: Moody's upgraded the utility to Ba1 in April and S&P Global to BB- in July, both still below investment grade. A liability being paid down with equity improves the bondholder's claim by construction.
The discount is rational rather than free. Below book, every dollar of settlement money raised by selling stock subtracts from the book value the regulator pays a return on, which is the whole of this company's earnings power. That is why the December interim decision on the rate request and the securitization order matter more to the equity than any quarter's earnings — and why the common dividend, suspended since the fires in 2023, stays a question for the end of the decade rather than this one.
Three payments are left. The cheaper the stock gets, the more of it each one costs.