

Meta's Muse App Repriced CBRE, JLL and Newmark as Middlemen AI Can Route Around
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Three commercial property firms whose fee revenue is accelerating were sold on 23 September because a consumer shopping app topped the US app store. Meta's personal AI agent Muse, launched 8 September, dragged every business that gets paid to stand between a client and a counterparty; Newmark fell hardest in a segment that has now lost roughly a sixth of its value in a month.
The businesses say otherwise. CBRE's Advisory unit grew second-quarter revenue 17.7% and segment operating profit 29.4%, with global leasing up 24%; Newmark's investment-sales fees rose 54.4%; JLL raised full-year adjusted earnings guidance to $24.60-$25.90 a share. Only Newmark shows a real crack — operating income down 5.5% as producer pay absorbed the revenue gain.
The market is marking terminal value, not next year's fees, and no quarterly print settles that.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
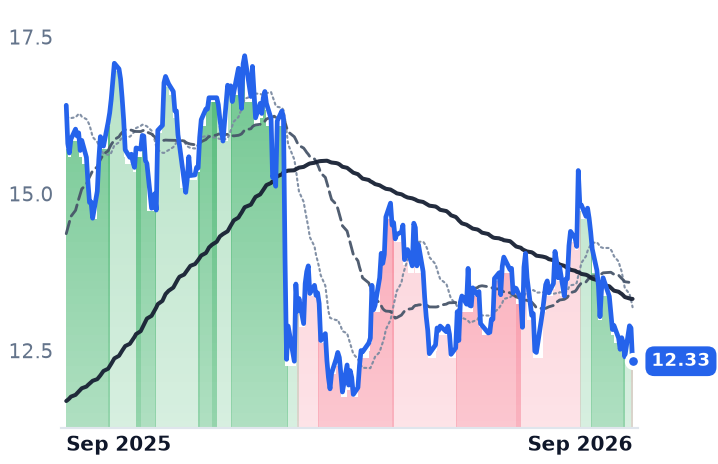
CBRE | CBRE | Commercial Real Estate Services | 🟢 Cont. Bull | −10.2% | −16.4% |
JLL | Jones Lang LaSalle Incorporated | Commercial Real Estate Services | 🟢 Cont. Bull | −16.3% | +3.5% |
NMRK | Newmark | Commercial Real Estate Services | 🔴 Cont. Bear | −18.3% | −31.6% |
| Compared against · context, not the story | |||||
CIGI | Colliers International | Commercial Real Estate Services | 🔴 Cont. Bear | −15.3% | −43.8% |
CWK | Cushman & Wakefield | Commercial Real Estate Services | ⚠️ Emerging Bear | −15.8% | −24.9% |
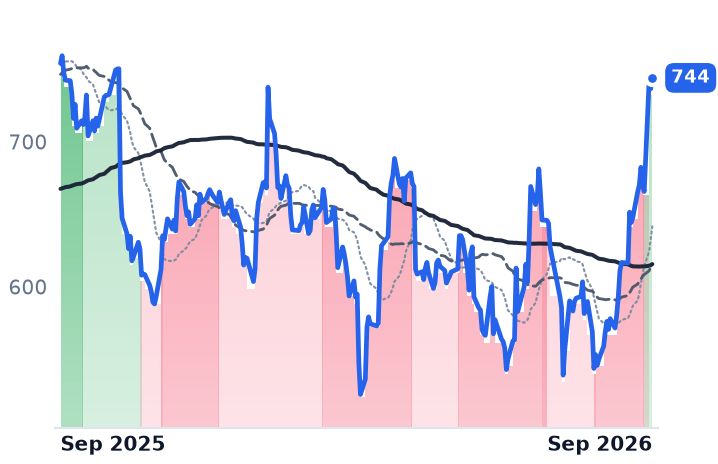
META | Meta Platforms | Social Media & Messaging | 🔴 Cont. Bear | +33.1% | −1.3% |
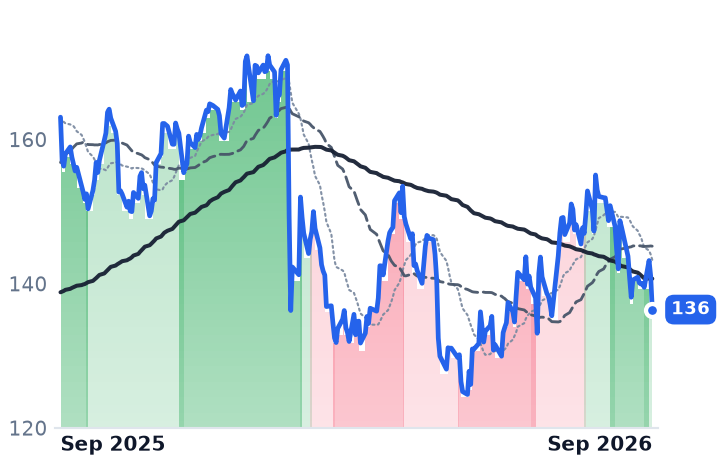
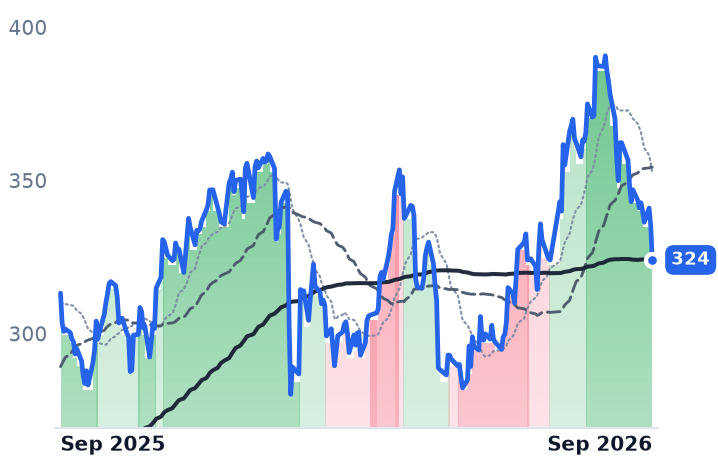
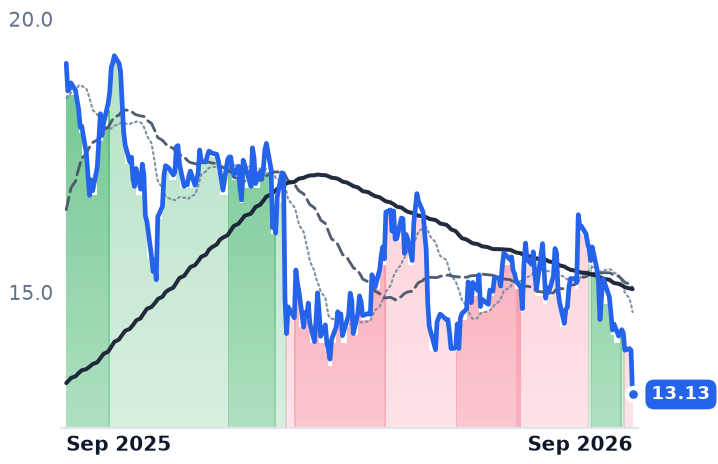
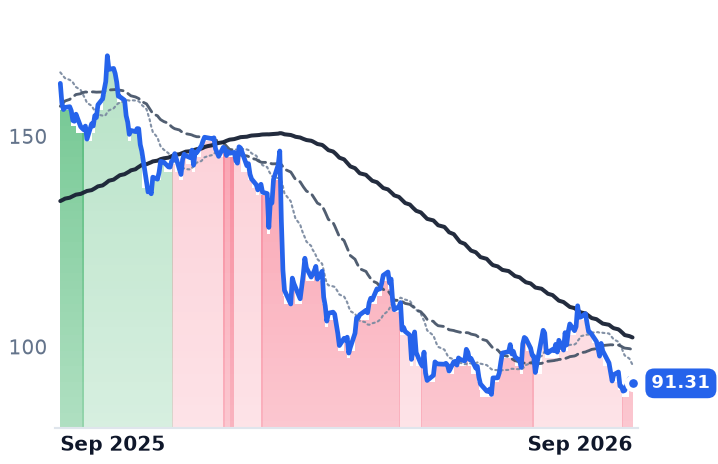
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CBRE | $39.5B | 31.1x | 17.4x | 0.9x | 0.8x | 5.1x | 4.8x | 17.9x | 2.4% |
JLL | $14.9B | 15.2x | 13.0x | 0.5x | 0.5x | 0.6x | 0.6x | 11.1x | 8.4% |
NMRK | $2.1B | 15.8x | 6.7x | 0.6x | 0.5x | 0.6x | 0.6x | 8.0x | 38.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CIGI | $4.5B | 41.5x | 11.9x | 0.7x | 0.7x | 2.7x | 2.6x | 11.1x | 4.5% |
CWK | $2.9B | 42.5x | 8.4x | 0.3x | 0.3x | 1.6x | 1.6x | 12.8x | 10.4% |
META | $1.5T | 21.5x | 18.2x | 6.5x | 5.8x | 7.9x | 7.1x | 14.7x | 2.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CBRE | Revenue | +15.4% | +11.3% | +9.7% |
| EPS | +23.7% | +14.8% | +13.0% | |
JLL | Revenue | +11.9% | +7.5% | +6.8% |
| EPS | +43.4% | +12.2% | +14.0% | |
NMRK | Revenue | +16.8% | +9.2% | +8.4% |
| EPS | +22.2% | +13.0% | +9.7% | |
CIGI | Revenue | +16.1% | +8.6% | +3.0% |
| EPS | +12.8% | +13.5% | +11.1% | |
CWK | Revenue | +58.6% | +6.5% | +6.1% |
| EPS | +20.5% | +17.4% | +15.4% | |
META | Revenue | +27.3% | +20.1% | +17.8% |
| EPS | +38.3% | +6.9% | +15.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Newmark Group brokers investment sales, arranges Fannie Mae and Freddie Mac loans and services a $219.3bn mortgage book. It sells nothing to consumers. On 23 September its shares fell 5.81% to $13.13, the worst showing in commercial real estate services, after Meta's personal AI agent Muse — released 8 September, 2.8m downloads in two weeks, top of Apple's US free-app chart — pushed investors out of anything paid to sit between a client and a counterparty. Jones Lang LaSalle, the Chicago firm that pairs global brokerage with the LaSalle investment-management arm, lost 3.37% to $324.06; CBRE Group, the Dallas-based market leader in leasing, property sales and building operations, lost 3.29% to $136.41. The S&P 500 as a whole slipped 0.7%.
That is a repricing by analogy, and it is the second one this year. On 11-12 February the same names gapped down roughly 12% to 14% in a single session, the steepest sell-off in real estate services shares since 2008. Keefe, Bruyette & Woods analyst Jade Rahmani named the mechanism then: "We believe investors are rotating out of high-fee, labor-intensive business models viewed as potentially vulnerable to AI-driven disruption." What is being marked is not next year's commissions. It is whether the commission exists in a decade.
What the fees actually did
CBRE's revenue line is a poor guide to its profits, and the hypothesis that brokerage economics are cracking dies in the segment detail. Building Operations & Experience — facilities work for corporate occupiers — booked $6,686m of second-quarter revenue, of which $3,534m was pass-through cost billed to clients at no margin. The profit sits in Advisory, the transactional book, and Advisory grew revenue 17.7% to $2.31bn while segment operating profit rose 29.4% to $449m — margins widening, not thinning. Global leasing revenue rose 24% and property sales 20%, with office leasing posting its best second quarter on record. CBRE raised full-year core earnings guidance to $7.80-$7.90 a share, about 23% growth at the midpoint.
Newmark, the most transaction-levered of the three with 8,800 staff against CBRE's 155,000, grew investment-sales fees 54.4% on first-half volumes up 64.8%, moving to second place in US investment sales. Its one deceleration is in debt: loan origination fees fell 26.1%. And it is the single name where the economics genuinely bent — operating income fell 5.5% to $40.4m on record revenue, producer compensation taking the entire gain, and management held 2026 guidance rather than raising it.
JLL did raise, lifting full-year adjusted earnings guidance to $24.60-$25.90 a share, roughly 34% growth at the midpoint, on operating income up 33% against revenue up 10.8%. LaSalle's assets under management finished the quarter at $86.8bn, flat on $86.9bn three months earlier — the steady leg while brokerage surged, which is why this is not one undifferentiated property trade. Chief executive Christian Ulbrich told investors the technology is already inside the reported figures: "The whole topic around data and AI because we were investing, as you know, into that topic for a very long time. And so we are starting from a very strong base." CBRE chair and chief executive Robert Sulentic has defended the model on economics rather than sentiment: "We're deploying AI where its economic value clearly exceeds the economic value of traditional efficiency levers like offshoring."
The month, and what it costs
Since 21 August CBRE has fallen 10.3%, JLL 16.3% and Newmark 19.0%, with Colliers International and Cushman & Wakefield down 14.7% and 16.8% alongside them. Over twelve months the group splits: JLL is up 3.5% while Colliers is down 43.9%. Part of September belongs to rates — the ten-year Treasury topped 5.04% and the Federal Reserve raised its target range to 3.75%-4.00% on 16 September — but a bond move does not explain a session triggered by a shopping app.
The drawdown left JLL at 12.96x forward earnings against roughly 18x historically, CBRE at 17.4x and Newmark at 6.72x, on consensus estimates that were raised rather than cut. The honest caveat is that cheapness against a historical anchor assumes the anchor survives, and the disintermediation thesis is precisely the argument that it does not. So the verdict splits cleanly: Newmark's compensation squeeze is earned, and nothing in CBRE's or JLL's reported quarters earns the rest of a 15% segment drawdown. What has changed is the burden of proof — accelerating fees no longer settle the argument, because the argument is about a business that will not report for years.
No institution has yet delegated a gateway-market office lease to an app. The market has begun pricing as though one will.