

NextEra's Allowed Return Is Locked at 10.95% Through 2029; Its Cost of Equity Is Not
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two of the largest builders of American power generation reported growing businesses and then sold off together in September, and only one of them has earned the de-rating. Entergy's June quarter grew revenue 5.9%, but diluted shares rose 4.6% and earnings per share slipped to $1.03 from $1.05 — the Gulf Coast build is being funded faster than it earns. NextEra grew adjusted earnings 9.5% and added 3.6 gigawatts to a signed backlog of 35.1 gigawatts, while its trailing earnings multiple compressed from 24.4x in May to 17.7x.
The shared event is the Federal Reserve's September 16 hike. Both companies spend more on plant than their operations generate, so the price of issued equity is now rising against returns that commissions have fixed for years.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
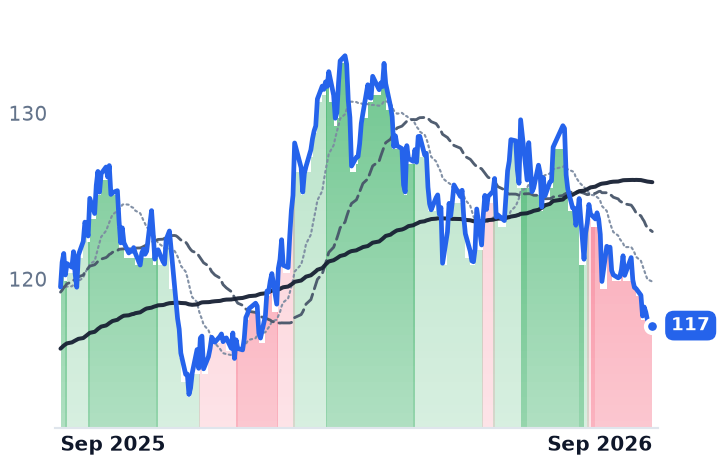
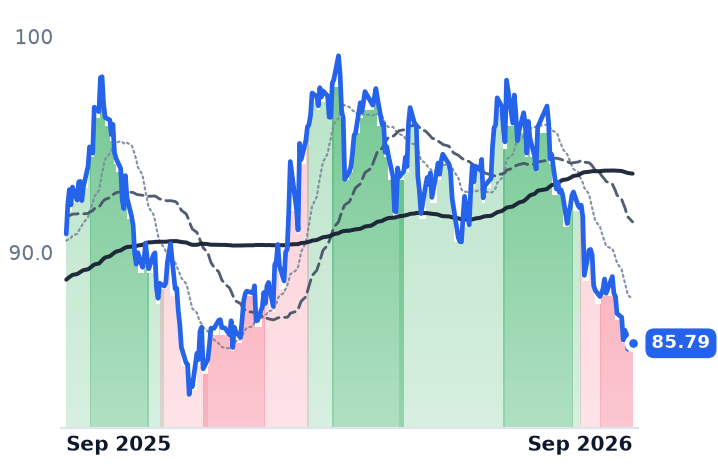
NEE | NextEra Energy | Vertically Integrated Utilities | 🔴 Cont. Bear | −5.1% | +11.8% |
ETR | Entergy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −4.3% | +15.0% |
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −5.3% | +7.8% |
| Compared against · context, not the story | |||||
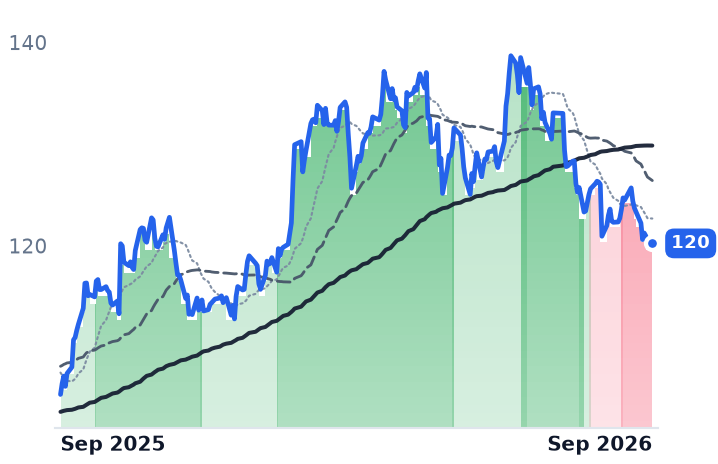
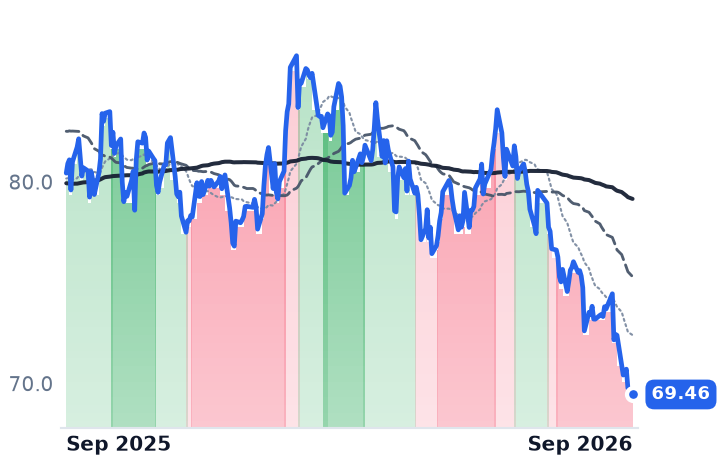
PCG | PG&E | Vertically Integrated Utilities | 🟢 Cont. Bull | −27.5% | −9.8% |
DUK | Duke Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −3.9% | −1.9% |
SO | The Southern | Vertically Integrated Utilities | ⚠️ Emerging Bear | −4.8% | −5.6% |
AEP | American Electric Power | Vertically Integrated Utilities | ⚠️ Emerging Bear | −1.4% | +14.1% |
PEG | Public Service Enterprise Group Incorporated | Vertically Integrated Utilities | ⚠️ Emerging Bear | −5.5% | −13.7% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.4% | +16.8% |
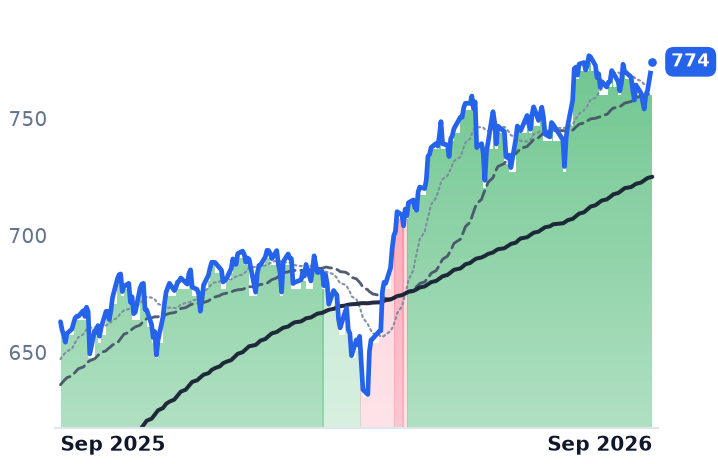
12-month price & trend
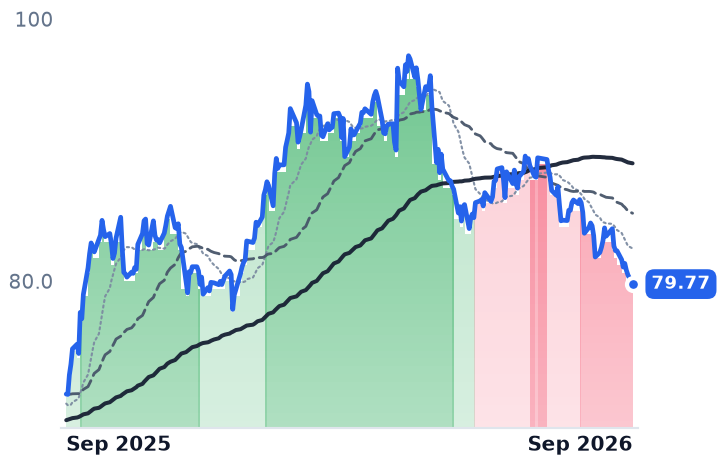
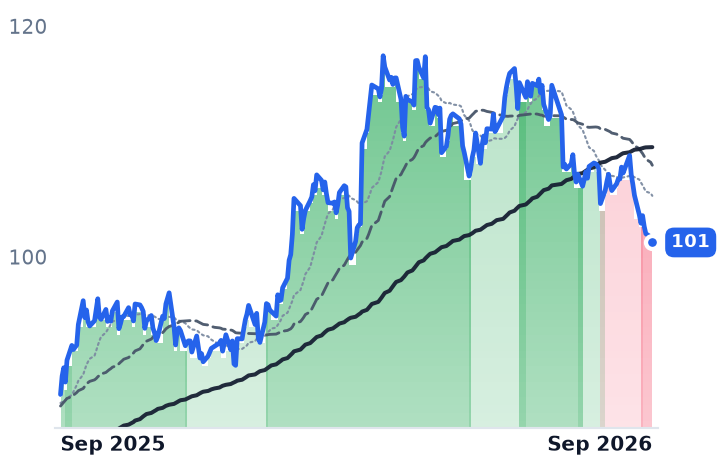
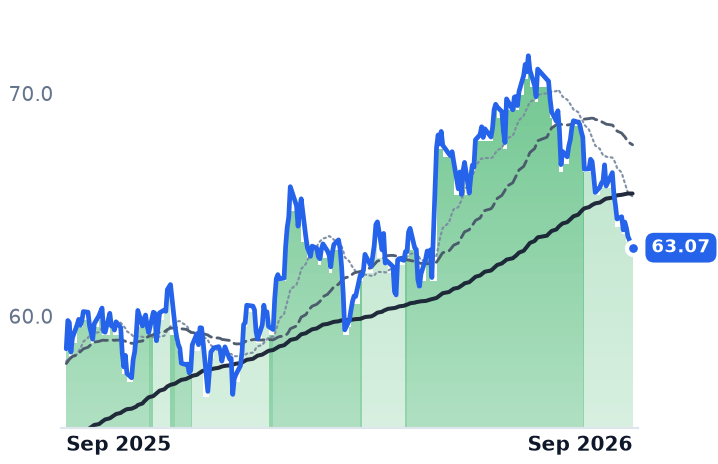
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEE | $165.4B | 17.7x | 19.7x | 5.7x | 5.3x | 7.9x | 7.4x | 15.4x | -6.2% |
ETR | $47.3B | 25.6x | 23.0x | 3.5x | 3.4x | 9.0x | 8.7x | 14.0x | -6.7% |
D | $55.1B | 21.7x | 17.5x | 3.0x | 3.0x | 6.1x | 6.1x | 14.7x | -12.4% |
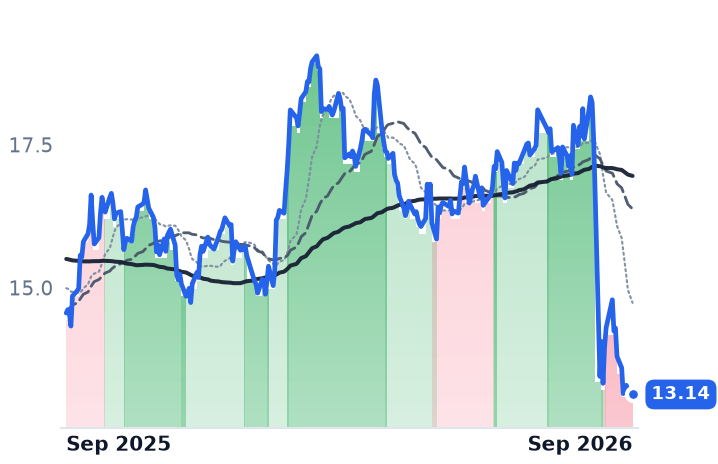
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCG | $37.7B | 10.2x | 8.5x | 1.5x | 1.4x | 2.6x | 2.6x | 9.6x | -11.3% |
DUK | $93.7B | 18.1x | 17.9x | 2.8x | 2.8x | 4.1x | 4.1x | 11.4x | 1.6% |
SO | $106.6B | 22.2x | 20.2x | 3.5x | 3.5x | 8.1x | 8.0x | 12.7x | 2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AEP | $67.8B | 21.4x | 19.5x | 3.0x | 2.9x | 6.1x | 5.9x | 14.1x | 13.2% |
PEG | $37.7B | 18.7x | 17.3x | 3.0x | 3.0x | 3.5x | 3.5x | 14.2x | 5.3% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.1% | +8.5% | |
ETR | Revenue | +8.6% | +9.8% | +9.8% |
| EPS | +12.3% | +16.1% | +13.6% | |
D | Revenue | +13.9% | +6.6% | +5.9% |
| EPS | +5.0% | +6.3% | +7.0% | |
PCG | Revenue | +2.8% | +3.9% | +3.9% |
| EPS | +10.1% | +9.0% | +9.2% | |
DUK | Revenue | +5.8% | +4.6% | +4.2% |
| EPS | +6.3% | +6.9% | +7.0% | |
SO | Revenue | +7.7% | +5.5% | +6.1% |
| EPS | +6.8% | +7.5% | +9.2% | |
AEP | Revenue | +9.5% | +5.9% | +7.6% |
| EPS | +7.9% | +7.6% | +10.6% | |
PEG | Revenue | +6.5% | +3.5% | +4.9% |
| EPS | +8.1% | +7.0% | +7.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
NextEra Energy, which owns Florida Power & Light and the largest contracted clean-energy development arm in the United States, knows precisely what it may earn on money invested in Florida through the end of 2029. Florida regulators approved a four-year settlement setting an authorized return on equity of 10.95% on a 59.6% equity layer, with base rates rising $945m from January 2026 and a further $705m a year later. What the company pays for that equity is not settled, and in September it went up.
The distance between those two numbers is where a regulated utility's profit actually lives. Entergy, NextEra and Dominion Energy all run negative trailing free cash flow — Dominion the deepest at -12.4% of market value, Entergy at -6.7%, NextEra at -6.2% — which means each spends more on plant than operations generate and issues securities to cover the difference. When the Federal Reserve raised rates on September 16 and the 10-year Treasury yield returned to 5%, its highest since 2007, the cost of the next dollar of that funding moved while allowed returns near 9.8% to 11% stayed exactly where commissions put them.
What actually moved
Between September 8 and September 21 every large regulated power name fell — Entergy 6.5%, PSEG 6.7%, Dominion 5.1%, NextEra 5.0%, AEP 4.3%, Southern 3.5%, Duke 3.4% — while the S&P 500 exchange-traded fund rose 0.9%. The thirty-day group number is worse, but half of it is one broken company: PG&E dropped 23% across two sessions at the end of August after California's legislature passed a wildfire bill stripped of the liability protections utilities expected. That is a Sacramento event, not a cost-of-capital one. Utilities are now roughly flat for the year and the second-worst of the index's eleven industries.
Entergy: the load is real, the shares are new
Entergy sells power to about 3 million customers in Arkansas, Louisiana, Mississippi and Texas, and it is building into the biggest industrial order book in its history. "We continue to have seven to 12 gigawatts of hyperscale data center potential in our pipeline, as well as three to five gigawatts of interest from traditional industrial segments," chair and chief executive Drew Marsh told investors on July 29. Louisiana's rate base is expected to roughly double to near $50bn by 2030 inside a $67bn plan.
The terms are better than the skeptics assume. Entergy's "Fair Share Plus" framework carries prepayments, parent-company guarantees and early-termination penalties, and in Arkansas Alphabet agreed to pay $526m toward a solar-and-storage project plus $190m for transmission. The problem is arithmetic between the plant and the shareholder. June-quarter revenue rose 5.9% to $3.524bn and net income 3.4%, but operating margin fell to 23.7% from 25.2% and diluted earnings per share slipped to $1.03, because the share count rose 4.6%. On September 2 the company settled 11.1m more shares for about $913m while reaffirming guidance of $4.25 to $4.45. Entergy trades at 25.6x trailing and 23.0x forward earnings, against 29.9x trailing in mid-May — and at 2.52x book value against a Louisiana return of about 9.7% once affiliate preferred investments are stripped out.
NextEra: nothing in the demand book broke
"NextEra Energy delivered a strong second quarter, with adjusted earnings per share increasing by 9.5% year-over-year," chairman and chief executive John Ketchum said of results reported July 24. Revenue grew 12.4%, operating income 17.1% — faster than sales — and the share count rose 1.3%. Yet the stock has fallen 12.9% in six months and trades at 17.7x trailing earnings below its own 19.7x forward, which says trailing accounting profit sits above the adjusted run-rate, not that the shares are cheap. Consensus still models 9% adjusted earnings growth this year and next.
Dominion, which NextEra agreed in May to buy entirely in stock at 0.8138 shares apiece, is now an input to that judgment rather than a separate one: both shareholder bases approved the $66.8bn combination on September 3, and on September 21 the two closed at a ratio of 0.7907, a 2.8% discount for deal risk. What NextEra inherits is a Virginia franchise with about 12 gigawatts under executed service agreements out of 53 in some stage of contracting, a new class for customers above 25 megawatts that bills a minimum on 85% of contracted delivery demand from January 2027 — and an offshore wind project whose cost has climbed to $11.5bn from $9.8bn at 81% complete, earning a state-allowed return of only 9.8%.
The split
September hit these two the same way and they did not deserve the same verdict. Entergy's compression is rational work on an expensive starting point: the hyperscaler load is contracted and the risk terms are sound, but the equity funding it is being issued today against rates a commission will approve later, and per-share earnings have already gone backwards once. NextEra's is financing cost and nothing else — a locked allowed return, a growing signed backlog, positive operating leverage and almost no dilution. The honest bear case is that a higher discount rate is permanent; it is not that the order book softened.
The largest single block of contracted megawatts in the group still has no approved rate behind it. Louisiana regulators take up Entergy's seven gas plants for Meta's Hyperion campus on December 16.