

MYR Group's Record Quarter Came From Wiring Data Centers While Transmission Grew 3.5%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Three firms filed under the same grid-interconnection label — AECOM, Tetra Tech and MYR Group — each set a record backlog in its latest quarter, and their shares have moved 106 percentage points apart over twelve months. Nothing in the order books explains that.
What explains it is contract form and conversion date. MYR Group's growth is fixed-price data-center electrical work, where commercial and industrial revenue rose 41.5% to $557.7m while transmission barely moved; AECOM's record $27.8bn book sits behind a $337m charge on a design-build project bid in 2018; Tetra Tech grew revenue 13.5% last quarter while gross profit fell 3.3%.
One of the three is a demand story, and the demand is landing inside buildings rather than on the interconnection queue.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
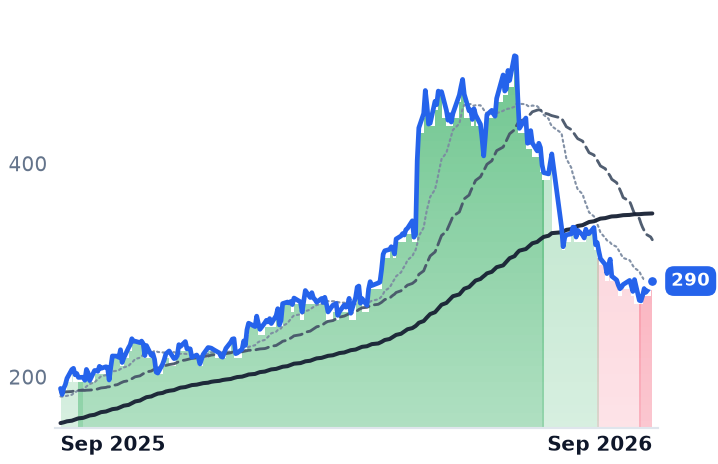
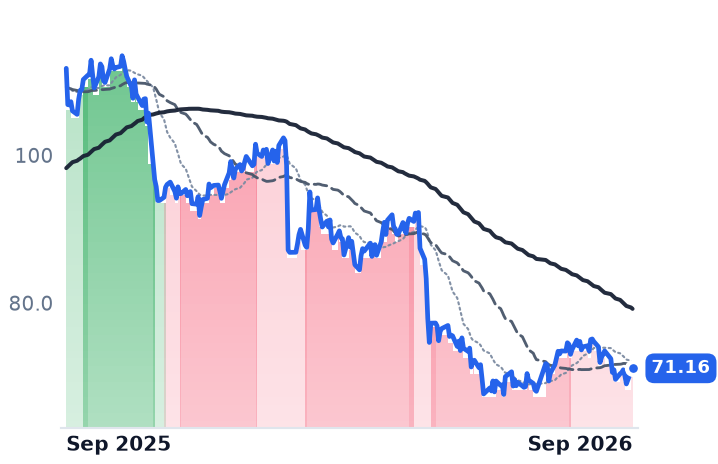
MYRG | MYR | Electrical & Power Infrastructure | ⚠️ Emerging Bear | −5.0% | +53.2% |
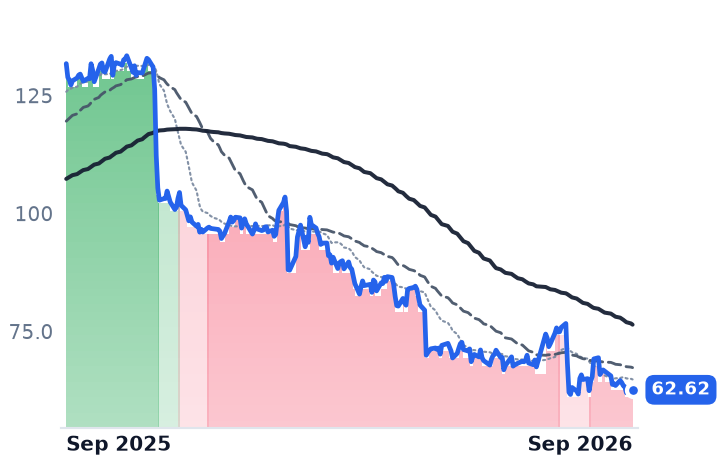
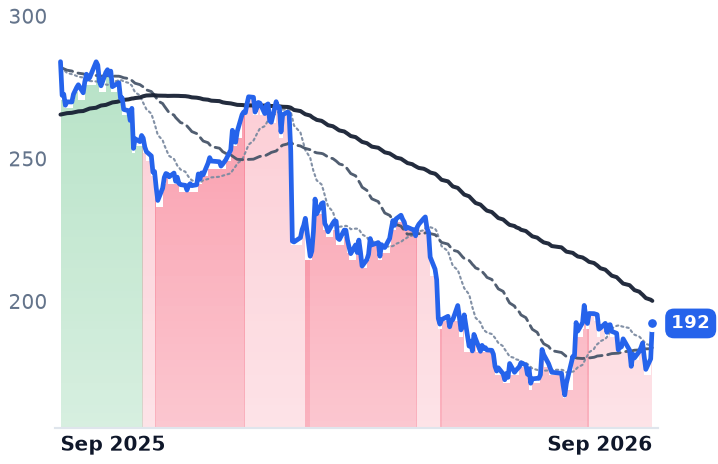
ACM | Aecom | Design & Engineering Consulting | 🔴 Cont. Bear | −3.6% | −52.5% |
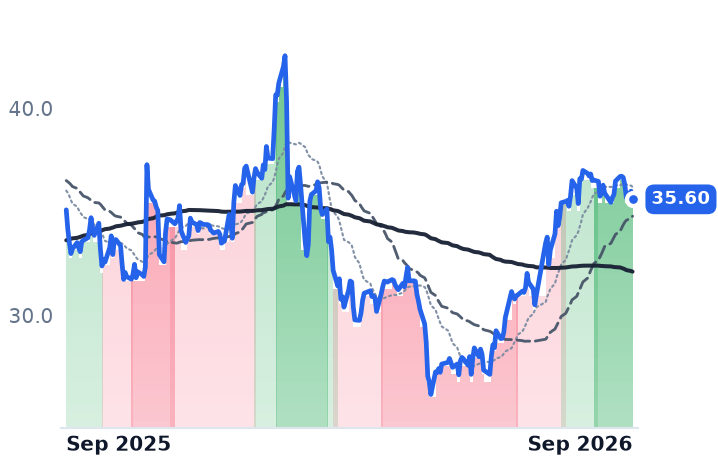
TTEK | Tetra Tech | Design & Engineering Consulting | 🌱 Emerging Bull | −3.4% | +1.4% |
| Compared against · context, not the story | |||||
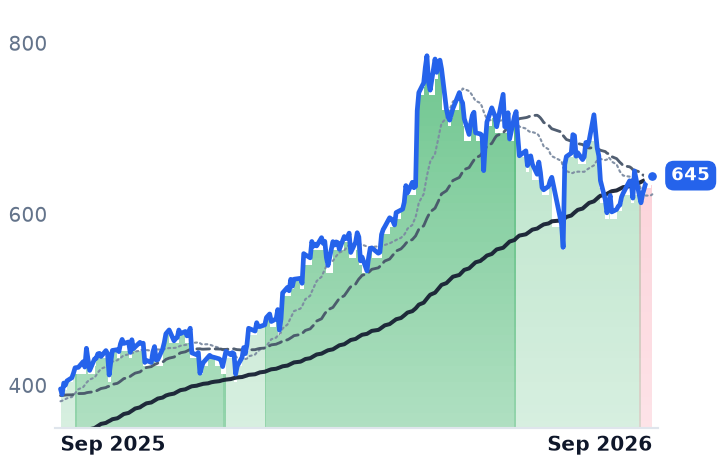
PWR | Quanta Services | Electrical & Power Infrastructure | 🟢 Cont. Bull | +4.6% | +63.0% |
STN | Stantec | Design & Engineering Consulting | 🔴 Cont. Bear | −4.1% | −36.3% |
WSP.TO | WSP Global | Engineering & Construction | 🔴 Cont. Bear | −0.0% | −32.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MYRG | $4.5B | 27.2x | 23.7x | 1.1x | 1.0x | 9.1x | 8.2x | 15.0x | 4.3% |
ACM | $8.0B | 28.2x | 15.6x | 0.5x | 1.1x | 9.2x | 19.2x | n/m | 2.5% |
TTEK | $9.2B | 21.2x | 22.5x | 1.8x | 2.1x | 9.7x | 11.3x | 15.0x | 6.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWR | $92.7B | 69.7x | 36.8x | 2.8x | 2.4x | 19.6x | 16.3x | 32.5x | 2.6% |
STN | $8.1B | 22.6x | 16.0x | 1.4x | 1.1x | 3.3x | 2.6x | 12.1x | 5.8% |
WSP.TO | $23.1B | 23.3x | 14.9x | 1.3x | 1.4x | 7.3x | 8.1x | 13.3x | 7.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MYRG | Revenue | +22.9% | +15.5% | +11.4% |
| EPS | +72.5% | +18.4% | +22.2% | |
ACM | Revenue | −2.9% | +8.6% | +5.8% |
| EPS | −24.1% | +60.4% | +14.2% | |
TTEK | Revenue | −3.5% | +4.3% | +1.8% |
| EPS | +4.1% | +10.2% | +8.2% | |
PWR | Revenue | +40.6% | +16.5% | +12.8% |
| EPS | +57.5% | +17.6% | +16.6% | |
STN | Revenue | +9.5% | +6.0% | +4.8% |
| EPS | +15.3% | +11.8% | +12.3% | |
WSP.TO | Revenue | +18.9% | +7.5% | +6.9% |
| EPS | +19.5% | +14.6% | +13.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
MYR Group, the Colorado electrical contractor founded in 1891 that builds high-voltage transmission lines and substations for utilities and wires data centers, hospitals and stadiums, had the best quarter in its history in June. The growth came from the buildings. Commercial and industrial revenue rose 41.5% to a record $557.7m, driven by fixed-price contracts, while transmission and distribution revenue rose 3.5%.
That split is the whole story of a group of companies investors treat as one trade. AECOM, Tetra Tech and MYR Group each reported a record backlog in its most recent quarter, and over the twelve months to September 22 their shares moved 106 percentage points apart — AECOM down 52.9%, Tetra Tech up 1.1%, MYR Group up 53.2%. Demand is not what separates them. What separates them is what kind of contract the demand arrives on, and when it converts to cash.
The contractor: paid a construction margin, priced on a calendar
MYR Group's June quarter beat consensus earnings by 20%, with gross margin up 181 basis points to 13.2% and net income up 88% to $49.9m. Backlog hit a record $3.16bn, up 19.6% — but $1.89bn of it is commercial and industrial work against $1.27bn in transmission and distribution. The order book is not an interconnection book.
The shares fell 21.3% in the week before that print and are down 40% over three months. The one discoverable company-specific catalyst since is a valuation call: Kansas City Capital's Jon Braatz cut the stock to Perform and withdrew his price target. The duration is the likelier pressure. Two Xcel Energy transmission awards booked this year produce no revenue until the second half of 2027, most major projects won will be built between 2028 and 2030, and second-half segment margins are guided below the June actuals — long-dated cash at a moment when the 30-year Treasury yield sits at 5.296%.
The consultant: one bid from 2018
AECOM, the Dallas design and program-management firm whose largest client is the Department of War, took a $337m pretax charge in its fiscal third quarter on a single construction-management project, turning quarterly gross profit negative and diluted earnings to minus $0.67. The project was a public-private design-build awarded in 2019 on terms the company says its current risk policies would reject, it is 80-85% complete, and subcontractor productivity is the cause. The cash cost is roughly $500m through the first half of fiscal 2027; free cash flow guidance fell to $300m from $400m.
Everything else went up. Net service revenue grew 5%, backlog reached a record $27.8bn on a 1.6x book-to-burn ratio, and full-year margin guidance was raised. On the August 11 call, management described the data-center business and its outlook as very strong and fast-growing, and president Lara Poloni cited a 30% expansion in the water pipeline, per Construction Dive's account. Construction management is 6-7% of net service revenue and the company says it will bid no more of this contract type. The shares fell 19.0% across two sessions and now trade at 15.7x forward earnings, against the 22-24x forward they carried in May.
The one growing without profit
Tetra Tech, the Pasadena water and environmental consultancy, is the name where the pass-through problem is real. Fiscal third-quarter revenue rose 13.5% to $1.309bn while gross profit fell 3.3%, a 323 basis-point margin loss, and that is the third straight quarter of flat-to-lower gross profit on rising revenue. Operating income fell 4.3%.
Its federal exposure, the risk everyone watched, already detonated: USAID contracts worth 10.6% of fiscal 2025 revenue were converted to terminations for convenience on February 27. Tetra Tech grew through it — federal customers, 20% of net revenue, grew 12% excluding USAID, State and disaster work. Chief executive Roger Argus told investors on July 30 he was "very encouraged by the 5% sequential backlog growth, our second consecutive quarter of growth," adding that the figure "includes only contracted, funded, and authorized work". The shares are up 31.1% in three months on that, and now trade at 22.5x forward earnings — above their 21.2x trailing, an inversion that says consensus expects no earnings growth at all.
What the label hides
None of the three is trading on interconnection. AECOM's collapse is a cash bill for a bid signed before the AI build existed, on a business line it has exited; its order flow never wavered. Tetra Tech's re-rating is being paid for profit that has gone backwards for three quarters. MYR Group's fall is a multiple cut against estimates that rose — consensus has its 2026 earnings up 72.5%. Stantec, which won Meta's $13bn Alberta data-center design mandate and posted a record margin, fell 36.5% over the year anyway, which is what a de-rating that ignores execution looks like.
The demand is real and it is being captured by whoever holds the fixed-price contract to install equipment inside a building. The designers bill hours on work that was funded years ago; MYR Group's record book gets built at the end of the decade. Until then its shares are less a bet on the grid than on the discount rate applied to 2029.