

Six in Ten KB Home Orders Carry a Mortgage Concession — the Cost Lands in Gross Margin
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Regional homebuilders were supposed to be the consumer group rescued when financing costs fall. Instead the Federal Reserve raised rates on September 16, the 30-year mortgage benchmark touched a one-year high of 7.05%, and builder sentiment sank to a 12-month low.
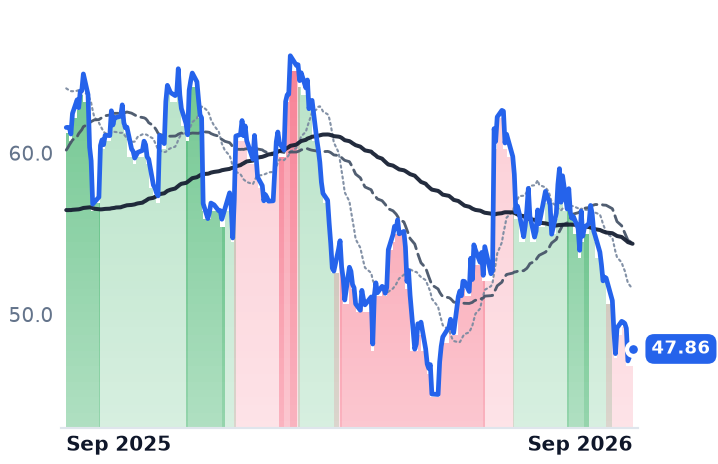
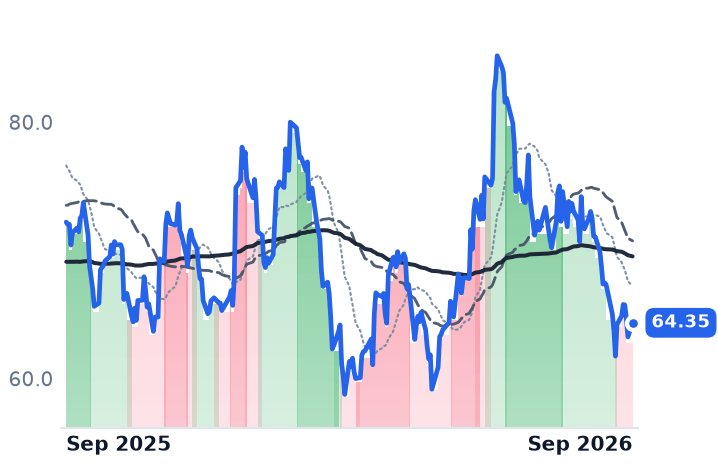
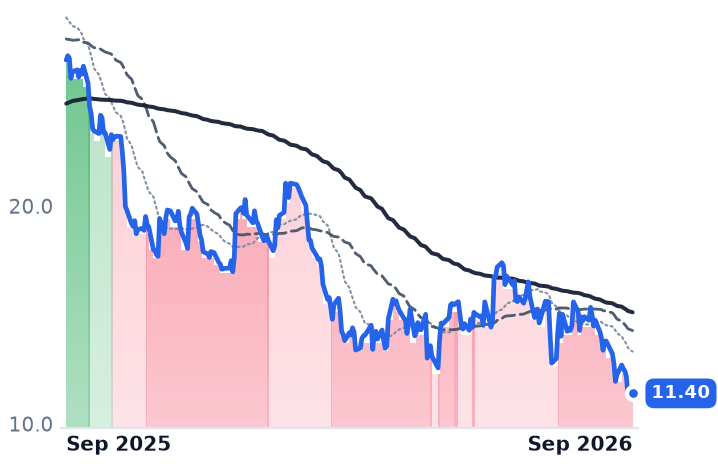
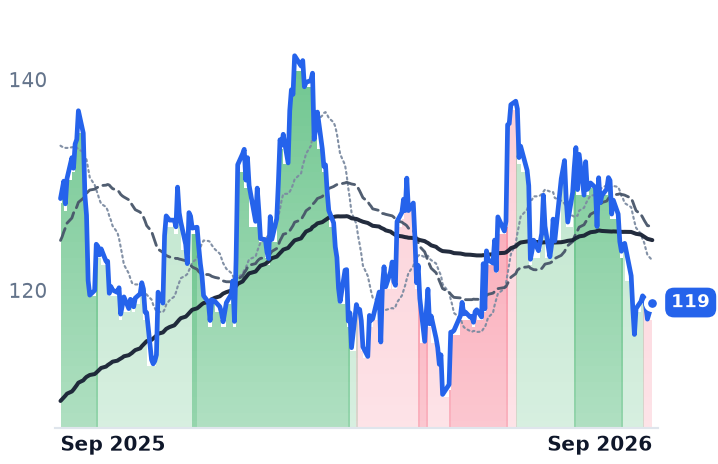
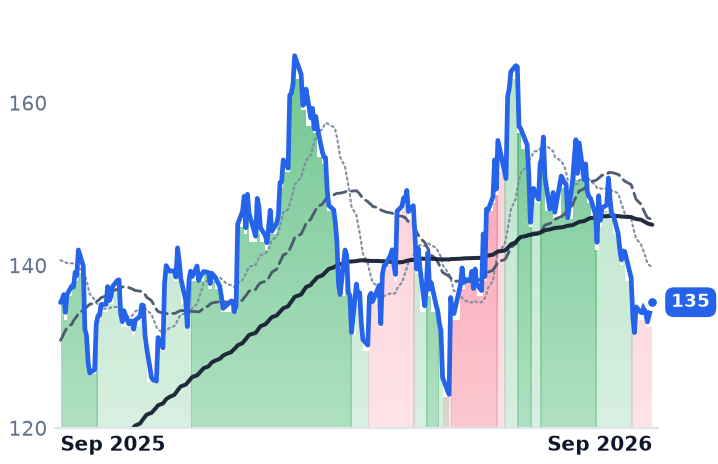
The mechanism matters more than the move. The concession builders actually give is a paid-down mortgage rate, and it lands in cost of sales rather than in the sticker price — so the discount shows up as margin instead of as a lower average selling price. KB Home's housing gross margin has fallen for four straight quarters, to 15.6% from 20.3%; Meritage's home closing margin dropped to 18.3% from 21.1%; Dream Finders' to 14.2%, which it blames primarily on land and financing costs. All three trade below book value, and all three repurchased stock last quarter. KB Home reports today against a 16.0–16.6% margin guide.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
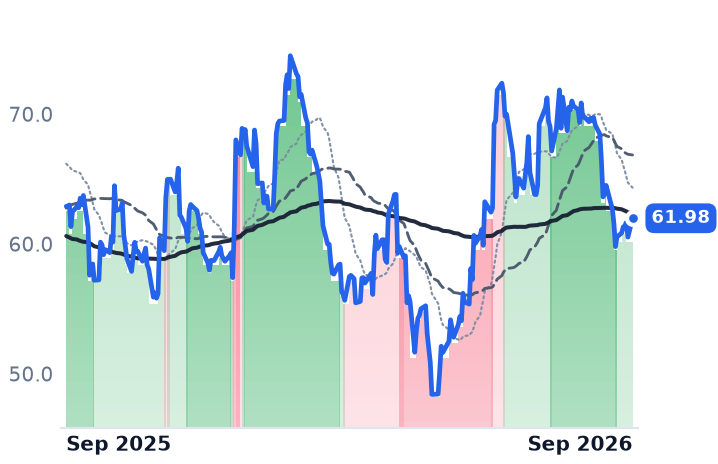
KBH | KB Home | Regional & Mid-Size Homebuilders | 🔴 Cont. Bear | −14.0% | −22.3% |
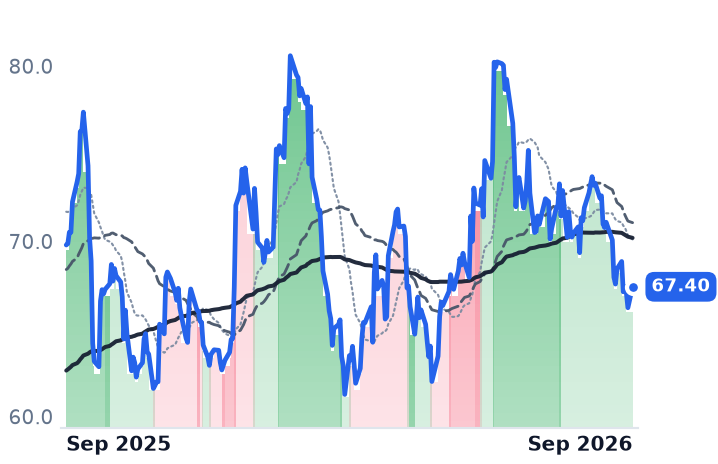
MTH | Meritage Homes | Regional & Mid-Size Homebuilders | 🌱 Emerging Bull | −11.3% | −10.9% |
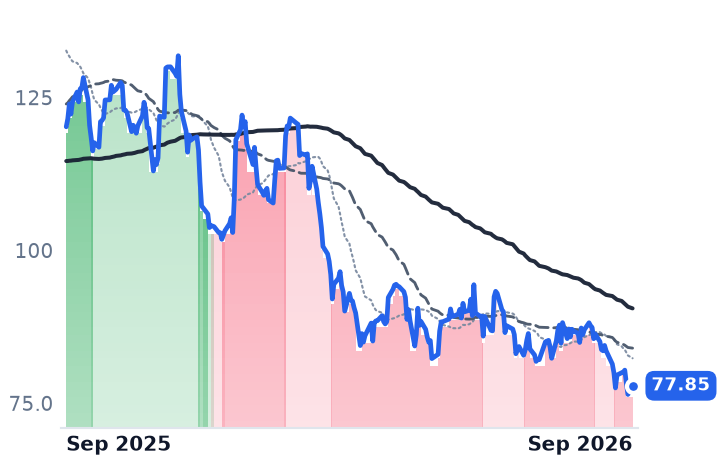
DFH | Dream Finders Homes | Regional & Mid-Size Homebuilders | 🔴 Cont. Bear | −22.8% | −57.3% |
| Compared against · context, not the story | |||||
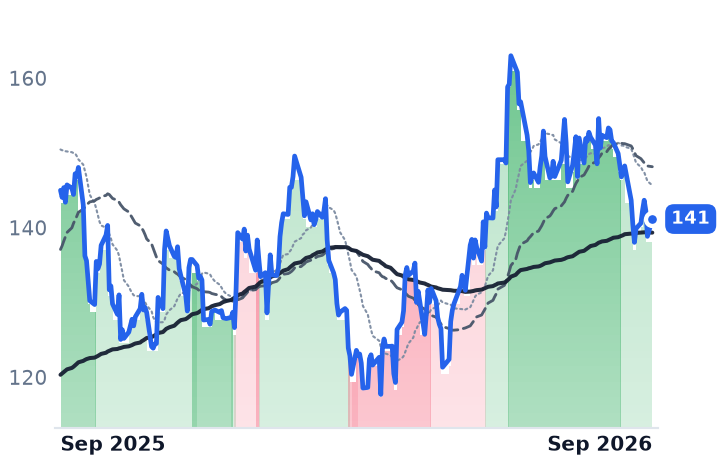
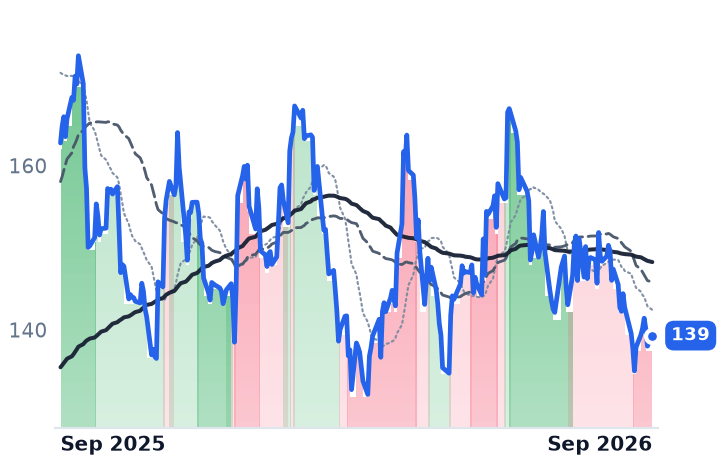
MHO | M/I Homes | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | −7.2% | −2.7% |
CCS | Century Communities | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | −10.7% | −1.5% |
GRBK | Green Brick Partners | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | −7.4% | −3.4% |
DHI | D.R. Horton | Large National Homebuilders | 🔴 Cont. Bear | −6.5% | −14.4% |
LEN | Lennar | Large National Homebuilders | 🔴 Cont. Bear | −11.7% | −35.2% |
PHM | PulteGroup | Large National Homebuilders | 🟢 Cont. Bull | −8.3% | −7.7% |
TOL | Toll Brothers | Large National Homebuilders | 🟢 Cont. Bull | −8.1% | +0.0% |
TMHC | Taylor Morrison Home | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | — | +9.9% |
TPH | Tri Pointe Homes | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | — | +40.1% |
BZH | Beazer Homes USA | Entry-Level & Value Homebuilders | 🟢 Cont. Bull | +0.9% | +36.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KBH | $2.9B | 11.4x | 14.5x | 0.5x | 0.6x | 3.1x | 3.4x | 12.3x | 12.4% |
MTH | $4.3B | 13.4x | 13.0x | 0.8x | 0.8x | 4.2x | 4.2x | 10.6x | 9.7% |
DFH | $1.1B | 7.2x | 10.1x | 0.3x | 0.2x | 1.8x | 1.8x | 11.6x | -15.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MHO | $3.5B | 11.5x | 11.6x | 0.8x | 0.8x | 3.9x | 3.9x | 7.5x | 5.7% |
CCS | $1.4B | 10.7x | 12.9x | 0.3x | 0.4x | 2.0x | 2.2x | 14.2x | 6.8% |
GRBK | $2.7B | 9.0x | 10.5x | 1.3x | 1.4x | 4.3x | 4.4x | 7.0x | 7.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DHI | $38.4B | 12.3x | 12.8x | 1.2x | 1.1x | 5.0x | 5.0x | 10.4x | 9.1% |
LEN | $20.8B | 11.3x | 13.4x | 0.6x | 0.6x | 3.7x | 3.8x | 9.4x | 0.1% |
PHM | $21.0B | 10.3x | 11.0x | 1.2x | 1.3x | 4.8x | 4.9x | 7.8x | 7.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TOL | $12.0B | 8.8x | 9.9x | 1.1x | 1.1x | 4.2x | 4.5x | 7.2x | 12.2% |
TMHC | $5.1B | 7.8x | 10.3x | 0.7x | 0.8x | 3.0x | 3.5x | 6.9x | 13.9% |
TPH | $4.0B | 21.7x | 24.5x | 1.2x | 1.3x | 6.0x | 6.5x | 16.0x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BZH | $604.6M | n/m | — | 0.3x | 0.3x | 2.2x | 2.2x | — | -11.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
KBH | Revenue | −17.6% | +7.5% | +7.3% |
| EPS | −48.3% | +33.4% | +28.4% | |
MTH | Revenue | −8.9% | +7.3% | +7.2% |
| EPS | −26.3% | +20.1% | +30.2% | |
DFH | Revenue | +1.6% | +7.1% | — |
| EPS | −47.6% | +4.9% | — | |
MHO | Revenue | −4.5% | +4.1% | −2.1% |
| EPS | −25.7% | +15.4% | +9.6% | |
CCS | Revenue | −6.2% | +8.3% | — |
| EPS | −30.8% | +30.8% | — | |
GRBK | Revenue | −3.0% | +9.3% | — |
| EPS | −15.0% | +12.4% | — | |
DHI | Revenue | −1.8% | +5.8% | +6.1% |
| EPS | −10.5% | +12.3% | +16.8% | |
LEN | Revenue | −2.9% | +3.4% | +8.6% |
| EPS | −25.8% | +21.8% | +22.3% | |
PHM | Revenue | −3.9% | +4.9% | +7.6% |
| EPS | −12.0% | +11.5% | +17.9% | |
TOL | Revenue | −1.9% | +6.0% | +5.1% |
| EPS | −7.7% | +10.8% | +12.0% | |
TMHC | Revenue | −17.0% | +8.0% | — |
| EPS | −32.0% | +23.3% | — | |
TPH | Revenue | −11.9% | +7.7% | +96.9% |
| EPS | −31.5% | +21.3% | +249.2% | |
BZH | Revenue | −6.8% | +14.8% | — |
| EPS | −151.2% | −296.5% | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
The discount that never reaches the sticker price
KB Home reports fiscal third-quarter results today, and the line that decides the quarter is not deliveries. The Los Angeles builder, which sells single-family homes and townhomes to first-time, move-up and active-adult buyers across the West Coast, Southwest, Central and Southeast, guided in June to a housing gross margin of 16.0–16.6% on 2,600–2,800 deliveries. Consensus earnings per share is $0.90.
Margin is where the discounting lives. The industry's preferred concession is a builder-paid mortgage-rate buydown — a forward commitment bought from a mortgage bank so the buyer gets a below-market rate — and it lands in cost of sales rather than in the list price. KB Home told analysts on June 23 that roughly 60% of its orders carry some form of mortgage concession, flat against the prior two quarters. The cost of that concession rises with the rate being bought down, and the 30-year benchmark reached a one-year high of 7.05% in the week of September 14–18, with the 10-year Treasury above 5%. The Federal Reserve raised its policy rate a quarter point to 3.75–4% on September 16, its first increase since 2023. Builder sentiment fell to 32, a 12-month low, and 66% of builders used incentives in September, the highest share since December.
Three builders, three meters
KB Home sells built-to-order: 73% of net orders in the quarter ended May 31 were houses configured by a buyer, so booked revenue reflects contracts struck months earlier. That quarter's revenue fell 27.3% to $1.112bn and gross margin came in at 15.6% against 19.5% a year earlier — the fourth consecutive quarterly decline from 20.3%. Average selling price for the half fell 8% to $457,000. The order book is thinning as the store count grows: ending community count rose 11% to 280 while backlog value fell 7% to $2.14bn on 4,526 homes. Cancellations improved, to 12% of gross orders from 16%. "We produced solid second-quarter results that met or exceeded the mid-point of our key guidance ranges," executive chairman Jeffrey Mezger said on June 23.
Meritage Homes, which builds mostly move-in-ready houses for entry-level buyers across Texas, Arizona, Florida and the Southeast, gives its concessions in the quarter it closes the sale. Its home closing gross margin fell to 18.3% in the June quarter from 21.1%, with orders down 9% as a 19% slower absorption pace outran a 14% larger community count. Cancellations rose to 13% from 10% — the only worsening of the three. But its unsold finished houses are shrinking, not piling up: completed specs fell to 30% of total spec count from 50% at the end of 2025. "Our second quarter results reflect solid execution in a softer demand environment," chief executive Phillippe Lord told investors on the July 30 call, adding that the company "saw no meaningful deterioration in demand from the first quarter to the second quarter." It cut 2026 guidance to roughly 5% below 2025 at the same time — before, not during, the recent slide.
Dream Finders Homes, a Jacksonville builder that controls most of its lots through option deposits with land bankers instead of owning dirt, is the test of whether that structure helps. Orders rose 15% to a second-quarter record 2,232 and cancellations fell to 11.1% from 14.0%, yet homebuilding gross margin dropped to 14.2% from 16.5%, which the company attributed primarily to higher land and financing costs. The optioned pipeline is being released rather than extended — 54,091 controlled lots at June 30 against 63,121 at year-end — and $3.0m of lot-deposit and deal-abandonment charges appeared in selling and administrative expense.
What the shares did, and what they are priced at
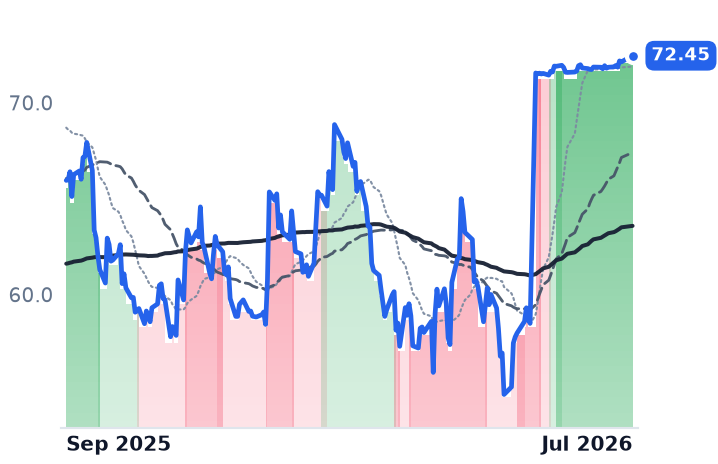
Over the thirty days to September 21, KB Home fell 13.6%, Meritage 10.2% and Dream Finders 23.6%, alongside D.R. Horton at -6.1%, Lennar -10.5% and PulteGroup -7.9%. No company news dated inside that window explains it; the repricing is the rate move.
All three now sit below book value — Meritage at 0.85 times, KB Home 0.78, Dream Finders 0.66 — and each bought back stock last quarter, $100m, $75m and $15m respectively. On earnings the picture inverts. KB Home's forward price-to-earnings of 14.5x sits above its trailing 11.4x, because fiscal 2026 consensus has already been cut 48% to $3.31 a share. Meritage's forward multiple of 13.0x is barely below its trailing 13.4x on consensus of $4.94, down 26%. Dream Finders looks cheapest at 7.2x trailing, but it consumes cash — free cash flow yield of minus 15.4%, against plus 12.4% at KB Home — and analysts pencil in only $1.19 for 2027 after $1.13 this year.
The verdict
The business earns most of this de-rating. Revenue is falling at all three, reported margins are compressing at all three, and estimates have been cut by a quarter to a half — this is not multiple compression against intact earnings. What it is not is a demand collapse: cancellations improved at two of the three, and Dream Finders sold more houses than in any prior second quarter. The squeeze is arriving through the concession. Because the discount is a bought-down mortgage rate, the price line stays respectable and the margin line absorbs it, which means a 7% mortgage does not show up as falling average selling prices — it shows up as the number KB Home publishes today.
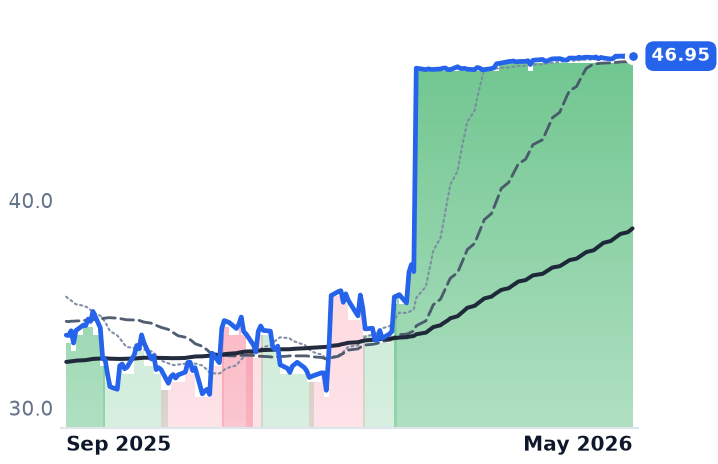
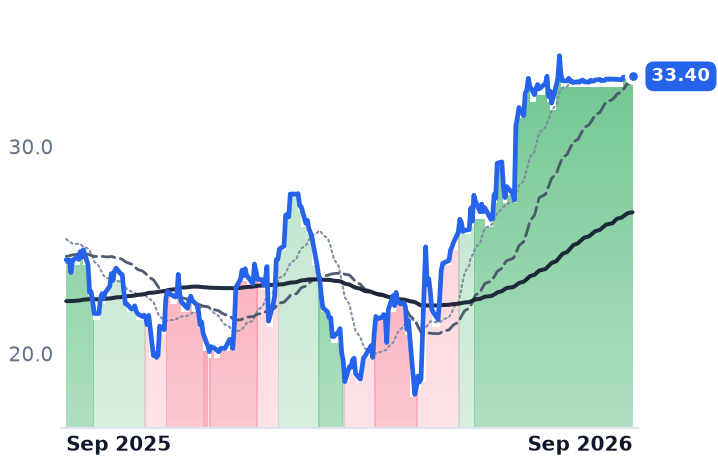
And Dream Finders has chosen this moment to get much bigger: it agreed in August to buy Beazer Homes for $33.50 a share in cash, an equity cheque of about $916m from a company worth roughly $1.05bn, on committed financing from Goldman Sachs, Bank of America and Kennedy Lewis, with closing expected in the fourth quarter. It has promised to keep a "100% land-light strategy" afterwards while buying a builder that owns its dirt.