

NXP Booked 18 Months of Backlog and Guided Third-Quarter Revenue Up 18% to $3.75bn
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
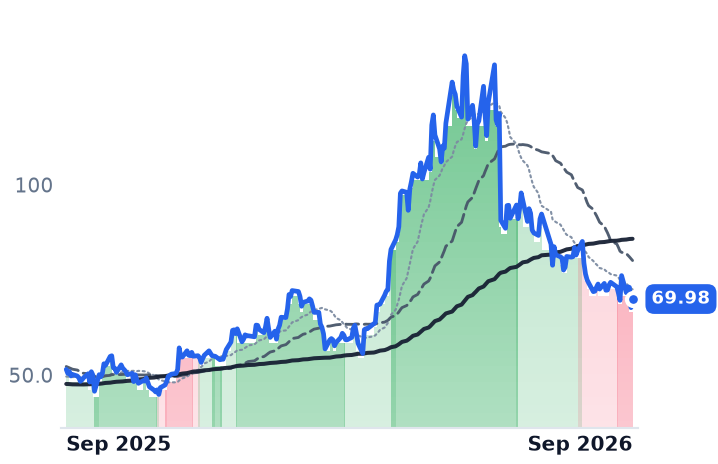
The automotive chip cycle that broke in 2025 has turned, and the company most levered to it is the one the market has paid for least. NXP Semiconductors' revenue went from shrinking 2.4% a year ago to growing 19.5% in the June quarter, with orders running above shipments and distributors holding only 11 weeks of stock — yet the shares are flat over twelve months.
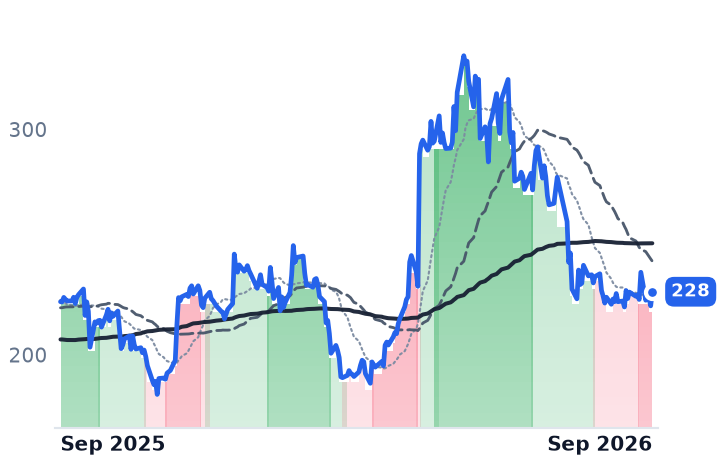
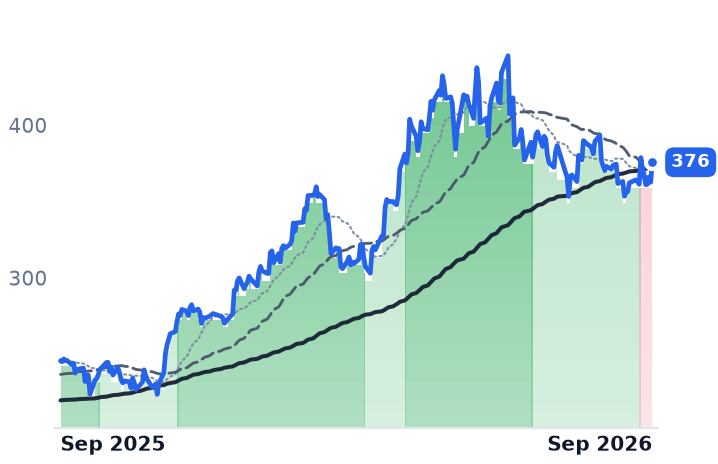
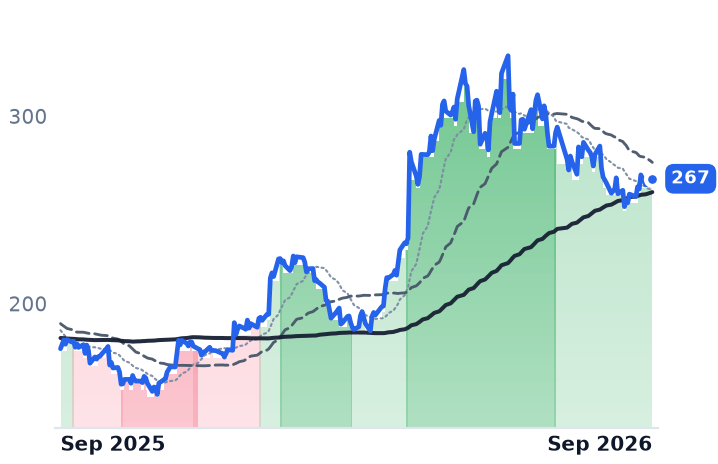
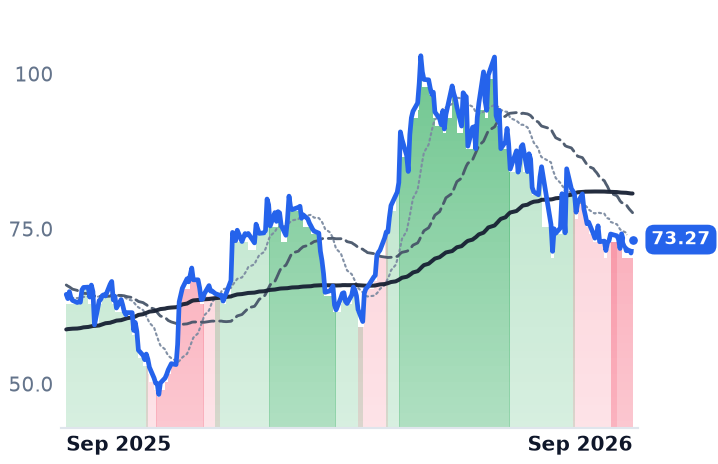
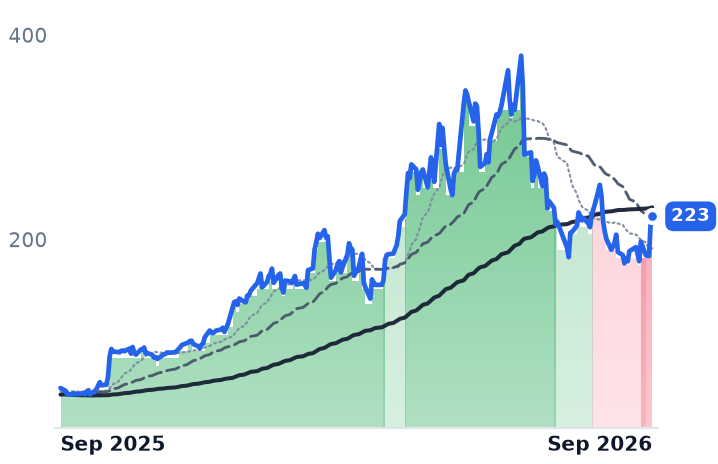
Analog Devices and Texas Instruments accelerated too, and both were repriced from mid-June alongside NXP. The split afterwards is the point: NXP now trades at 15.1x forward earnings and yields 5.1% on trailing free cash flow, against Texas Instruments at 31.3x and 2.2% with consensus itself modeling lower earnings in 2029 than 2028. One of the three de-ratings looks earned; NXP's is the one the meters do not explain.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
NXPI | NXP Semiconductors | Analog & Mixed-Signal | ⚠️ Emerging Bear | +2.5% | +2.0% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | +1.2% | +52.9% |
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | +3.0% | +51.5% |
| Compared against · context, not the story | |||||
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | −5.2% | +32.7% |
ON | ON Semiconductor | Analog & Mixed-Signal | ⚠️ Emerging Bear | −2.7% | +35.9% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | ⚠️ Emerging Bear | −1.3% | +13.7% |
VICR | Vicor | Other | ⚠️ Emerging Bear | +17.2% | +307.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXPI | $57.5B | 19.4x | 15.1x | 4.4x | 4.0x | 7.8x | 7.2x | 13.3x | 5.1% |
ADI | $183.0B | 44.4x | 29.2x | 13.2x | 12.1x | 20.0x | 18.4x | 29.1x | 2.7% |
TXN | $243.5B | 40.3x | 31.3x | 12.5x | 11.1x | 21.5x | 19.0x | 27.9x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $59.8B | 74.3x | 44.4x | 18.3x | 14.4x | 33.1x | 26.1x | 58.1x | 1.0% |
ON | $27.2B | 44.3x | 21.9x | 4.4x | 4.2x | 11.7x | 11.1x | 22.3x | 6.5% |
MCHP | $40.3B | 102.8x | 20.4x | 7.9x | 6.3x | 13.1x | 10.5x | 27.0x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VICR | $8.3B | 57.7x | 53.5x | 17.6x | 13.8x | 31.1x | 24.4x | 61.8x | 0.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NXPI | Revenue | +16.7% | +11.5% | +8.3% |
| EPS | +28.0% | +20.5% | +15.3% | |
ADI | Revenue | +37.8% | +22.1% | +11.6% |
| EPS | +65.8% | +29.4% | +18.0% | |
TXN | Revenue | +24.0% | +13.8% | +10.6% |
| EPS | +55.6% | +20.7% | +17.1% | |
MPWR | Revenue | +49.2% | +28.7% | +20.2% |
| EPS | +54.8% | +31.0% | +20.2% | |
ON | Revenue | +9.2% | +13.1% | +13.9% |
| EPS | +37.1% | +40.6% | +30.5% | |
MCHP | Revenue | +6.2% | +37.1% | +16.4% |
| EPS | +20.7% | +132.2% | +25.6% | |
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
NXP Semiconductors sold $1.938bn of automotive chips in the June quarter, up 12.1% year on year and 17% once divestitures are stripped out, and told investors its order book now stretches as far as 18 months out with book-to-bill above 1.0 across its end markets. The Dutch company — which sells microcontrollers, radar and Ethernet processors, connectivity and security chips into cars, factories and phones — guided the September quarter to $3.75bn, plus or minus $100m, an 18% annual gain.
That matters beyond one print because NXP is the cleanest read available on whether industrial and automotive demand is genuinely recovering rather than being restocked. Roughly 59% of its quarterly sales, $2.072bn, move through distributors, who finished June holding 11 weeks of inventory. Lean channels plus orders exceeding shipments is what a demand-led upturn looks like from the inside; a restocking bounce shows up as weeks of channel stock climbing while end demand sits still.
The trough was real
NXP's 2025 revenue fell 2.7% to $12.27bn and net income dropped 19.5%, so the four quarters since — minus 2.4%, then plus 7.2%, 12.2% and 19.5% — are a recovery off a genuine bottom, not a continuation. Gross margin came back to 57.3% from 53.4%, and operating income grew 55.9% on that 19.5% of revenue growth. The sockets driving it are structural: software-defined vehicle architectures and multi-year platform commitments for in-car Ethernet switches and processors, in an advanced driver-assistance component market of roughly $35-38bn growing at low double digits, where NXP and Texas Instruments compete with Renesas on cost and power for camera and perception modules rather than with Nvidia's high-end autonomy compute.
The other two accelerated as well
Analog Devices, the Massachusetts maker of data converters, amplifiers and power-management parts, reported its first $4bn quarter in August, revenue up 40% with gross margin at 67.3%. Industrial revenue grew 53%, and communications — now about 80% data center — grew 84%. Asked on the August 19 call how durable that is, the finance chief grounded it in "bookings momentum, design activity, and pipeline visibility," and said it was not "hopes and dreams." Management also said book-to-bill was "not unusually elevated" and that customers are "running lean," which is the same demand-not-inventory signal NXP's channel weeks give.
Texas Instruments grew 22.8% to $5.46bn in the June quarter with gross margin at 61.4%, up from 57.9%. Far from a fixed-cost squeeze, Dallas cut 2026 capital spending guidance to $2-3bn against depreciation of $2.2-2.4bn, targeting more than $8 of free cash flow per share, and reported $2.74bn of quarterly free cash flow helped by $1.6bn of CHIPS Act incentives. Its capital event is the $7.5bn agreement to buy Silicon Labs, announced February 4 and closing in the first half of 2027.
One repricing, three outcomes
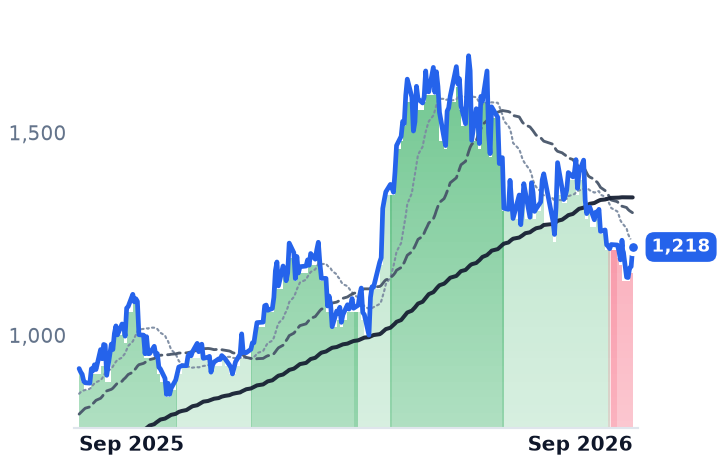
All three peaked within days of June 18 and fell into September — NXP 27.2%, Texas Instruments 17.4%, Analog Devices 13.5% — in a duration repricing already visible across power-analog names, with the 30-year Treasury at a 19-year high in August and the Federal Reserve raising rates on September 16. Only NXP's decline hardened into a confirmed downtrend, on September 9.
What the businesses earn and what the prices say now diverge unevenly. Texas Instruments is the most expensive of the three at 31.3x forward earnings, with the lowest free-cash-flow yield at 2.2% and a consensus that models 2029 earnings of $11.32 a share below 2028's $12.04 — a de-rating with an argument behind it. Analog Devices gave up roughly 13% of its multiple of gross profit in a month while trailing gross profit grew 51%, yet at 18.4x forward gross profit it remains the richest of the three on that measure. NXP, at 7.2x forward gross profit, 13.3x enterprise value to earnings before interest, taxes, depreciation and amortization against Analog Devices' 29.1x, and a 5.1% free-cash-flow yield, is the one whose price contains no recovery at all.
The risk is that NXP's meters are self-reported and its next print is not yet scheduled. Texas Instruments reports on October 20, guided to $5.65-6.15bn — the first outside check on whether industrial and automotive orders held through the quarter that repriced them.