

Lamb Weston Sold 7% More Potatoes in Fiscal 2026 and Made 11% Less Operating Profit
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
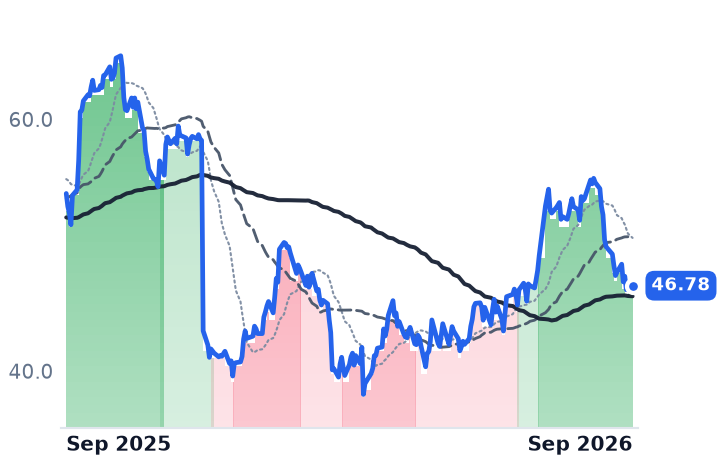
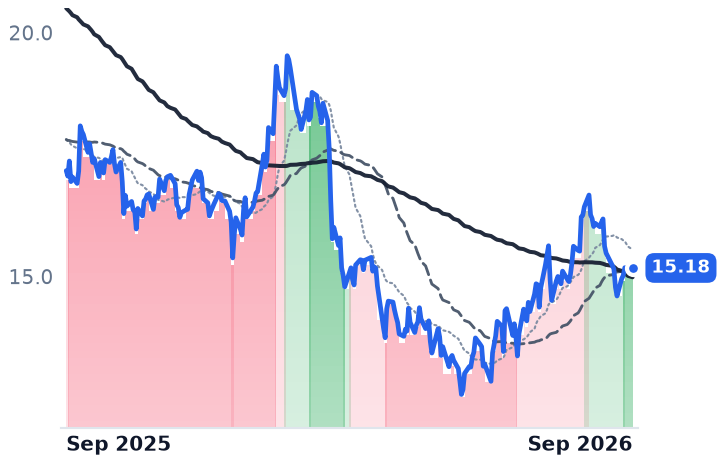
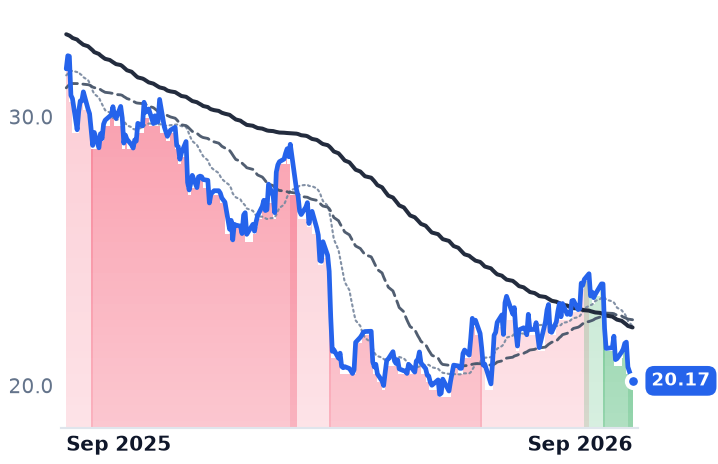
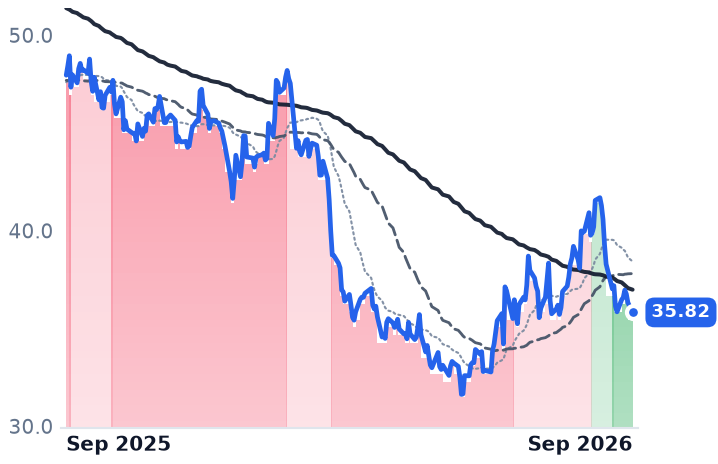
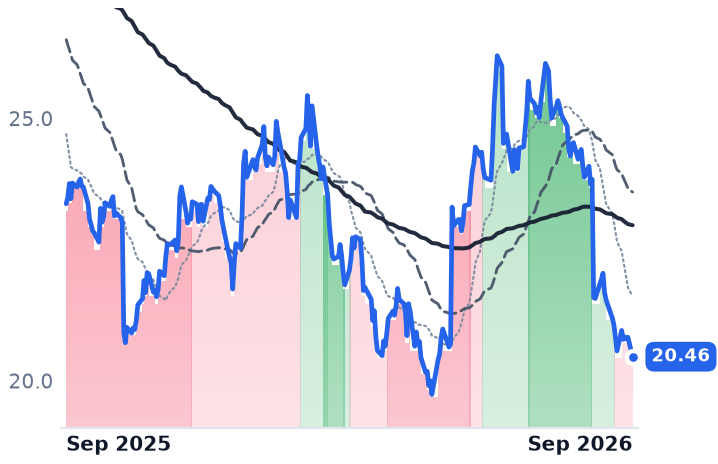
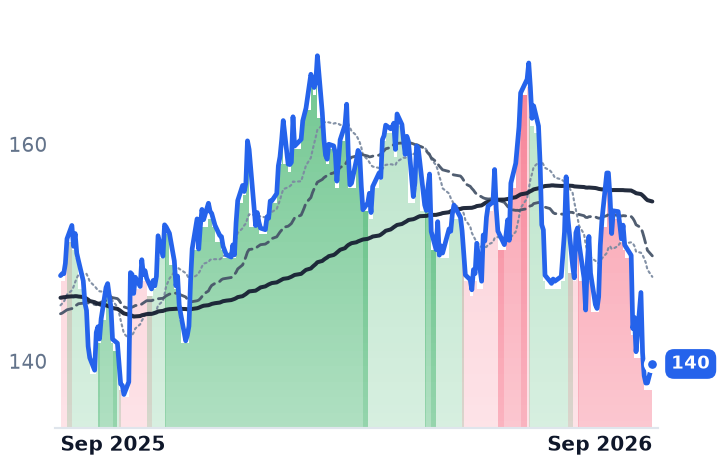
Frozen food's September selloff started at a company that sells almost no frozen food: Campbell's cut its dividend on September 3, and Lamb Weston and Conagra fell the same day with nothing of their own to report. Ten days on, the three have split — Conagra has recovered while the other two kept sliding.
Lamb Weston is where the disagreement sits. It is the only one of the three growing volume, with pounds up 7% in fiscal 2026, and the only one that handed the gain back in price, with price/mix down 6% and diluted earnings of $2.08, less than half fiscal 2024's. It is also the most expensive frozen name, at 15.6x forward earnings against Nomad Foods' 7.4x. Its fiscal first quarter lands October 6.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LW | Lamb Weston | Frozen & Prepared Foods | 🌱 Emerging Bull | −14.6% | −13.5% |
CAG | Conagra Brands | Frozen & Prepared Foods | 🌱 Emerging Bull | −9.0% | −11.6% |
CPB | Campbell Soup | Frozen & Prepared Foods | 🌱 Emerging Bull | −16.5% | −36.5% |
| Compared against · context, not the story | |||||
NOMD | Nomad Foods | Frozen & Prepared Foods | 🌱 Emerging Bull | −12.8% | −16.5% |
GIS | General Mills | Cereals & Breakfast | 🌱 Emerging Bull | −12.5% | −25.3% |
HRL | Hormel Foods | Meat & Protein Processing | 🌱 Emerging Bull | −15.1% | −12.5% |
TSN | Tyson Foods | Meat Processing | 🔴 Cont. Bear | −9.9% | −1.2% |
KHC | The Kraft Heinz | Condiments & Sauces | 🌱 Emerging Bull | −5.2% | −4.7% |
SJM | The J. M. Smucker | Pet Food & Nutrition | 🟢 Cont. Bull | −4.0% | +15.4% |
DPZ | Domino's Pizza | Quick Service - Pizza | 🔴 Cont. Bear | −15.4% | −29.9% |
WEN | The Wendy's | Quick Service - Burgers & Sandwiches | 🌱 Emerging Bull | −24.1% | −25.4% |
MCD | McDonald's | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −9.0% | −17.2% |
YUM | Yum! Brands | Quick Service - Pizza | ⚠️ Emerging Bear | −11.2% | −5.5% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.4% | +16.8% |
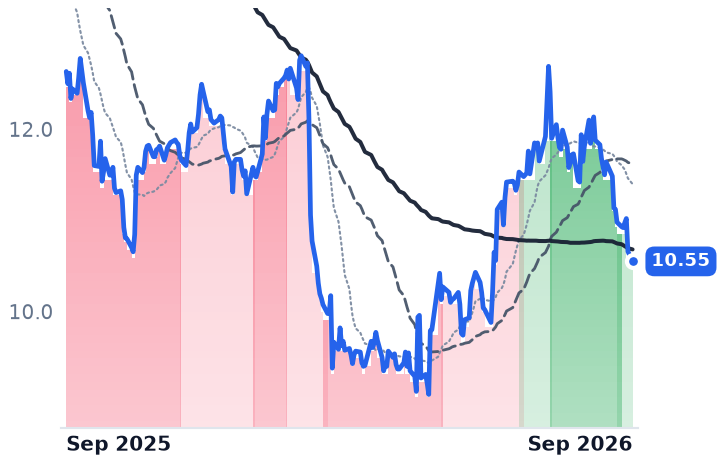
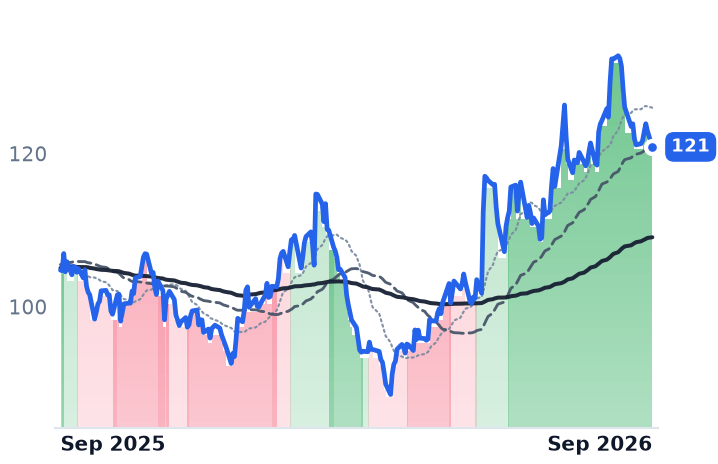
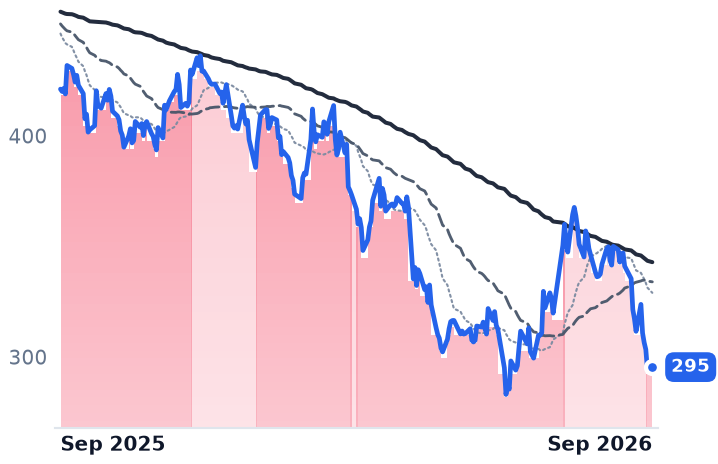
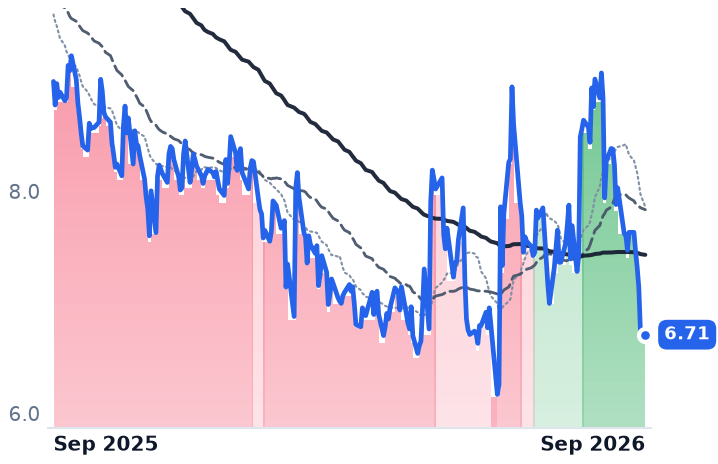
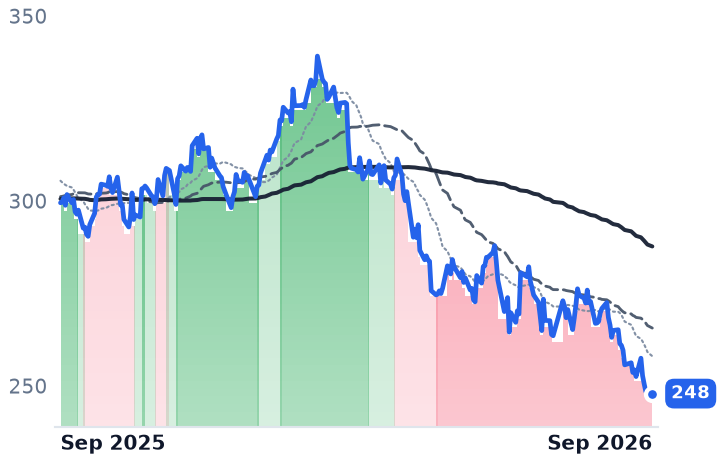
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LW | $6.5B | 22.5x | 15.6x | 1.0x | 1.0x | 4.8x | 4.9x | 10.6x | 9.8% |
CAG | $7.1B | n/m | 10.3x | 0.6x | 0.7x | 2.6x | 2.7x | n/m | 13.8% |
CPB | $5.9B | 14.9x | 11.8x | 0.6x | 0.6x | 2.2x | 2.2x | 10.0x | 11.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOMD | $1.5B | 10.5x | 7.4x | 0.4x | 0.5x | 1.6x | 1.9x | 10.2x | 15.9% |
GIS | $17.6B | 8.1x | 9.6x | 1.0x | 1.0x | 2.9x | 2.9x | 10.1x | 9.4% |
HRL | $11.5B | 33.3x | 14.1x | 0.9x | 0.9x | 6.1x | 6.1x | 15.5x | 6.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TSN | $23.4B | 51.3x | 16.3x | 0.4x | 0.4x | 6.4x | 6.3x | 12.2x | 5.2% |
KHC | $27.2B | n/m | 11.1x | 1.1x | 1.1x | 3.3x | 3.3x | n/m | 14.5% |
SJM | $10.7B | n/m | 10.1x | 1.2x | 1.2x | 3.7x | 3.6x | n/m | 9.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DPZ | $11.1B | 18.9x | 17.7x | 2.2x | 2.1x | 5.5x | 5.3x | 16.2x | 5.9% |
WEN | $1.3B | 10.2x | 13.2x | 0.6x | 0.6x | 2.1x | 2.1x | 10.3x | 20.7% |
MCD | $176.1B | 20.1x | 19.2x | 6.4x | 6.2x | 11.1x | 10.9x | 15.3x | 4.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
YUM | $38.0B | 17.2x | 21.0x | 4.4x | 4.3x | 9.5x | 9.3x | 17.2x | 4.4% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LW | Revenue | +2.7% | −0.4% | +1.6% |
| EPS | −10.9% | +9.0% | +11.5% | |
CAG | Revenue | −3.2% | −3.9% | −0.4% |
| EPS | −26.7% | −14.9% | +3.6% | |
CPB | Revenue | −4.9% | −2.9% | −0.5% |
| EPS | −26.0% | −21.7% | +6.9% | |
NOMD | Revenue | −3.0% | +2.0% | −0.2% |
| EPS | −12.6% | +4.7% | +10.0% | |
GIS | Revenue | −5.6% | −2.5% | +1.0% |
| EPS | −18.2% | −4.5% | +4.0% | |
HRL | Revenue | +0.1% | +1.8% | +1.4% |
| EPS | +9.0% | +5.7% | +5.6% | |
TSN | Revenue | +3.1% | +0.8% | +2.4% |
| EPS | +6.0% | +12.4% | +26.5% | |
KHC | Revenue | −2.0% | +0.6% | +1.1% |
| EPS | −18.6% | +1.4% | +4.4% | |
SJM | Revenue | +3.2% | +1.0% | +1.5% |
| EPS | −10.2% | +10.4% | +8.5% | |
DPZ | Revenue | +5.4% | +2.4% | +3.9% |
| EPS | +7.6% | +9.8% | +8.0% | |
WEN | Revenue | +1.3% | −0.5% | +3.3% |
| EPS | −41.7% | +3.9% | +11.8% | |
MCD | Revenue | +5.7% | +5.1% | +4.2% |
| EPS | +6.4% | +8.0% | +7.0% | |
YUM | Revenue | +9.4% | +3.2% | +5.8% |
| EPS | +8.1% | +10.2% | +11.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Lamb Weston reaches its next earnings date as the odd name in frozen food: the only large frozen manufacturer whose volumes are still climbing, and the only one whose shares carry a premium for it. The company said on September 8 that it will report fiscal 2027 first-quarter results on October 6.
Nothing about how it earns money resembles a grocery shelf. Lamb Weston, based in Eagle, Idaho, sells frozen potatoes — fries, commercial ingredients, appetizers — by the pound to restaurant chains and foodservice distributors, with a smaller retail business under Grown in Idaho, Alexia and customer private labels. Its prices are set in an annual contracting season rather than at a checkout, so a year's economics are largely fixed before the year begins. In fiscal 2026 that produced net sales up 2% to $6.6bn, with volume up 7% and price/mix down 6%. Operating profit fell 11%. Gross margin came in at 20.6%, against 27.3% two years earlier, and diluted earnings per share of $2.08 were less than half fiscal 2024's $4.98.
Pounds bought with price
"At the end of the day, we're winning with customers and growing and we expect some volume growth," chief executive Mike Smith told investors on the July 24 call. He is right about the pounds: North American sales rose 3% on a 9% volume increase from customer retention and contract wins. The cost of those wins arrives as price. On the same call, management traced fiscal 2027's "modest price mix investments" largely to "decisions made in the last contracting season".
The occasion those pounds serve is shrinking. US quick-service restaurant traffic fell 1.2% year on year in the second quarter of 2026, and visits shorter than ten minutes — the drive-thru trip where fries attach — dropped 6.8% in May. Lamb Weston is answering by removing capacity, not filling it: its board approved closing the Broekhuizenvorst plant in the Netherlands on June 1, affecting about 110 employees, at a pre-tax cost of $80–110m falling mostly in the year to May 2027 — two years after it opened a plant at Kruiningen, roughly 195km away. Nor is the raw material reliably getting cheaper: north-west European growers cut plantings about 11% and Idaho acreage is down some 15,000 acres, which argues against another round of contract-price relief.
Guidance for fiscal 2027 is sales flat to up 1%, adjusted EBITDA of $1.1–1.2bn against $1,147m delivered, adjusted EPS of $2.95–3.25 and capital spending cut to $380–410m. Net debt ended the year at $3.8bn, 3.4x adjusted EBITDA. Consensus of $3.02 sits inside that guidance rather than above it.
Priced as the survivor
Lamb Weston trades at 15.6x forward earnings against 22.5x trailing, and 10.6x trailing enterprise value to EBITDA, the fitter comparison given the leverage. That makes it the most expensive of the frozen names: Nomad Foods is at 7.4x forward earnings, Conagra 10.3x, Campbell's 11.8x. Sell-side targets have converged on the quote — Bernstein cut to $46 from $65, BNP Paribas Exane to $48 with a downgrade, Barclays to $55.
Someone else's dividend
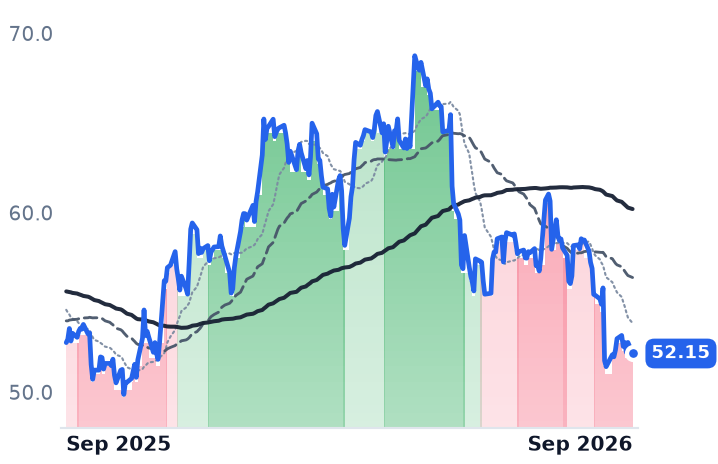
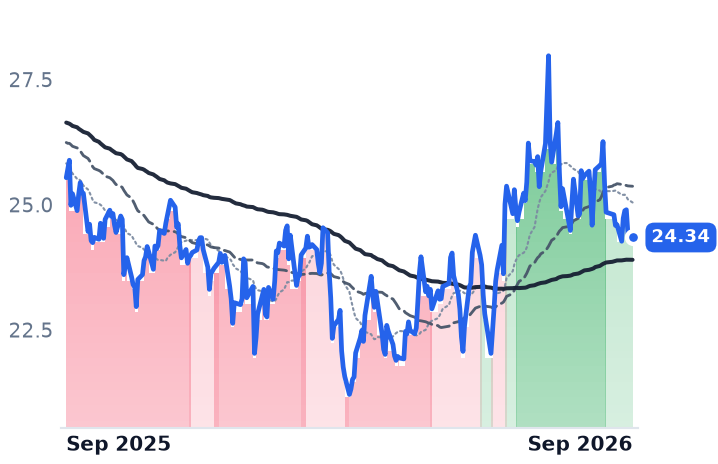
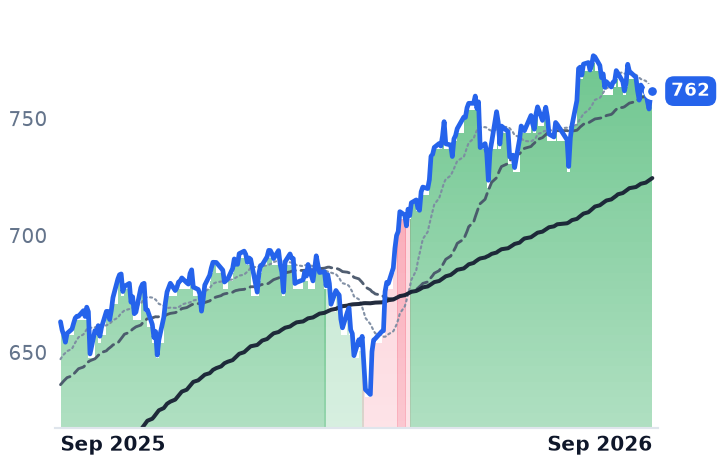
The September leg down began elsewhere. On September 3, Campbell's — soup, Rao's, Pepperidge Farm, Goldfish — cut its quarterly dividend 36% to $0.25 and guided fiscal 2027 adjusted EPS to $1.65–1.80 against the $1.86 analysts expected. "Reducing the dividend is obviously a difficult decision, but it is unfortunately a necessary decision," chief executive Mick Beekhuizen said on that day's call. Campbell's fell 7.0%; Lamb Weston fell 3.8% and Conagra 3.5% with no news of their own. Campbell's is barely a frozen business — in the six months to February 1, Meals & Beverages earned $549m of segment operating profit against Snacks' $190m — and the selling was not frozen-specific either: over the past 30 days General Mills fell 10.4%, Hormel 14.3%, Tyson 10.8%, Domino's 13.6% and Wendy's 25.6%, while the S&P 500 rose 1.1%.
Conagra, which sells Birds Eye, Healthy Choice and Marie Callender's at retail shelf prices, is the mirror of Lamb Weston's contracted economics. Its fiscal 2026 revenue fell 2.9% to $11.28bn, gross margin slipped to 23.9% from 27.7% two years earlier, and a roughly $2bn impairment produced a $1.92bn net loss. It halved its dividend in July, ending 51 straight years of maintained payments, and guides fiscal 2027 volume down mid-single digits while still taking inflation-justified frozen pricing at elasticities above historical levels. Private label is the reason that hurts: US store-brand unit share hit a record 23.8%. Nomad Foods, the European owner of Birds Eye and Findus, shows the same split from the other side — its second-quarter volume fell 5.9% even as chief executive Dominic Brisby told investors on August 13 that "the frozen category in our markets year-to-date, it's up 3.4% in value terms and up 1.6% in volume terms." Frozen is not breaking; brands are losing share within it.
The shared shock has since worn off. Since September 11 Conagra has risen 4.0% while Lamb Weston has fallen 2.2% and Campbell's 3.9%, leaving Campbell's at $20.18, within 1% of its two-year low.
What the business earns and what it borrowed
Over twelve months, Lamb Weston's de-rating is earned at the profit line: the same $6.6bn of revenue now carries less than half the earnings of two years ago, and the cheaper crop has yet to reach gross margin. September added a further leg that no Lamb Weston fact explains — it came from a soup company's payout decision spreading across every food name a screen groups with it. What the remaining premium over Conagra and Nomad prices is a single proposition: that pounds bought with margin turn back into margin once the contracting cycle turns. Fiscal 2027 guidance promises no such thing this year.
October 6 is the first read on whether the pounds keep coming and the price stops falling. Lamb Weston has spent two years proving it can buy volume; it has yet to show what the volume is worth.