

Albemarle Prices 40% of Its Lithium Off an Index That Lags Three Months. The Index Broke
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two lithium producers reported their best quarters in four years in August and have since given back roughly a fifth of their market value, with no guidance cut, no downgrade of volumes and no company event behind it. Albemarle's June-quarter gross margin was 33.9% against 14.8% a year earlier; SQM's was 51.1% against 24.3%, on revenue up 137%.
What moved was the 2027 supply balance: Australian mines restarted, Chinese carbonate futures rolled over from their late-August high, and both companies are paid a lagged, index-referenced version of that benchmark. The shares are marking a realised price that has not yet been reported.
The two are not equally exposed. Consensus already models Albemarle's earnings falling 14.6% in 2027 from a 2026 peak, so its cheap forward multiple rests on a peak denominator; SQM's 2027-28 estimates are flat to higher, and its iodine business, 16% of first-half gross profit at a record $73.4 per kilogram, has no battery in it at all.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
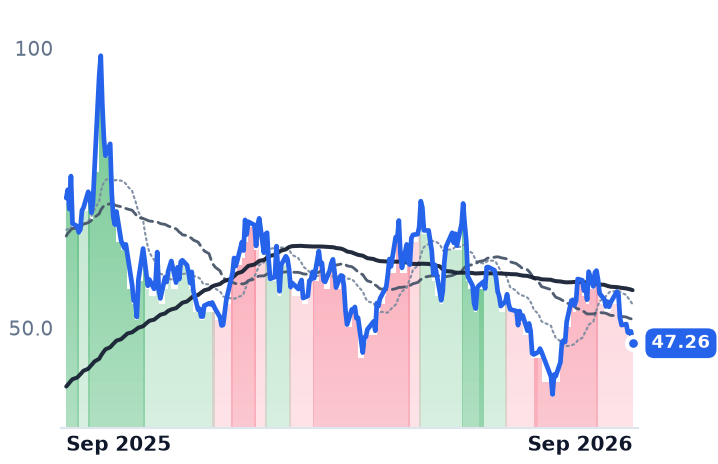
ALB | Albemarle | Lithium & Battery Materials | 🔴 Cont. Bear | −19.9% | +41.9% |
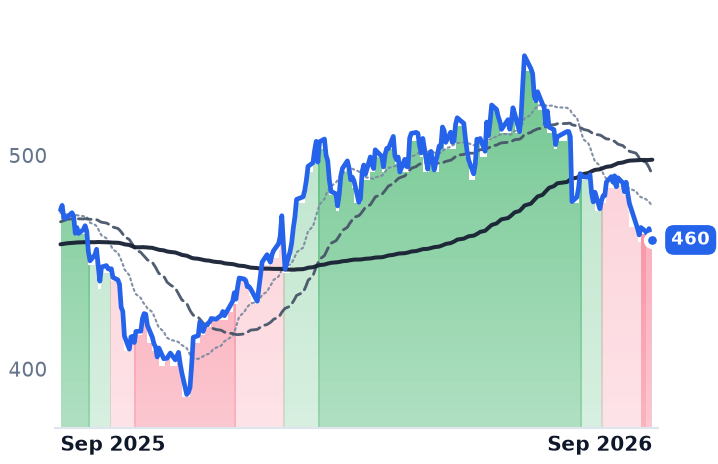
SQM | Sociedad Química y Minera de Chile | Lithium & Battery Materials | ⚠️ Emerging Bear | −15.4% | +60.9% |
| Compared against · context, not the story | |||||
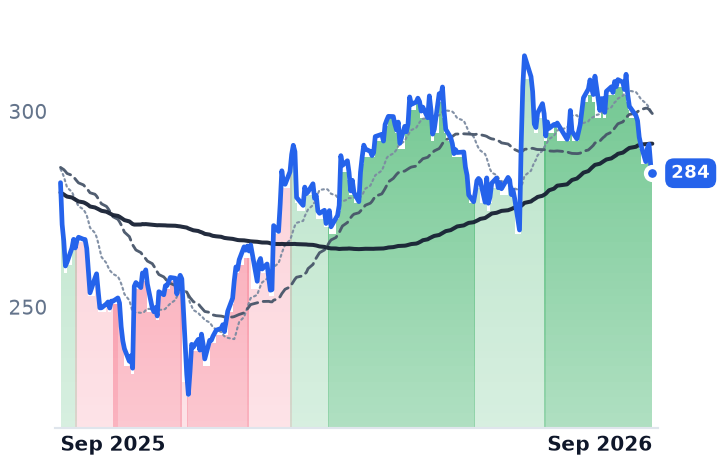
SGML | Sigma Lithium | Battery & Energy Transition Materials | ⚠️ Emerging Bear | −18.3% | +59.0% |
LAC | Lithium Americas | Battery & Energy Transition Materials | 🔴 Cont. Bear | −8.0% | −13.3% |
MP | MP Materials | Rare Earth & Magnets | 🔴 Cont. Bear | −17.7% | −35.5% |
LIN | Linde | Industrial Gases | ⚠️ Emerging Bear | −6.0% | −3.0% |
APD | Air Products and Chemicals | Industrial Gases | 🟢 Cont. Bull | −7.2% | +0.9% |
12-month price & trend
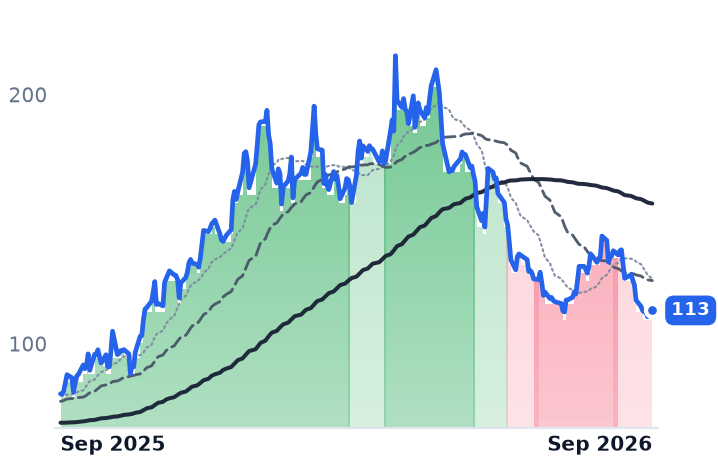
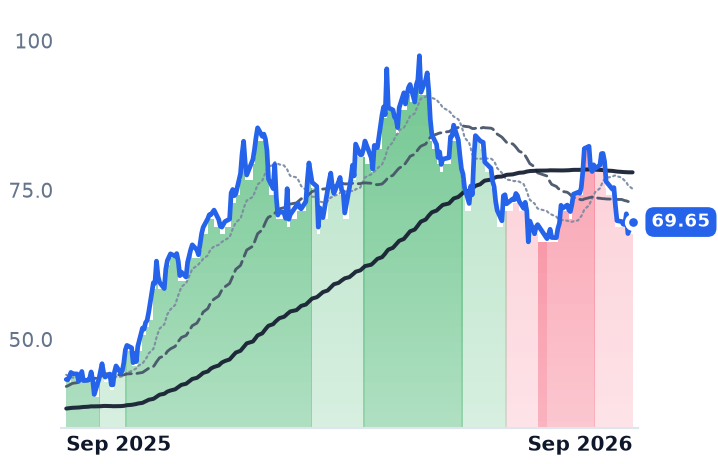
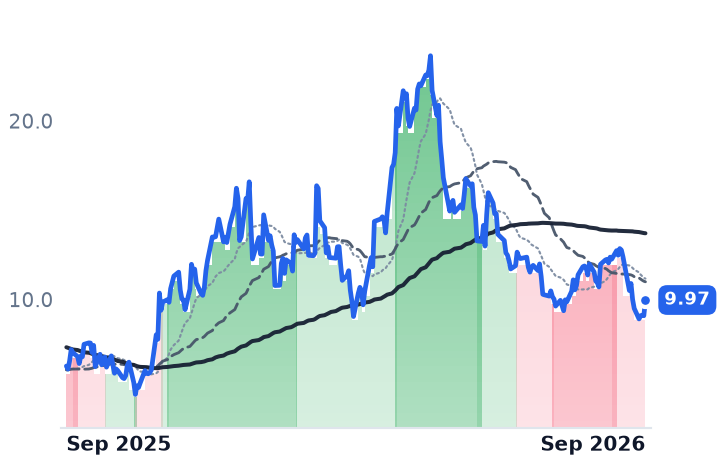
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALB | $13.4B | 236.3x | 9.9x | 2.3x | 2.2x | 9.5x | 9.1x | 11.2x | 10.0% |
SQM | $19.9B | 14.4x | 9.5x | 3.0x | 2.4x | 7.0x | 5.6x | 7.4x | 9.7% |
SGML | $1.9B | n/m | 16.7x | 18.1x | 5.3x | 67.2x | 19.6x | 345.0x | 0.1% |
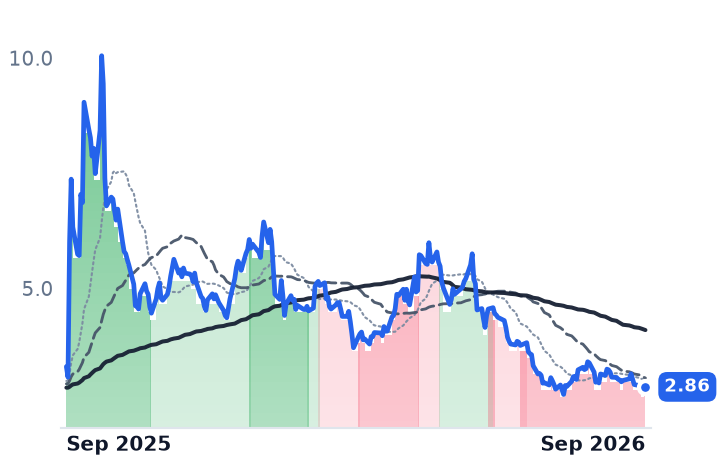
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LAC | $1.1B | n/m | — | n/m | 16.1x | — | — | n/m | -90.6% |
MP | $10.5B | n/m | 522.6x | 34.2x | 23.4x | — | — | 177.5x | -4.8% |
LIN | $224.5B | 31.2x | 27.1x | 6.3x | 6.2x | 13.9x | 13.6x | 18.4x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APD | $67.9B | n/m | 22.7x | 5.4x | 5.3x | 16.8x | 16.6x | 65.6x | 3.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ALB | Revenue | +20.9% | +1.0% | +2.1% |
| EPS | −1568.8% | −14.6% | +10.0% | |
SQM | Revenue | +86.6% | −3.3% | +1.6% |
| EPS | +233.7% | +1.2% | +0.2% | |
SGML | Revenue | +206.1% | +37.8% | +59.1% |
| EPS | −767.1% | +27.9% | −86.8% | |
LAC | Revenue | — | −30.6% | +697.5% |
| EPS | −82.0% | −0.8% | −126.8% | |
MP | Revenue | +90.7% | +75.5% | +24.3% |
| EPS | −129.5% | +723.3% | +57.6% | |
LIN | Revenue | +7.2% | +4.8% | +5.5% |
| EPS | +8.8% | +9.6% | +9.9% | |
APD | Revenue | +6.0% | +5.7% | +6.2% |
| EPS | +11.9% | +7.5% | +8.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Albemarle's battery-materials business earned $723m of adjusted segment profit in the June quarter, more than three times what it made a year earlier. Since August 21 the shares have fallen 22.6%, and nothing the company has published explains it.
What repriced was not this year's earnings but next year's balance. Mineral Resources restarted the Bald Hill mine and Core Lithium restarted Finniss, Chinese futures peaked at RMB162,500 a tonne (about $24,000) during 24-27 August and then slid on firming expectations that Jiangxi mines restart, and lithium futures went on to a five-month low as traders handicapped a 2027 glut. That matters to these two specifically because neither is paid the spot price. About 40% of Albemarle's estimated 2026 salts volumes sell under index-referenced contracts carrying floors, sometimes ceilings, and a three-month price lag — so a September break in the index reaches the income statement in the fourth quarter. The equity is marking a realised price nobody has reported yet.
What a lithium dollar actually is at Albemarle
Albemarle, the Charlotte specialty chemicals group that sells lithium carbonate, hydroxide and chloride into battery supply chains alongside bromine flame retardants and refining catalysts, shipped 65,000 tonnes of lithium carbonate equivalent at $19.53 per kilogram in the June quarter, volumes up 11% and price up 60%. Management put that realised figure roughly 15% below prevailing market pricing, the gap being contract lag plus the dilutive effect of selling spodumene concentrate beside salts. Revenue rose 31% to $1.74bn, gross margin reached 33.9% against 14.8%, and the full-year Specialties outlook was raised. "We continue to see resilient demand fundamentals across our core markets, including energy storage, electric vehicles, and semiconductors," chief executive Kent Masters said in the August 6 release.
The balance sheet behind that is already defensive. First-half capital expenditure was $170m, down $132m year on year — cut before the rally and not restored. The mandatory convertible preferred that raised about $2.3bn at a 7.25% coupon converts on March 1, 2027, and diluted share count has already climbed from 117.7m to 136.2m as earnings turned positive. Albemarle owns 49% of Talison, operator of Greenbushes, where a June 9 fire pushed the third chemical-grade plant's ramp into the first quarter of 2027 while concentrate guidance held. Its conversion spread is squeezed from both ends when the index falls: feedstock it buys from a venture it minority-owns, plants whose unit cost is set by utilisation.
SQM's cushion, and the landlord
SQM, the Santiago brine producer of lithium, iodine and potassium nitrate fertilizers, had a bigger quarter still: revenue up 137% to $2.47bn, gross margin 51.1% against 24.3%, lithium realised near $21.80 per kilogram. It raised its 2026 global demand forecast by 200,000 tonnes on August 19 rather than trimming it. But lithium is 78% of consolidated first-half gross profit against iodine's 16% — the iodine book, at a record $73.4 per kilogram, is a floor rather than the bulk of the business.
Chile takes a widening cut on the way up. The 2018 lease with development agency CORFO carries a progressive royalty rising to a marginal 40% above $10,000 a tonne, and payments to the state exceeded $1.6bn in the first half against $4.23bn of revenue. Under the Codelco partnership, the state's share of operating margin on new production runs near 70% to 2030 and 85% thereafter. A schedule that escalates with price also relaxes when price falls — an automatic stabiliser Albemarle does not have.
The verdict
The physical market moved far less than the equities. Cochilco's August average of $19,525 a tonne is 12.2% off the May peak but still more than double the 2025 average; a single-digit dip in Chinese carbonate in mid-September produced a 5.68% fall in SQM in one session. Nothing in either reported quarter earns that. What the selloff does earn is the arithmetic ahead: lagged contracts guarantee fourth-quarter realised prices follow the index down even if spot holds, and consensus has Albemarle at $11.48 a share this year and $9.81 next, so its 9.9x forward multiple is struck on a denominator analysts expect to be a cycle top. SQM's forward estimates are flat to slightly higher into 2028 at a similar multiple. The pair is not one trade. One is a converter with dilution arriving in March; the other is the low-cost brine producer whose landlord absorbs part of the fall.
SQM's own management supplied the bear case nobody needed a futures screen for: battery-storage cells are being produced faster than they are deployed, and a 12- to 18-month oversupply is possible if approvals catch up too slowly. The next print is the first to contain any of September, and the only line on it that settles this is the price per kilogram Albemarle actually collected.