

Warrior Met Sold Record Tons at $137.82 as Its Cash Cost Fell to $92.53; Alpha's Rose
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A coking-coal producer whose margin per ton roughly doubled year on year has lost a fifth of its market value in three weeks — and the price of the coal it sells barely moved. Warrior Met's June-quarter revenue rose 70.6% and adjusted earnings before interest, taxes, depreciation and amortization reached $156.9m, with the $1.02bn Blue Creek mine already built and its longwall running since October 2025. Alpha Metallurgical, shipping nearly identical tonnage, cut volume guidance, raised cost guidance and earned $25.6m. Ramaco's collapse is not a coal move at all. One segment label covers three businesses sitting at very different points on the cost curve, and only Warrior's decline lacks an explanation in its own accounts.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
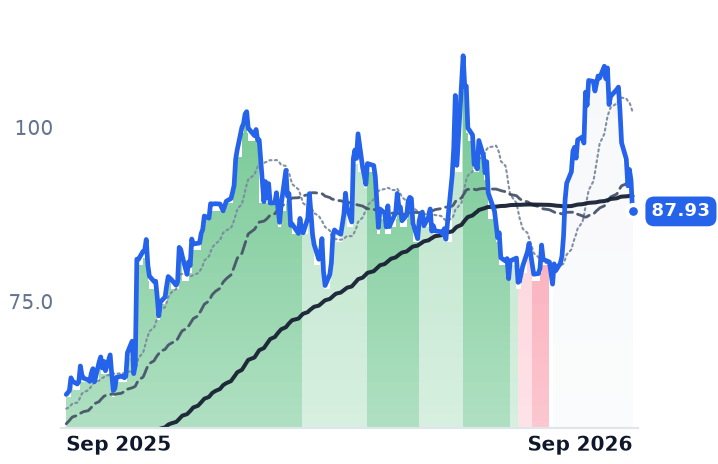
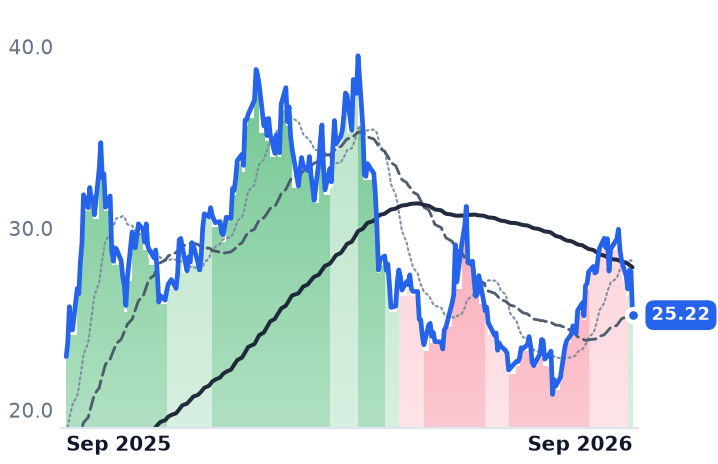
HCC | Warrior Met Coal | Metallurgical Coal Producers | ⚠️ Emerging Bear | −17.6% | +42.6% |
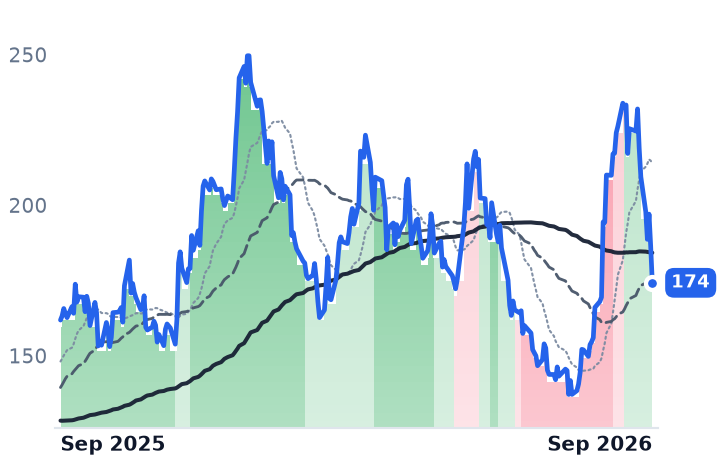
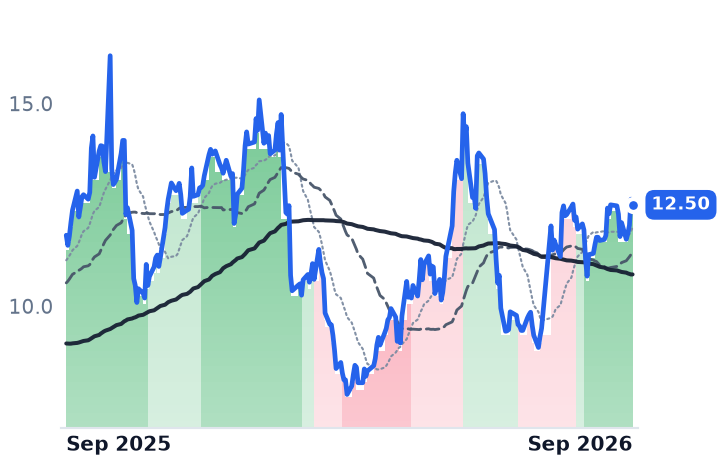
AMR | Alpha Metallurgical Resources | Metallurgical Coal Producers | ⚠️ Emerging Bear | −17.0% | +7.6% |
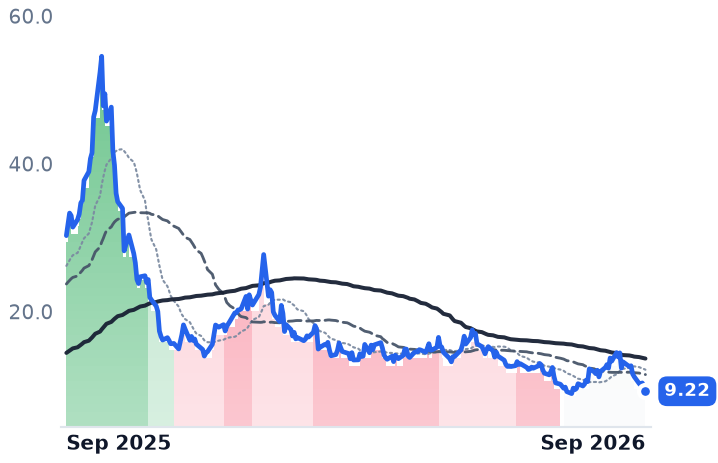
METC | Ramaco Resources | Metallurgical Coal Producers | 🔴 Cont. Bear | −22.5% | −69.6% |
| Compared against · context, not the story | |||||
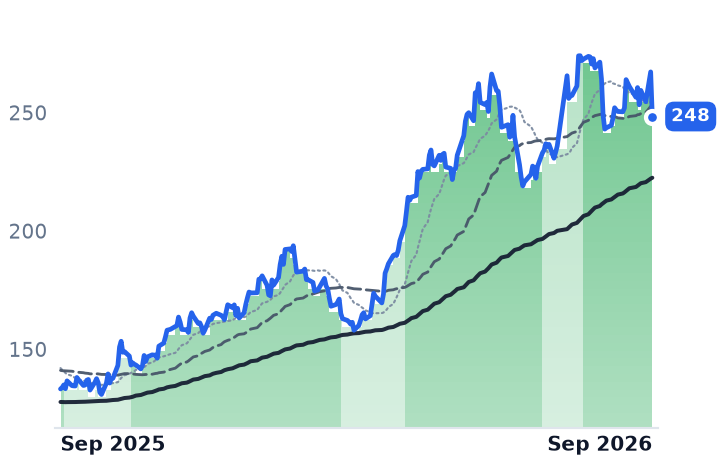
NUE | Nucor | Integrated Steelmakers | 🟢 Cont. Bull | +1.9% | +86.4% |
BTU | Peabody Energy | Thermal Coal Producers | ⚠️ Emerging Bear | −8.7% | +9.9% |
CLF | Cleveland-Cliffs | Flat-Rolled Steel | 🟢 Cont. Bull | +10.9% | +6.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HCC | $4.6B | 21.1x | 14.0x | 2.8x | 2.3x | 6.6x | 5.5x | 10.1x | 0.1% |
AMR | $2.2B | n/m | — | 1.1x | 1.0x | 33.1x | 32.3x | 17.6x | -0.1% |
METC | $496.1M | n/m | — | 1.0x | 0.9x | 22.5x | 20.3x | n/m | -27.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NUE | $56.6B | 19.8x | 13.0x | 1.6x | 1.4x | 10.1x | 9.0x | 10.9x | 2.8% |
BTU | $3.5B | n/m | — | 0.9x | 0.8x | 39.6x | 37.1x | 11.8x | 13.0% |
CLF | $5.9B | n/m | — | 0.3x | 0.3x | — | — | 101.5x | -17.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
HCC | Revenue | +54.0% | +9.9% | +4.9% |
| EPS | +524.3% | +30.3% | +13.3% | |
AMR | Revenue | −0.5% | +21.6% | +5.0% |
| EPS | −22.7% | −527.2% | +35.4% | |
METC | Revenue | +2.9% | +21.3% | +25.3% |
| EPS | −3.8% | −94.7% | −1238.4% | |
NUE | Revenue | +23.9% | +1.9% | +0.0% |
| EPS | +140.4% | +2.7% | −4.8% | |
BTU | Revenue | +11.1% | +8.3% | −0.7% |
| EPS | −59.9% | −1581.4% | +3.9% | |
CLF | Revenue | +9.2% | +2.3% | +0.6% |
| EPS | −78.7% | −155.5% | +40.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Warrior Met Coal sold a record 3.7m short tons of steelmaking coal in the June quarter, its fourth consecutive quarterly record, and dug each one out of the ground for less than it spent a year earlier. The Alabama longwall miner, which ships premium low-volatility coal to blast-furnace steelmakers in Europe, South America and Asia, reported an average net selling price of $137.82 per short ton against a cash cost of $92.53 delivered to port — roughly $45 of margin on every ton, where a year earlier the same two lines left barely $29.
Since the end of August, Warrior's shares have fallen about 19%, to $87.93 and a market value of $4.64bn. Over the same stretch the Australian hard coking coal benchmark did essentially nothing: it held near $271 a ton on September 17, within a hair of the level it reached during an August spike driven by safety inspections at Chinese mines. Coking coal is sold at an index price and earned as a netback after rail freight and port charges, against a cash cost that is mostly fixed. Volume and position on the cost curve set the margin. That is why the three American producers filed under one heading now look nothing alike.
The mine that is already paid for
Warrior's revenue has accelerated for four straight quarters, reaching $509.7m in the June quarter with gross margin of 31.9% against 7.0% a year before. Net income was $87.4m against $5.6m. The reason is Blue Creek: the company had spent $1,022.9m on the growth mine through March against a budget of $995m to $1.075bn, and its longwall started in October 2025, eight months early, with nameplate capacity lifted 25%. "The second quarter marked a key inflection point as we clearly realized the incremental earnings and cash flow contributions of Blue Creek," chief executive Walter Scheller told investors on August 5. Metallurgical coal also became eligible in 2026 for a federal critical-minerals tax credit worth 2.5% of production costs, which Warrior cited in its cost decline. Consensus has 2026 earnings of $6.30 a share against $1.08 last year; the stock trades at 14.0 times that, versus 21.1 times trailing.
The one the market read correctly
Alpha Metallurgical Resources, which runs nineteen mines across Virginia and West Virginia, shipped 3.5m tons and earned $25.6m. Revenue fell 10.4% to $492.9m and operating margin was minus 2.1%, a fourth straight quarter of operating losses. Realised met pricing slipped to $118.71 a ton against cost guidance raised roughly $7 to $103–107 — twelve to sixteen dollars of margin where Warrior has forty-five. Alpha cut full-year volumes by about 1m tons after an 80-mph storm in June wrecked one of two stacker reclaimers at its Atlantic export terminal. "Everyone knew there was going to be High-Vol supply coming on. But at the same time, everybody expected the steel market globally to be stronger than it is today," chief commercial officer Daniel Horn said on the August 7 call. "We need our customers to produce more steel, frankly." The buyback that once absorbed $1.2bn at an average $166.18 a share spent $13.5m last quarter. At $174.22 the shares carry 1.48 times book and 17.6 times trailing EV/EBITDA — higher than Warrior's 10.1 times on a sixth of the cash earnings.
Ramaco is not in this argument
Ramaco Resources realised $116 a ton against a $99 cash cost for $5.7m of coal EBITDA. Its $496m Class A market value stands against roughly $23m of annualised coal earnings; the remainder is Brook Mine, a Wyoming rare-earth project whose Hatch assessment put capital spending at $3.2bn plus $0.8bn of contingency with first production in 2031. The shares are down 70% over twelve months and fell hardest on September 3, when Ramaco disclosed that Yorktown Energy Partners would distribute about a million shares to its partners. No steelmaker is on either side of that trade.
What the business earns and what it does not
Alpha's de-rating is paid for by its own income statement, and Ramaco's by a 2031 start date. Warrior's is not: cost per ton down, tons up, capital spent, guidance being met. The likelier reading is that the shares are being marked back to where the index sat before August rather than to anything mined in Alabama — the whole complex sold off together on September 18, Peabody and Nucor included. Note who won the year: Nucor, an electric-arc-furnace steelmaker that buys no coking coal at all, is up 85% over twelve months while Alpha, which feeds its blast-furnace competitors, is up 6%. The tariff protection landed on the steel, not on the coal beneath it. China's coke exports rose 14.4% in the first half, displacing seaborne demand at the margin, while India's imports climbed 32% to 73.53m tonnes — a tug-of-war neither producer controls.
What Warrior does control, it has already done. Ninety percent of Blue Creek's expected 2026 volume is under contract. The tons are sold; what remains unsettled is what anyone will pay for the company that mines them.