

Appian Will Retry Its Vacated $2.036bn Claim Against Pegasystems on January 11
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A courtroom holds an asset worth roughly three-quarters of Appian's equity value, and it finally has a date on the calendar. Appian's latest quarterly filing discloses that the Fairfax County Circuit Court has set the retrial of its vacated trade-secret award against Pegasystems to begin in January 2027 — superseding the position reported here a week ago, that no date had been set. Pegasystems carries no accrual for the matter.
Until the verdict, the operating business stands alone, and it is split down the middle. June-quarter adjusted EBITDA of $16.2m beat the $5–8m the company guided, while revenue growth eased to 19.1% and gross margin fell to 71.2%. Cloud net expansion of 115% is the one demand meter that held.
The profit inflection is earned. The re-rating — from 3.07x gross profit in early May to 4.77x — is not visible in the demand numbers.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
APPN | Appian | Low-Code & Process Automation | 🌱 Emerging Bull | −2.1% | +11.3% |
| Compared against · context, not the story | |||||
PEGA | Pegasystems | Low-Code & Process Automation | 🔴 Cont. Bear | +4.4% | −41.5% |
NCNO | nCino | Financial Services Software | 🌱 Emerging Bull | +2.1% | −30.6% |
PCOR | Procore Technologies | Specialized Enterprise Solutions | 🌱 Emerging Bull | −19.2% | −27.2% |
FRSH | Freshworks | Security & Compliance | 🌱 Emerging Bull | −5.6% | −6.5% |
BL | BlackLine | Financial Services Software | 🔴 Cont. Bear | −11.6% | −48.6% |
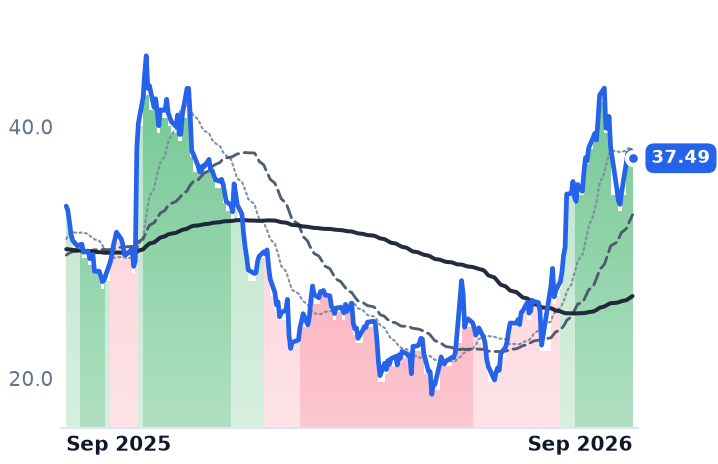
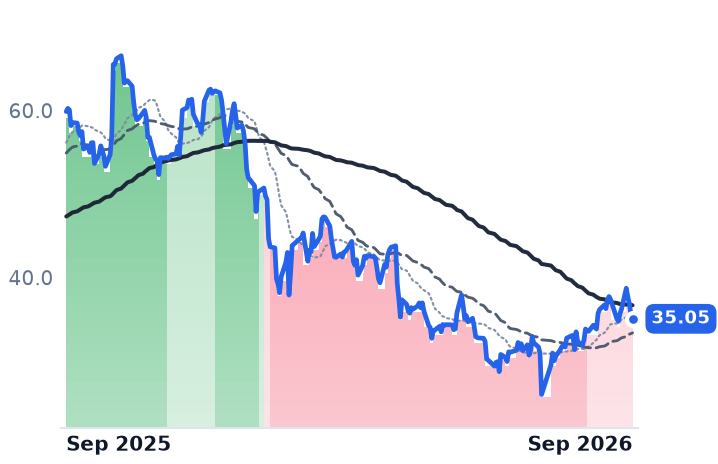
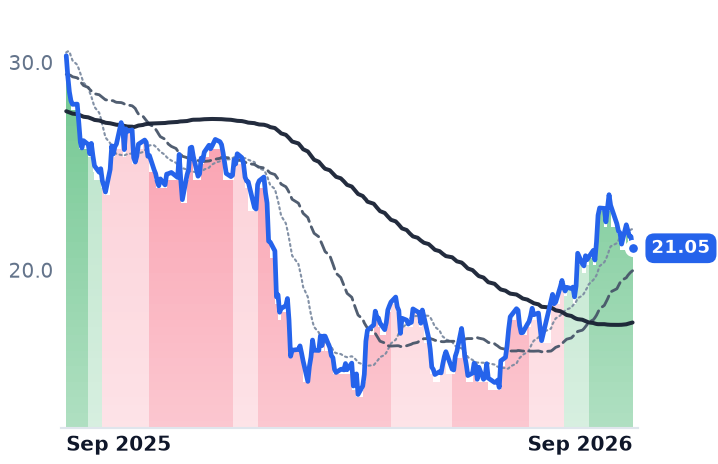
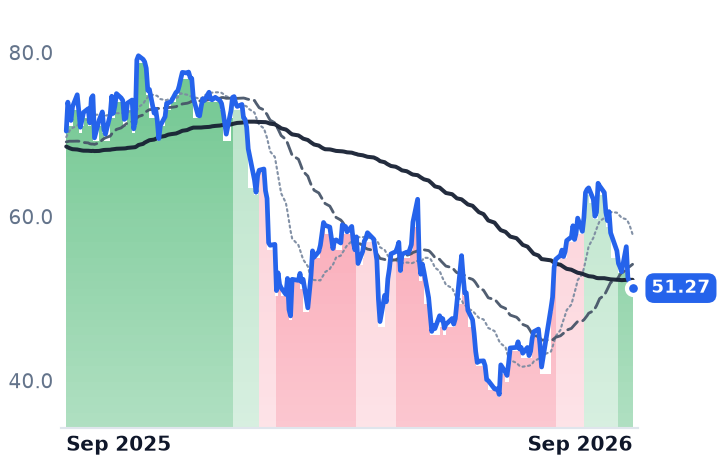
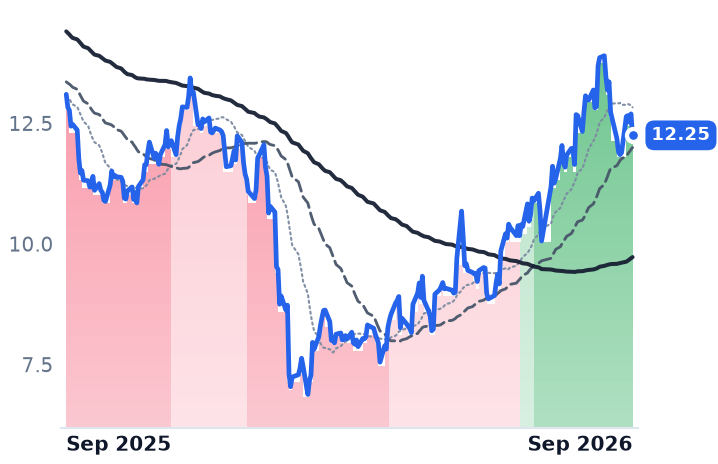
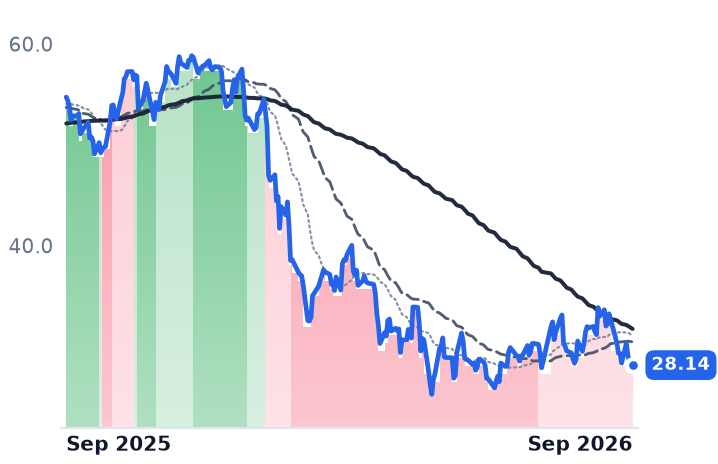
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APPN | $2.8B | n/m | 34.7x | 3.5x | 3.3x | 4.8x | 4.5x | 119.9x | 2.8% |
PEGA | $6.1B | 19.7x | 15.2x | 3.5x | 3.3x | 4.7x | 4.3x | 30.6x | 8.2% |
NCNO | $2.3B | 67.9x | 16.1x | 3.7x | 3.6x | 6.0x | 5.8x | 31.1x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCOR | $7.8B | n/m | 30.8x | 5.5x | 5.2x | 6.9x | 6.5x | 122.0x | 3.8% |
FRSH | $3.4B | 18.7x | 18.3x | 3.7x | 3.5x | 4.4x | 4.1x | 37.6x | 7.4% |
BL | $1.7B | 47.8x | 11.3x | 2.3x | 2.2x | 3.0x | 2.9x | 20.9x | 10.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APPN | Revenue | +19.1% | +10.8% | +7.4% |
| EPS | +104.0% | +31.1% | +11.4% | |
PEGA | Revenue | +8.8% | +9.2% | +8.7% |
| EPS | +18.0% | +7.8% | +6.2% | |
NCNO | Revenue | +9.8% | +9.0% | +8.5% |
| EPS | +25.2% | +44.5% | +20.0% | |
PCOR | Revenue | +15.3% | +13.9% | +14.4% |
| EPS | +24.1% | +46.2% | +20.2% | |
FRSH | Revenue | +15.6% | +14.2% | +15.4% |
| EPS | +5.4% | +24.0% | +18.4% | |
BL | Revenue | +9.5% | +10.5% | +10.2% |
| EPS | +19.4% | +11.9% | +17.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Appian's Form 10-Q for the June quarter discloses something its earlier filings did not: on May 7, 2026 the Fairfax County Circuit Court set a date for the retrial of the trade-secret claim it won, and then lost, against Pegasystems. The trial begins January 11, 2027. The position reported here on September 13 — that no trial date had been set — is superseded.
The stake is unusual. Appian, a McLean, Virginia company that sells a low-code process-automation platform to banks, insurers, drugmakers and government agencies, won a $2.036bn jury verdict against Pegasystems, a rival in enterprise workflow software, and watched the Supreme Court of Virginia vacate it on January 8 over a jury instruction that shifted the burden of proof on damages. That award is about 73% of Appian's $2.77bn market value. Pegasystems' own quarterly filing records no loss accrual for the matter. Nothing is collected or paid before a verdict, so the operating business has to be judged without it.
What an Appian dollar actually is
It is not paid for "low-code" as a category. It is a cloud subscription billed per user and per application across three tiers, negotiated contract by contract, with designer licenses priced far above ordinary business users. Chief financial officer Serge Tanjga told William Blair's growth conference that four verticals — financial services, insurance, life sciences and the public sector — supply 80% of annual recurring revenue, and that more than 70% of the business comes from customers spending over $1m a year: one bank replaced six fraud systems with a single workflow; a branch of the US military runs ammunition supply-chain work on it at roughly a million transactions a month.
Artificial intelligence reaches that revenue as a price increase rather than a product line. Putting AI into production requires the Advanced tier, which carries a 25–35% license premium; Tanjga said 70–80% of customers use AI in some form and 40% already pay for it. Appian's disclosed retention meter, cloud net annualized recurring revenue expansion, was 115% at June 30, flat sequentially and up from 113% a year earlier.
The profit line and the demand line disagree
June-quarter adjusted EBITDA was $16.2m against $5–8m guided and $8.1m a year earlier, and the GAAP operating loss halved to $5.44m. That follows a first full-year GAAP operating profit in 2025, of $0.6m, after a $60.9m loss in 2024. It is not headcount surgery: chief executive Matt Calkins told investors on the August 6 call that pulling 2027 hiring forward "might be an indication of strong pipeline that's unusually strong and also our confidence of being able to win in the current environment."
The demand meters run the other way. Revenue growth slowed to 19.1% in the June quarter, from 21.5% in March. Gross margin has compressed to 71.2% from 75.8% four quarters ago, with subscription gross margin down to 84% from 86%. Unsatisfied performance obligations of $625.3m grew 13%, slower than revenue. And the raised full-year guide — 16–17% total revenue, 20–21% cloud — sits below the 23% cloud growth just posted.
One popular explanation for the margin story is wrong. The professional-services book has not been starved: services revenue grew 20%, marginally faster than the total, holding 22.4% of revenue against 22.3% a year earlier, and its gross margin improved to 31% from 29%. The compression came from the software line.
What the shares have already paid for
Appian has held an uptrend since mid-August, its 50-day average above its 200-day, after a 79% gain over three months that roughly doubled the next-best move among comparable subscription-software names. Two-thirds of it arrived before results, in a window when Freshworks, nCino and Procore all turned up too — the likelier reading is a sector-wide re-rating of beaten-down software, with the August print adding a company-specific 14% session. Price-to-gross-profit went from 3.07x in early May to 4.77x trailing, against consensus revenue for the year rising about 3% to $849.7m. Forward, at 4.47x gross profit, Appian sits at the median of that group, below construction-software maker Procore at 6.46x and above accounting-automation vendor BlackLine at 2.85x, while carrying roughly double the group's median forward growth. Stretched against May; against last September, the shares are up 14.8% on trailing revenue up 15.1%, and the multiple has not moved at all.
So the profit inflection is earned and the margin story is real; the acceleration the multiple implies appears in no demand meter except retention, and management's own guidance embeds further slowing. Against Pegasystems — whose annual contract value growth halved to 7% — Appian is taking share. Against ServiceNow and Microsoft's bundled Power Platform, there is no win-rate evidence either way.
Which leaves the one item no operating metric prices. A retrial can return a number larger than the company, or nothing at all. Fairfax County, January 11.