

Descartes Bought Extensiv for $120m, Entering Manhattan Associates' Warehouse Market
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two logistics software vendors that used to sell around each other now sell into the same socket — and both were repriced by the market months before either of their meters turned. Manhattan Associates raised full-year revenue guidance to $1.160bn-$1.166bn in July on remaining performance obligations of $2.47bn, up 23%, and cloud revenue up 26%; its shares gapped over two sessions and dragged the whole de-rated vertical software group up with them.
Descartes reported its own quarter only on 10 September: revenue up 12%, operating income up 36%, but organic services growth still "just north of 9%," flat against the prior quarter. The freight volume meter it bills against inflected the same day, with Cass August shipments up 2.1% year on year, the first annual gain since January 2023. Manhattan's re-rating has bookings behind it. Descartes' has margin and cash acquisitions — the volumes are still a forecast.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
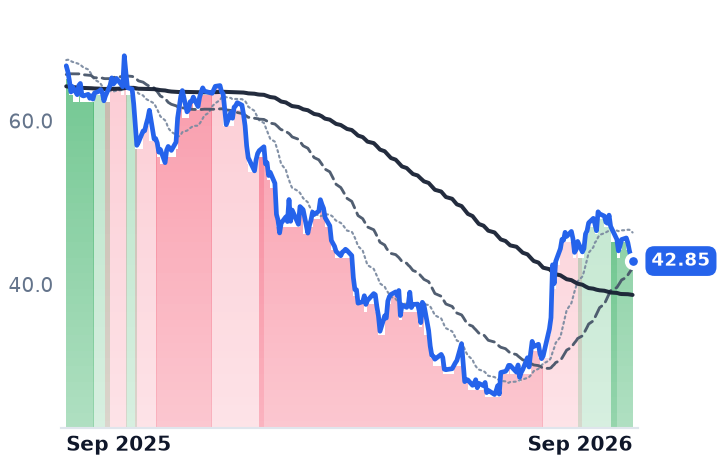
DSGX | The Descartes Systems | Specialized Enterprise Solutions | 🌱 Emerging Bull | −1.2% | −25.2% |
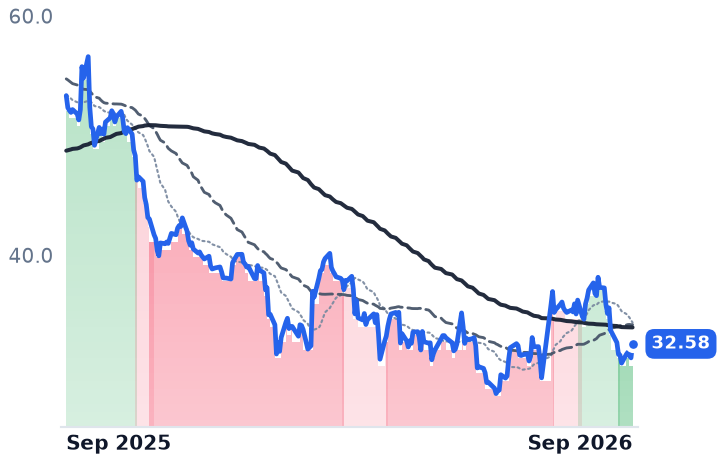
MANH | Manhattan Associates | Specialized Enterprise Solutions | 🌱 Emerging Bull | −1.4% | −2.0% |
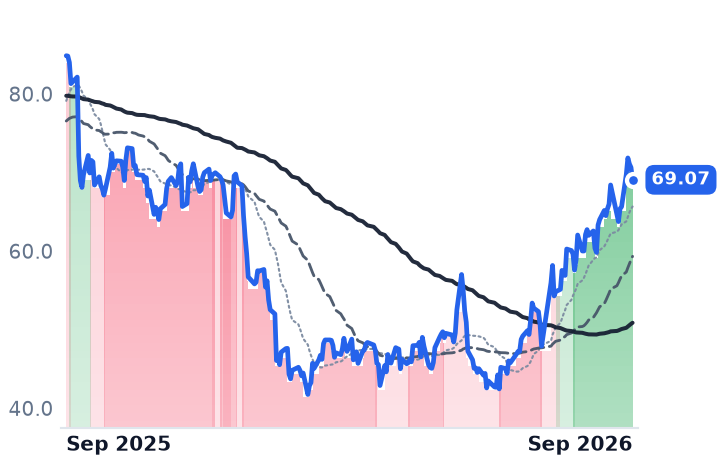
AGYS | Agilysys | Specialized Enterprise Solutions | 🟢 Cont. Bull | −12.0% | −6.4% |
| Compared against · context, not the story | |||||
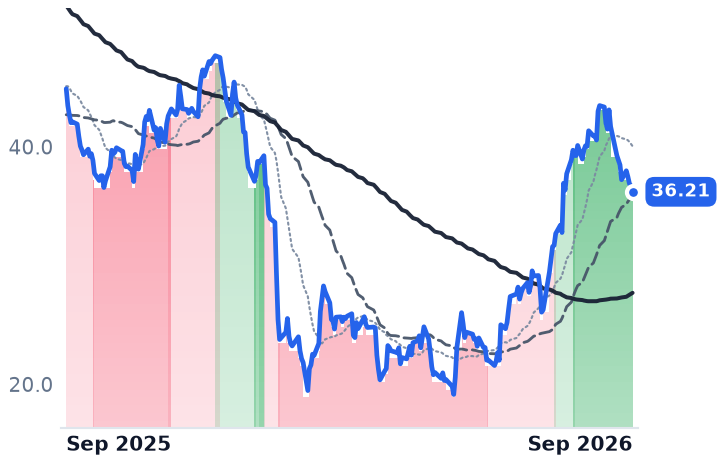
APPF | AppFolio | Specialized Enterprise Solutions | 🌱 Emerging Bull | −4.4% | −24.7% |
BLKB | Blackbaud | Specialized Enterprise Solutions | 🌱 Emerging Bull | −9.8% | −35.8% |
BSY | Bentley Systems, Incorporated | Specialized Enterprise Solutions | 🌱 Emerging Bull | −12.1% | −38.9% |
DOCU | DocuSign | Specialized Enterprise Solutions | 🌱 Emerging Bull | +11.4% | −18.6% |
INTA | Intapp | Specialized Enterprise Solutions | 🌱 Emerging Bull | −12.4% | −19.3% |
NOW | ServiceNow | Specialized Enterprise Solutions | 🌱 Emerging Bull | +5.4% | −28.5% |
PAR | PAR Technology | Specialized Enterprise Solutions | 🌱 Emerging Bull | −21.9% | −63.7% |
PCOR | Procore Technologies | Specialized Enterprise Solutions | 🌱 Emerging Bull | −19.2% | −27.2% |
PTC | PTC | Specialized Enterprise Solutions | 🌱 Emerging Bull | −12.1% | −34.0% |
ROP | Roper Technologies | Specialized Enterprise Solutions | 🌱 Emerging Bull | −9.5% | −26.2% |
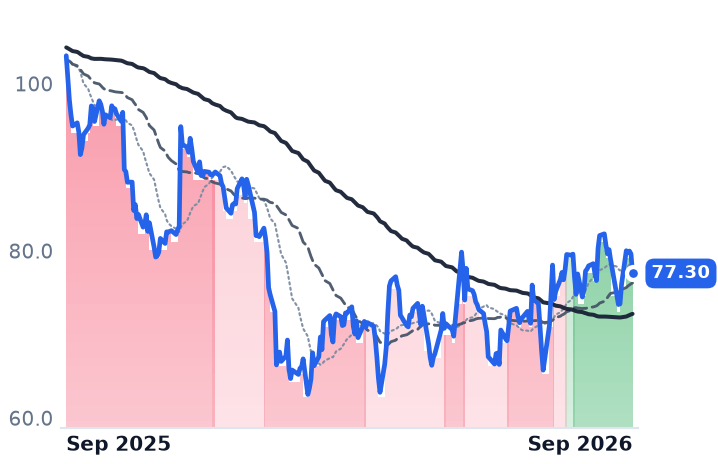
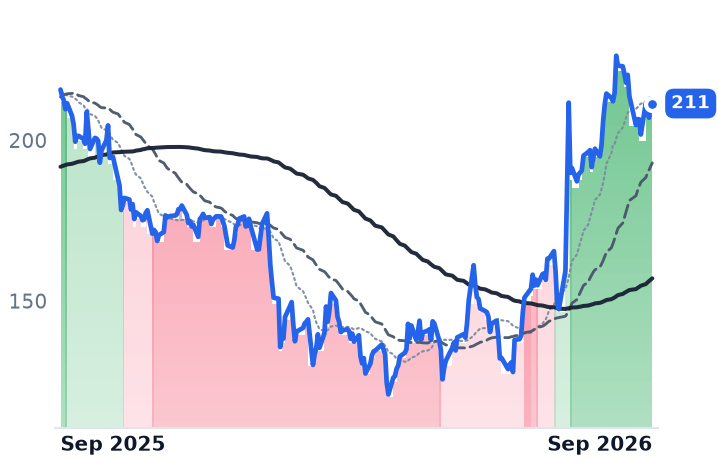
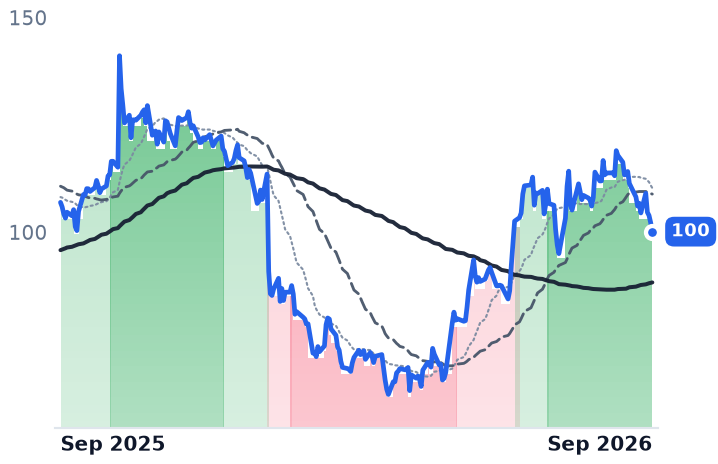
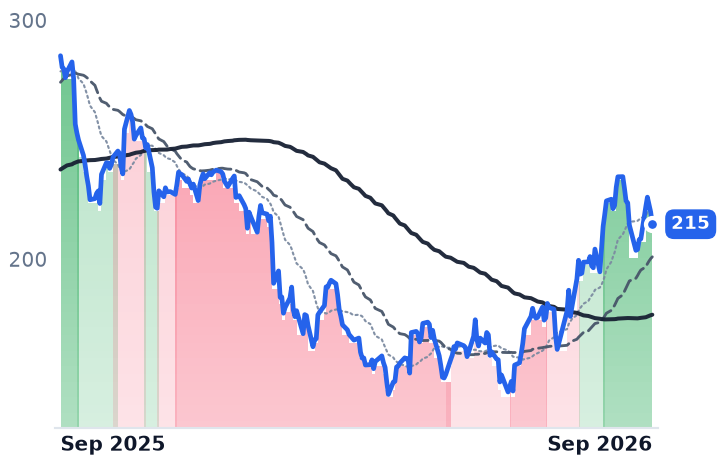
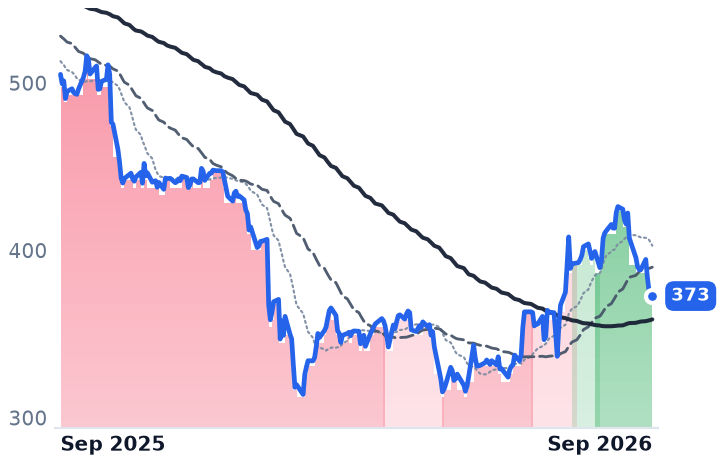
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DSGX | $6.6B | 35.0x | 33.6x | 8.5x | 8.0x | 12.1x | 11.4x | 18.4x | 4.5% |
MANH | $12.3B | 60.1x | 38.5x | 10.9x | 10.6x | 20.0x | 19.4x | 42.1x | 3.2% |
AGYS | $2.8B | 65.4x | 40.8x | 8.6x | 7.6x | 13.7x | 12.2x | 42.2x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APPF | $7.7B | 48.7x | 31.1x | 7.4x | 6.8x | 11.7x | 10.8x | 36.1x | 3.5% |
BLKB | $1.9B | 13.2x | 8.2x | 1.7x | 1.7x | 2.8x | 2.8x | 9.5x | 14.3% |
BSY | $9.5B | 35.4x | 23.3x | 5.9x | 5.6x | 7.3x | 6.9x | 21.2x | 5.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DOCU | $13.2B | 41.4x | 14.9x | 3.9x | 3.8x | 4.9x | 4.7x | 20.3x | 9.1% |
INTA | $2.8B | n/m | 22.6x | 4.8x | 4.2x | 6.4x | 5.6x | n/m | 4.9% |
NOW | $140.1B | 84.1x | 33.3x | 9.5x | 8.6x | 12.7x | 11.6x | 41.8x | 3.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PAR | $629.0M | n/m | 19.9x | 1.3x | 1.2x | 3.3x | 3.1x | n/m | -3.0% |
PCOR | $7.7B | n/m | 30.5x | 5.4x | 5.1x | 6.8x | 6.4x | 120.8x | 3.8% |
PTC | $15.7B | 13.1x | 16.6x | 5.3x | 5.8x | 6.3x | 6.9x | 10.1x | 6.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ROP | $37.6B | 15.5x | 16.8x | 4.5x | 4.4x | 6.5x | 6.3x | 10.8x | 7.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DSGX | Revenue | +15.0% | +11.8% | +12.8% |
| EPS | +15.8% | +23.5% | +15.6% | |
MANH | Revenue | +8.3% | +8.6% | +8.8% |
| EPS | +10.3% | +11.8% | +15.3% | |
AGYS | Revenue | +16.5% | +16.6% | +16.9% |
| EPS | +26.9% | +49.3% | +30.3% | |
APPF | Revenue | +18.5% | +17.4% | +18.7% |
| EPS | +33.8% | +22.8% | +28.6% | |
BLKB | Revenue | +4.5% | +4.6% | +3.2% |
| EPS | +18.8% | +13.8% | −37.2% | |
BSY | Revenue | +13.6% | +10.5% | +10.2% |
| EPS | +18.4% | +12.2% | +16.3% | |
DOCU | Revenue | +8.4% | +9.2% | +8.0% |
| EPS | +6.9% | +22.1% | +12.8% | |
INTA | Revenue | +14.7% | +14.6% | +15.0% |
| EPS | +36.8% | +29.9% | +22.3% | |
NOW | Revenue | +22.4% | +18.7% | +18.6% |
| EPS | +17.1% | +23.2% | +21.4% | |
PAR | Revenue | +15.1% | +9.9% | +10.2% |
| EPS | +505.2% | +86.3% | +84.9% | |
PCOR | Revenue | +15.3% | +13.9% | +14.4% |
| EPS | +24.1% | +46.2% | +20.2% | |
PTC | Revenue | +4.9% | +6.4% | +7.5% |
| EPS | +20.4% | +8.8% | +10.2% | |
ROP | Revenue | +8.1% | +5.9% | +5.6% |
| EPS | +11.5% | +9.5% | +9.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Descartes Systems Group, the Waterloo, Ontario vendor that bills carriers, brokers and retailers by the transaction and the message across its Global Logistics Network, paid roughly $120m of cash on 1 September for Extensiv, a cloud warehouse-management platform used by more than 1,200 third-party logistics providers. Eight days earlier it had agreed to buy Tai, a transportation management system for freight brokers, for about $100m. The Extensiv deal drops Descartes into the third-party-logistics warehouse socket that Manhattan Associates sells into; the two vendors, previously adjacent, now overlap.
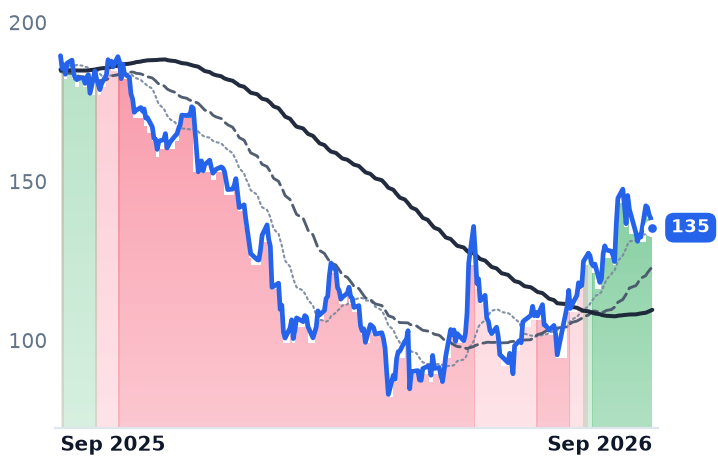
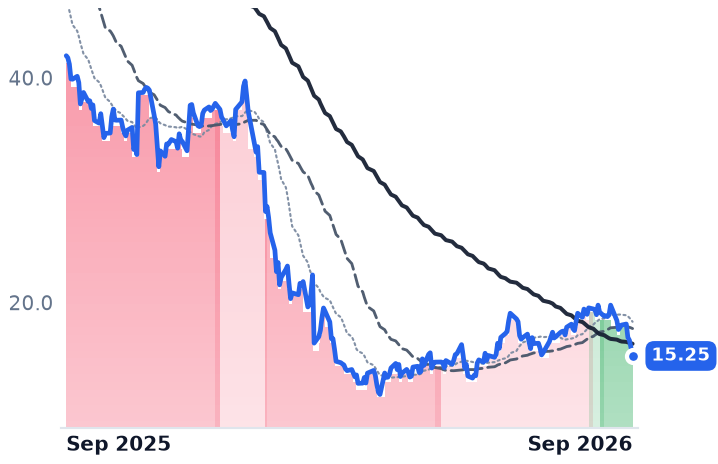
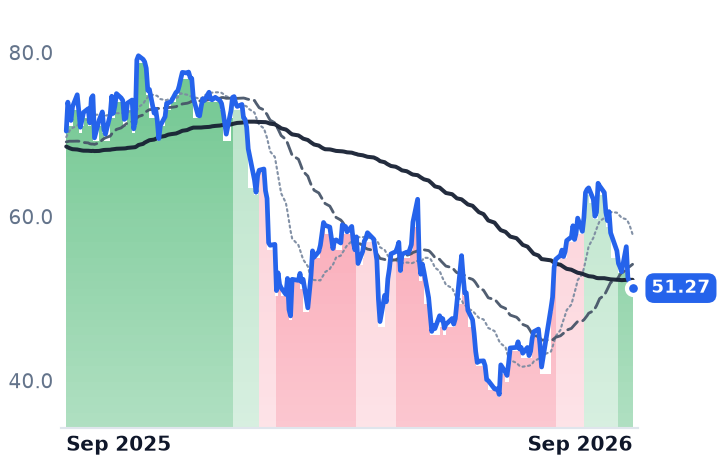
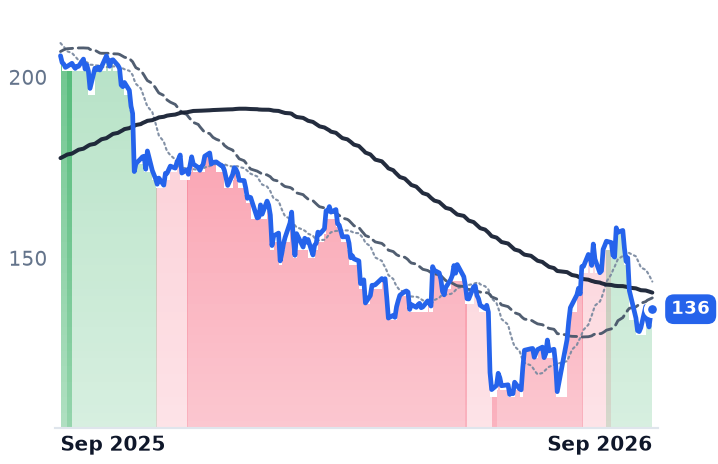
By then both companies had already been repriced. Manhattan's shares rose 32.9% over the two sessions after its 28 July results, and every other name in the de-rated enterprise-software group rose with it — Blackbaud 22.7%, Agilysys 10.6%, Descartes 10.2%. Descartes' own quarter did not land until 10 September, a month after its uptrend was established. What is at stake is whether the market has paid in advance for a freight recovery that has barely begun to appear in either income statement.
What Manhattan earned
Manhattan, the Atlanta company whose warehouse, transportation and order-management software sits inside grocery, pharmaceutical and retail distribution centers, reported second-quarter revenue of $297.8m, up 9.3%, with cloud revenue up 26% and remaining performance obligations of $2.47bn, up 23%. It raised full-year guidance to $1.160bn-$1.166bn from the $1.13bn-$1.15bn set in January. "On strong demand, we posted our third consecutive record bookings quarter and once again accelerated our revenue growth," chief executive Eric Clark said on 28 July.
The line that matters most for whether customers are still funding warehouse projects is professional services — implementation hours booked against a fixed bench of consultants. It came in at $133.0m, up 3%, after falling 3% a year earlier. Reported operating income still fell 10.2%, carrying $7m-$9m of severance from the 260 job cuts, 6% of staff, announced on 1 June.
What Descartes reported
Descartes' fiscal second quarter, ended 31 July and published on 10 September, showed record revenue of $201.1m, up 12%, of which services — the metered network business — was $188.6m, or 94% of the total, up 13%. Operating income rose 36% to $65.5m; adjusted EBITDA reached $94.4m, just under 47% of revenue. Operating margin has widened about six points over eight quarters.
The number that cannot be bought did not move. On the call, management put organic services growth, excluding recent acquisitions and currency, at "just north of 9%" — essentially the 9.1% of the prior quarter. "Today's supply chains and logistics operations need to be agile in the face of an increasingly dynamic global trade environment," chief executive Edward J. Ryan said in the release. The shares rose 3.2% the next session, touched $80.02 on 14 September and settled back at $77.30, about a quarter below their 52-week high.
The meter turned the same day
On 10 September, Cass reported that August freight shipments rose 2.1% year on year, the first annual gain since January 2023 and the end of a 42-month downturn, with truckload linehaul rates up 11.3%. Rates are the wrong meter for Descartes, which is paid per filing and per message rather than per dollar of freight spend; shipment counts are the right one, and they have only just crossed zero. Management said trucking volumes were down 4% year on year in the quarter, with growth coming from adoption — its MacroPoint agents lifted tracking penetration from 87% to 93% in about six months. Filing complexity is the other lever: with de minimis treatment suspended for all countries from 29 August 2025, low-value parcels now require full customs entries, and each one is a billable event.
What the group paid
Gross margins differ too widely across these three for sales multiples to compare — Manhattan's is near 53%, Agilysys' near 63% — so measure them against forward gross profit: Descartes at 11.4x, Agilysys at 12.2x, Manhattan at 19.4x. Manhattan carries 38.5x this year's consensus earnings, against roughly 25x in late February, for consensus earnings growth near 10%. Descartes sits at 33.6x forward against 35.0x trailing, and at the same 11.4x it carried in August, against roughly 14.5x a year ago.
Agilysys, which sells property-management and point-of-sale systems to hotels and casinos and shares nothing with the other two but a sector label, is the useful counter-example: its uptrend began in mid-July, before its own 27 July beat-and-raise took full-year guidance to $368m-$373m, and it has given back 10.6% in the past month. The repair across this group came in one eight-week cluster, ahead of the reporting.
So the split is clean. Manhattan's re-rating has a business under it: record bookings, rising obligations, a services line that stopped shrinking, guidance raised twice. Descartes' does not yet — margin expansion and $220m of cash tuck-ins carry the earnings, while the organic meter has been pinned at roughly 9% for two quarters and the freight index only turned positive a month after the shares had. If shipment counts keep rising, the anticipation is vindicated; if August was noise, what is left is a cheaper multiple and an acquisition budget.
That budget has already changed the map. Descartes no longer sells alongside Manhattan into third-party logistics warehouses — it sells against it.