

Brookfield Renewable's 5.26% Payout Slipped Below the 30-Year Treasury's 5.33%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two renewable yield vehicles broke down this quarter and neither break came from the power plants. Brookfield Renewable posted record second-quarter funds from operations of $0.62 per unit, up 11%, with hydro running above long-term average; Clearway Energy grew June-quarter revenue 22.7% and operating income 36.5%, and reaffirmed a 2027 target of $2.70 or better in cash available for distribution.
What moved was the discount rate. After the Federal Reserve's September 16 quarter-point hike, the 30-year Treasury reached 5.33%, erasing Brookfield's income advantage entirely. Clearway's payout still clears the long bond by roughly eight-tenths of a point, and its damage shows up in financing instead: about $50m raised against an equity plan of $0.5-1.0bn.
A third move is not repricing at all — Brookfield's corporate twin is converging on a one-for-one merger ratio ahead of October 14 votes.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
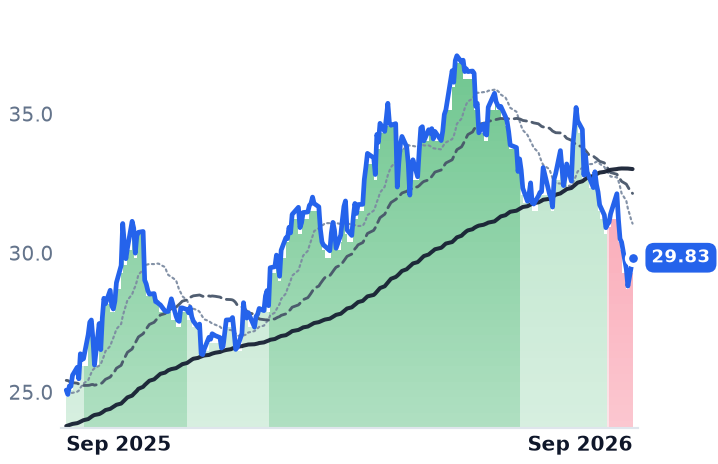
BEP | Brookfield Renewable Partners | Diversified Renewable Generators | ⚠️ Emerging Bear | −9.0% | +19.0% |
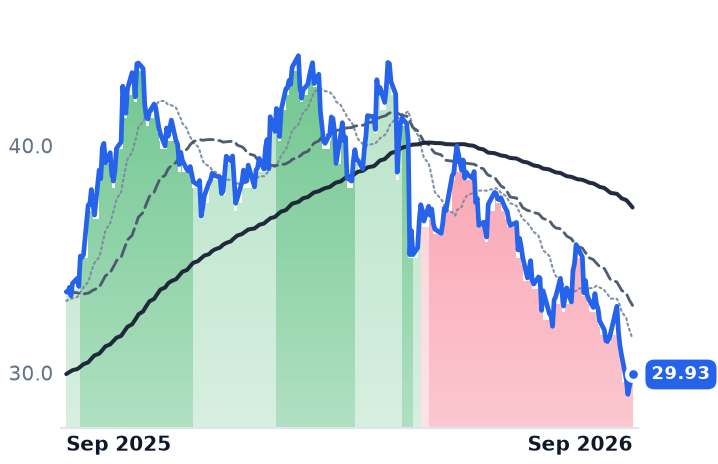
BEPC | Brookfield Renewable | Diversified Renewable Generators | ⚠️ Emerging Bear | −10.0% | −10.8% |
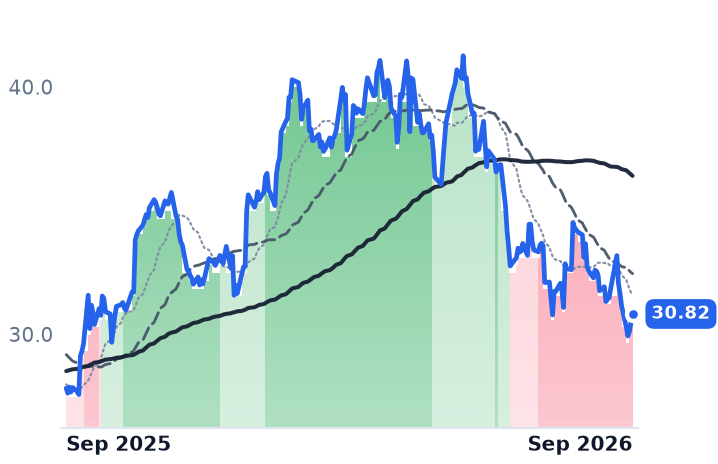
CWEN | Clearway Energy | Wind & Solar Developers | ⚠️ Emerging Bear | −5.3% | +10.8% |
| Compared against · context, not the story | |||||
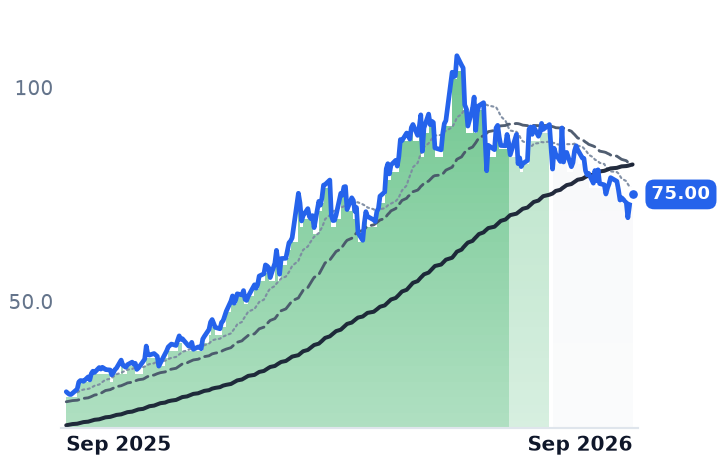
ENLT | Enlight Renewable Energy | Wind & Solar Developers | 🟢 Cont. Bull | −6.2% | +159.7% |
RNW | ReNew Energy Global | Wind & Solar Developers | 🌱 Emerging Bull | +0.4% | −12.8% |
XIFR | XPLR Infrastructure | Renewable & Infrastructure Assets | 🟢 Cont. Bull | −1.9% | +12.0% |
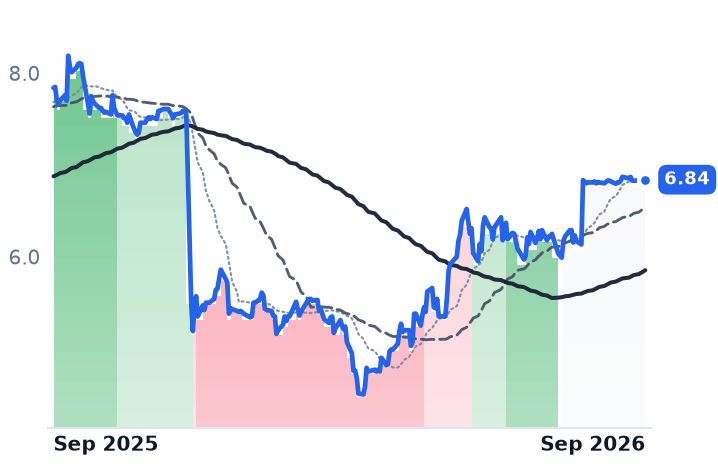
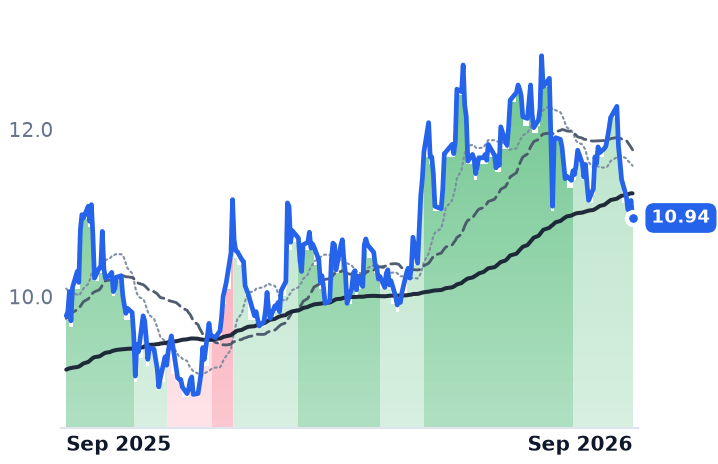
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BEP | $9.1B | 64.8x | — | 1.4x | 1.4x | 5.9x | 5.6x | 9.7x | -51.7% |
BEPC | $4.4B | n/m | — | 1.1x | 0.7x | 2.3x | 1.6x | n/m | -12.5% |
CWEN | $6.3B | 40.6x | — | 4.0x | 3.8x | 7.6x | 7.3x | 14.3x | 10.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ENLT | $11.3B | 119.0x | 63.0x | 19.3x | 4.7x | 34.6x | 8.4x | 32.4x | -19.8% |
RNW | $2.5B | 20.9x | — | 1.7x | — | 2.8x | — | 9.3x | -23.2% |
XIFR | $1.1B | 17.0x | 10.0x | 0.9x | 0.8x | 5.2x | 4.6x | 8.9x | -59.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BEP | Revenue | +3.9% | +7.6% | −11.5% |
| EPS | +5.7% | −20.9% | −6.6% | |
BEPC | Revenue | +4.6% | +16.3% | +5.7% |
| EPS | +280.9% | −93.3% | +455.5% | |
CWEN | Revenue | +14.5% | +11.5% | +12.2% |
| EPS | −116.0% | −318.9% | +60.4% | |
ENLT | Revenue | +32.0% | +45.9% | +52.5% |
| EPS | −53.4% | +116.3% | −100.0% | |
RNW | Revenue | +42.1% | +13.9% | +21.0% |
| EPS | +1367.7% | +78.6% | +150.0% | |
XIFR | Revenue | +0.8% | +4.7% | +1.3% |
| EPS | −849.6% | −44.0% | −144.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A yield vehicle is a spread over the long bond, and Brookfield Renewable's spread has closed. The partnership declared a quarterly distribution of $0.392 per unit, an annualized $1.57 and more than 5% above the prior year. Against the September 18 close of $29.83 that is a 5.26% yield. The 30-year Treasury paid 5.33% the same day.
That arithmetic governs a whole class of securities. Brookfield Renewable owns hydroelectric, wind, solar and pumped-storage plants across North America, Colombia and Brazil and sells their output under contracts averaging more than a decade. Clearway Energy, spun out of NRG in 2018, owns roughly 5,000 net megawatts of American wind and solar plus about 2,500 megawatts of gas-fired generation. Both are bought for contracted cash, and both fund growth partly with equity issued at whatever price the market sets. When the long bond moves, the price moves before the meter does — and here the meters ran the other way.
The accounts went up
Brookfield's fourteen-month uptrend broke in the first days of September, its 50-day average falling through its 200-day; the units are down 9.1% over thirty days and still up 16.4% over twelve. The break followed the Federal Open Market Committee's September 16 quarter-point increase to 3¾-4%, its first hike in three years, with utilities falling more than 5% as long-dated yields surged.
The operating record points the opposite way. Brookfield reported record second-quarter funds from operations of $421m, or $0.62 per unit, up 11% per unit on July 31. Hydro contributed $336m, with the US and Colombian fleets running above long-term average. "We delivered record financial results, robust capital deployment, and the highest levels of development and asset recycling in our history," chief executive Connor Teskey said. Asset sales agreed or closed in the quarter carried about $2.2bn of proceeds, $630m net to Brookfield.
Two caveats travel with that record. Roughly $175m of the $421m was gains on developed assets and non-core disposals — two-fifths of the quarter, and not repeatable by definition. And reported revenue fell 1.8% to $1.66bn, a second consecutive quarterly decline.
One fall that is only arithmetic
Brookfield Renewable Corporation, the corporate twin holding roughly 12,723 megawatts of the same fleet, is down 20.0% in three months. That is not a de-rating. On July 21 Brookfield announced it would fold partnership and corporation into a single listed company, exchanging units and shares one-for-one, with special meetings on October 14. The corporation's premium over the partnership has gone from 41.1% last December to 0.3% on September 18. Brookfield's ownership, the preferred units and the management fee arrangements are unchanged: no cash flows differently for anyone.
Clearway's damage is in the funding
Clearway grew June-quarter revenue 22.7% to $481m, the third straight quarter of acceleration, with operating income up 36.5%. It also cut 2026 cash available for distribution guidance to $430-470m from $470-510m and reaffirmed a 2027 target of $2.70 per share or better. "In the near term, our 2026 outlook has been impacted by transitory weather patterns in the first half of the year," chief executive Craig Cornelius told investors on August 5. The shares had already rolled over on July 20, a fortnight before that cut.
In June Clearway recontracted all three Texas wind projects, more than 600 megawatts, out past 2040 at better pricing, against North American wind power contracts clearing at a record $79.40 per megawatt-hour. The strain is elsewhere: the $3bn plan through 2029 assumes $0.5-1.0bn of external equity, of which about $50m has been raised, and third-party project purchases have been deprioritized until the share price recovers. XPLR Infrastructure, the former NextEra Energy Partners, shows where that road ends — it suspended distributions outright rather than issue equity.
What the prices are saying
Brookfield is the cheaper security at 9.65 times trailing enterprise value to EBITDA against Clearway's 14.3 times, but its earnings are flattered by disposal gains while Clearway's are project-level contracted cash. Clearway trades at 0.68 times book — under the carrying value of a contracted fleet — and 11.4 times the 2027 cash target it just reaffirmed, on a 6.17% dividend that still clears the long bond by roughly eight-tenths of a point.
The verdict splits. Brookfield's slide is earned by the anchor that governs any income vehicle, and no amount of record recycling fixes a payout that pays less than a Treasury. Clearway's is not earned by its accounts, which accelerated; it is earned by the cost of the equity it must sell, which is a real cost and a real constraint on the $3bn plan. Meanwhile the tax regime tightens underneath both: production and investment credits terminate for wind and solar beginning construction after July 4, 2026 unless in service by the end of 2027, and the Treasury guidance narrowing eligibility was vacated by a federal court, leaving near-term pipelines legally unresolved.
The October 14 votes will give holders of both Brookfield securities one price for one fleet. What no vote settles is the question the long bond now puts to every contracted megawatt-hour: what a decade of indexed cash is worth when a Treasury pays more and carries no weather.