

CSX Moved to Kill the Union Pacific Merger; Norfolk Southern Trades 17.2% Below the Offer
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A railroad asked federal regulators to throw out its neighbor's takeover before the evidence was filed, and on September 18 it lost. The Surface Transportation Board denied three motions for summary denial of Union Pacific's revised application to buy Norfolk Southern — one filed by CSX, which simultaneously wants trackage rights across Norfolk Southern's Pennsylvania lines.
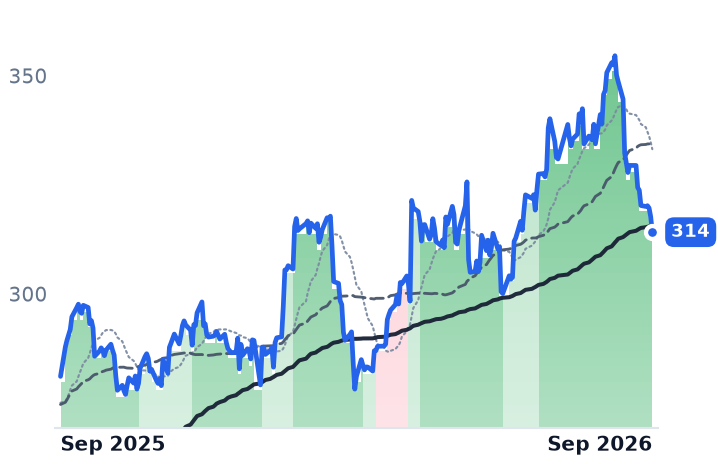
The ruling went the acquirer's way and the discount widened anyway. Norfolk Southern now sits well below the 1.0 Union Pacific share plus $88.82 cash it is owed, against a 13.0% gap on August 19, when the case came out of abeyance. Its June-quarter revenue rose 11% to a record $3.5bn while operating income rose 1.8%.
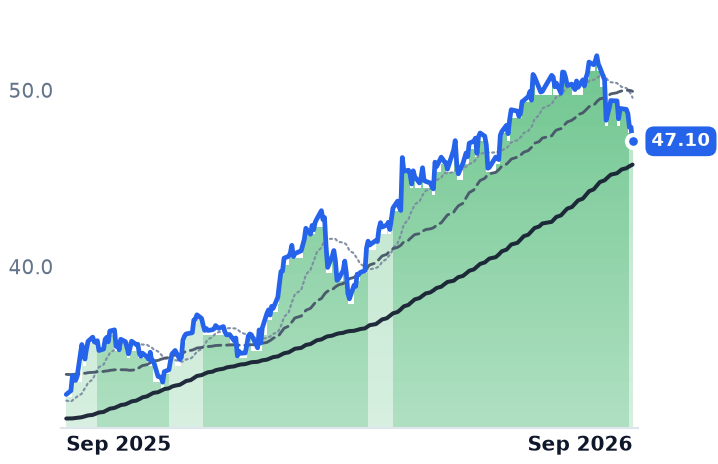
CSX is the group's best operator and its worst-explained selloff: operating ratio 61.7% from 64.1%, volumes up 6%, shares down 6% in a month with the trailing earnings multiple unchanged from May.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CSX | CSX | Class I Railroads | 🟢 Cont. Bull | −7.6% | +43.8% |
NSC | Norfolk Southern | Class I Railroads | 🟢 Cont. Bull | −9.4% | +11.8% |
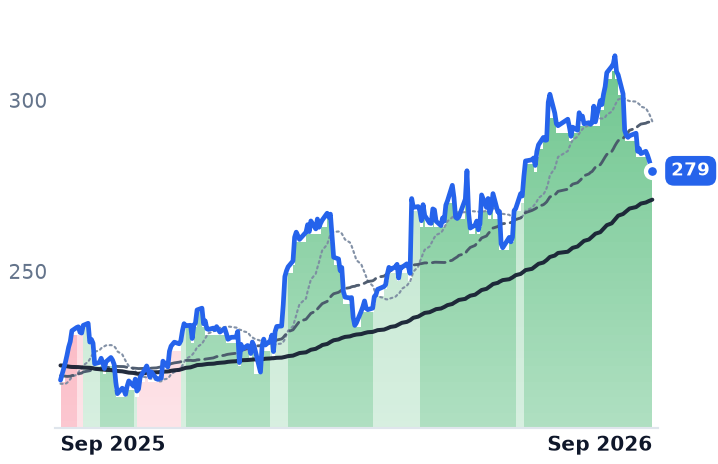
UNP | Union Pacific | Class I Railroads | 🟢 Cont. Bull | −8.1% | +28.0% |
| Compared against · context, not the story | |||||
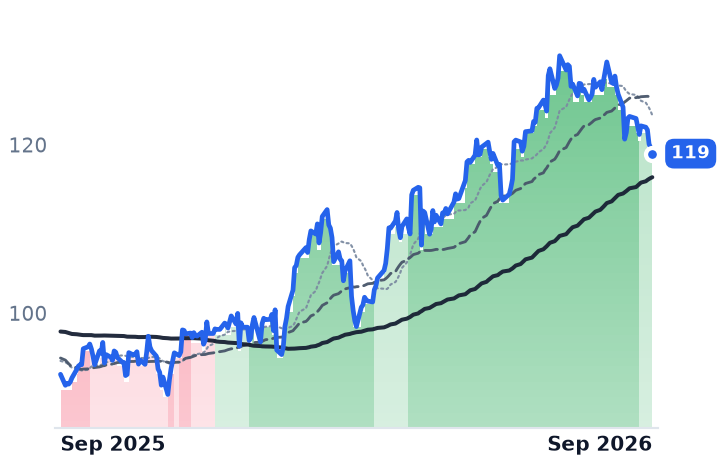
CNI | Canadian National Railway | Class I Railroads | 🟢 Cont. Bull | −7.6% | +28.3% |
CP | Canadian Pacific Kansas City | Class I Railroads | 🟢 Cont. Bull | −8.0% | +16.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CSX | $87.3B | 27.2x | 23.5x | 6.0x | 5.7x | 11.0x | 10.5x | 15.8x | 5.8% |
NSC | $70.6B | 26.8x | 24.2x | 5.6x | 5.3x | 10.5x | 9.9x | 15.9x | 5.4% |
UNP | $166.0B | 22.6x | 21.4x | 6.5x | 6.2x | 14.3x | 13.6x | 14.7x | 3.9% |
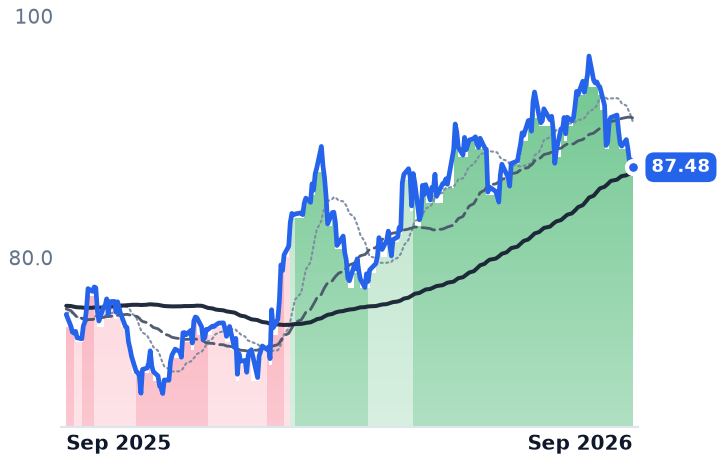
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CNI | $72.0B | 21.4x | 14.3x | 5.7x | 3.8x | 13.5x | 9.0x | 13.5x | 3.5% |
CP | $76.9B | 26.0x | 16.5x | 6.4x | 4.6x | 13.4x | 9.6x | 14.9x | 2.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CSX | Revenue | +7.6% | +5.0% | +3.7% |
| EPS | +22.7% | +13.3% | +10.4% | |
NSC | Revenue | +8.5% | +4.3% | +4.6% |
| EPS | +8.0% | +10.5% | +9.5% | |
UNP | Revenue | +9.3% | +5.1% | +12.6% |
| EPS | +11.9% | +8.4% | +10.9% | |
CNI | Revenue | +9.3% | +4.1% | +5.6% |
| EPS | +10.5% | +10.5% | +10.6% | |
CP | Revenue | +10.9% | +5.7% | +7.2% |
| EPS | +14.3% | +15.7% | +14.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Federal regulators spent September 18 refusing to end a railroad merger fight early. The Surface Transportation Board denied three motions asking it to reject Union Pacific's revised application to control Norfolk Southern for failure to make a prima facie case — motions filed on August 6 by BNSF Railway, by a shipper coalition including the American Chemistry Council and The Fertilizer Institute, and by CSX Transportation. The Board was careful about what it had done: the decision "does not reflect any determination on the merits of the proposed transaction nor is it an endorsement of Applicants' arguments, analyses, or positions." Parties may renew everything in opening comments due November 18.
That date is now the meter for Norfolk Southern's equity, because its share price has stopped being a function of what it hauls. Holders of the eastern Class I, which runs roughly 19,300 route miles across 22 states hauling chemicals, autos, coal and intermodal boxes, are owed one Union Pacific share plus $88.82 in cash. On September 18 that package was worth $368.19 against a $314.16 close — a gross discount of 17.2%, wider than any reading since April, and against 13.0% on August 19, the day the Board lifted its abeyance and started the clock.
The target trades on its acquirer
The inversion is measurable. Over the three months to September 18, Norfolk Southern's daily moves correlated 0.92 with Union Pacific's and 0.81 with CSX's. Before the deal, from January to July 2025, the readings ran the other way: 0.90 with its eastern neighbor, 0.81 with its future buyer. Decompose the last month and the point sharpens — the package Norfolk Southern is owed fell 5.0% as Union Pacific's own shares slid, while Norfolk Southern fell 7.3%. Roughly 2.3 points of its decline is widening deal risk alone.
The freight underneath is not what is moving it, though it is not flattering either. June-quarter railway operating revenue rose 11% to a record $3.5bn on 4% more volume, but six of those eleven points came from higher fuel surcharges, and higher fuel expense carried roughly a 110-basis-point operating-ratio headwind. Operating income grew 1.8%; margin fell about three points to 32.4%. "We've had basically 4 years that we've navigated through a freight recession," chief executive Mark George told the July 23 call. "It is the longest freight recession in history." Management also said the company lost some volume after the merger was announced.
CSX is an adversary with a shopping list
CSX — 19,500 route miles east of the Mississippi, unique access to Mid-Atlantic ports and PJM generation, 22,200 employees — is not objecting on principle. It is asking for trackage rights from Chambersburg to Manville, New Jersey via Harrisburg and the Lehigh Valley, plus access over Norfolk Southern lines to the port terminal at Norfolk. BNSF wants 824 miles between Chicago and Pennsylvania intermodal terminals. Union Pacific has rejected the requests. Those responsive applications land November 18 too.
On its own account CSX is the best operator in the group and the least explained share price. Revenue grew 10.1% to $3.94bn in the June quarter, the operating ratio improved to 61.7% from 64.1%, volumes rose 6% and intermodal 9%. "Our railroaders successfully managed substantial volume growth," chief executive Steve Angel said on July 22. The shares are up 40.9% over twelve months, the best of the five North American Class I roads and far ahead of the merger target's 11.1%, and down 6.3% over the last month.
The selloff has de-rated nothing: CSX's trailing earnings multiple is 27.2x, against 27.4x in early May at a lower share price. Looking forward, CSX at 23.5x and Norfolk Southern at 24.2x both sit above Union Pacific's 21.4x — despite Union Pacific carrying the best operating margin of the three at 40.3%.
What the decline is, and is not
All five Class I railroads fell between 6.0% and 7.3% from August 18 to September 18, with Canadian National and Canadian Pacific Kansas City squarely inside that range, which is the evidence that the month is macro. Diesel set a record $6.285 a gallon on September 14 while rail fuel surcharges reset on a lagged formula — grain surcharges held at 48 cents a mile through September — so the cost lands before the recovery does.
The verdict splits cleanly. CSX's year is earned by the accounts: accelerating revenue, expanding margin, an operating ratio in the low sixties. Its month is a sector de-rating on fuel that its own multiple has not yet absorbed. Norfolk Southern's month is mostly a regulatory reprice, and its multiple is not a judgment on its earnings at all — it is an exchange ratio wearing a price-to-earnings ratio's clothes. Anyone valuing it on carloads is reading the wrong instrument.
A railroad that booked record revenue in June now trades on a filing deadline two months out — and on whether the rival asking for its track gets it.