

Celestica Grew 62% by Selling More of What It Doesn't Design
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Celestica's equity case rests on the hardware it designs itself rather than merely assembles. In the June quarter that owned-design line grew 58% — slower than the 84% posted by the cloud segment it sits inside — so it fell from roughly 58% of that segment to about half, and gross margin slipped to 12.29% from a year earlier.
The shares sit well below their June peak and the business is not the reason: revenue growth has accelerated for four straight quarters and full-year guidance was raised to $20.5bn. September's selling was priced in the bond market, not in anyone's order book. Jabil, which reports fiscal fourth-quarter results on September 30, is the harder case — its valuation expanded over a year in which its growth halved.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CLS | Celestica | Electronic Manufacturing Services | ⚠️ Emerging Bear | +10.1% | +31.5% |
JBL | Jabil | Electronic Manufacturing Services | 🟢 Cont. Bull | −5.5% | +33.6% |
| Compared against · context, not the story | |||||
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | −1.6% | +85.0% |
SANM | Sanmina | Electronic Manufacturing Services | 🟢 Cont. Bull | +4.6% | +68.7% |
PLXS | Plexus | Electronic Manufacturing Services | 🟢 Cont. Bull | +1.7% | +75.0% |
BHE | Benchmark Electronics | Electronic Manufacturing Services | 🟢 Cont. Bull | +2.9% | +90.1% |
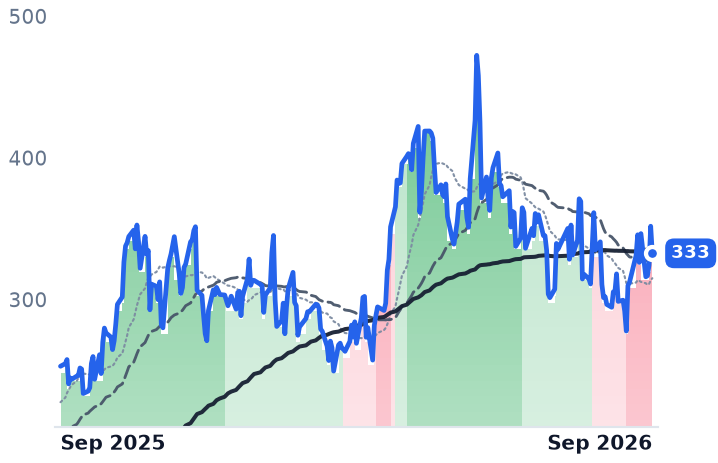
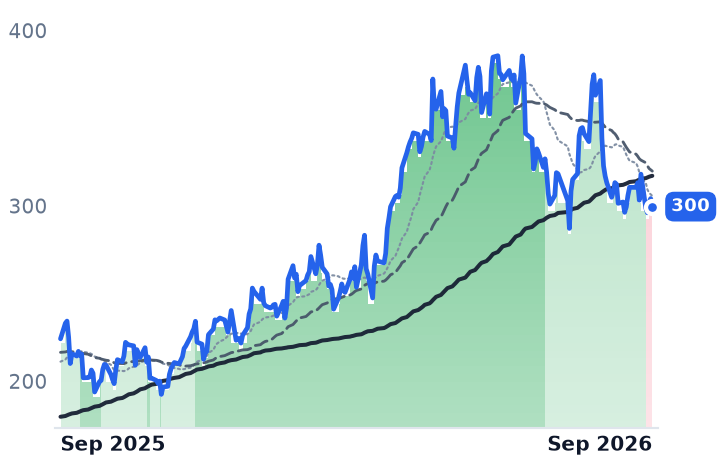
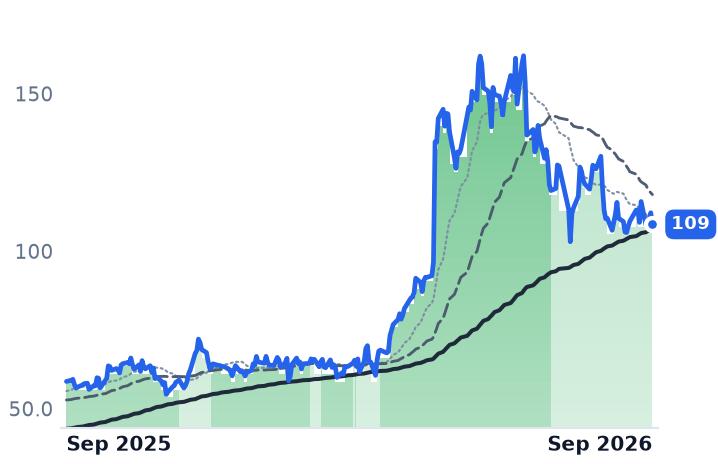
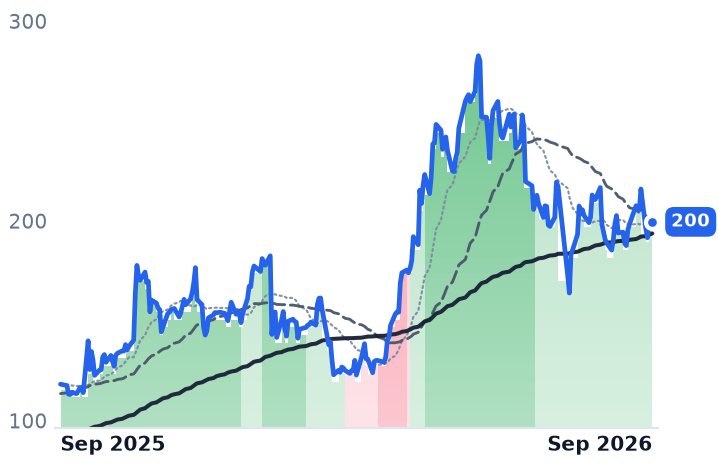
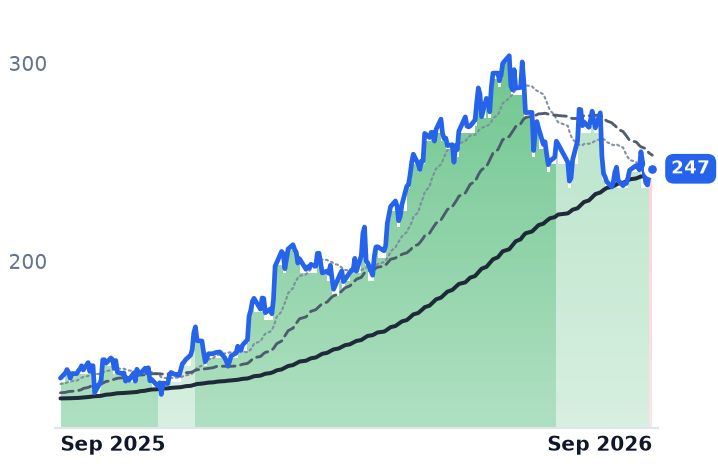
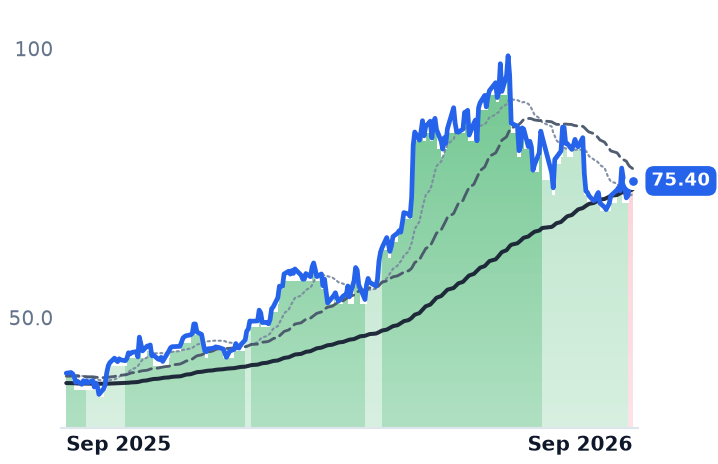
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CLS | $38.2B | 34.2x | 29.5x | 2.4x | 1.9x | 21.1x | 16.0x | 25.6x | 1.4% |
JBL | $31.4B | 37.0x | 17.8x | 0.9x | 0.7x | 10.1x | 8.0x | 16.0x | 4.8% |
FLEX | $39.5B | 41.3x | 22.7x | 1.3x | 1.1x | 14.2x | 12.0x | 22.4x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SANM | $10.1B | 33.1x | 15.6x | 0.8x | 0.7x | 8.8x | 7.9x | 16.0x | 5.9% |
PLXS | $7.3B | 39.6x | 31.9x | 1.6x | 1.5x | 15.9x | 15.0x | 29.4x | 0.8% |
BHE | $2.6B | 49.1x | 24.6x | 0.9x | 0.9x | 9.0x | 8.5x | 18.0x | 4.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CLS | Revenue | +67.5% | +72.1% | +33.1% |
| EPS | +88.6% | +73.5% | +36.3% | |
JBL | Revenue | +20.2% | +21.8% | +13.4% |
| EPS | +35.9% | +31.6% | +21.6% | |
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.7% | +51.5% | |
SANM | Revenue | +74.9% | +15.8% | +11.8% |
| EPS | +103.4% | +15.2% | +12.7% | |
PLXS | Revenue | +20.8% | +13.8% | +9.0% |
| EPS | +19.5% | +15.6% | +12.0% | |
BHE | Revenue | +13.3% | +7.8% | — |
| EPS | +26.7% | +13.0% | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
Celestica sold $4.70bn of hardware in the June quarter, and the half of its cloud business it designs itself grew more slowly than the half it builds to someone else's print.
That distinction is the entire equity case. Celestica, the Toronto contract manufacturer that builds switches, servers, storage and interconnects for hyperscale cloud operators alongside aerospace, industrial and healthtech electronics, books most of its reported revenue as customer-specified components bought and passed straight through at a few points of margin. What it owns is Hardware Platform Solutions — its own switch and storage designs, sold per unit at materially better margins. In the June quarter that line reached roughly $1.9bn, up 58%, while the Connectivity & Cloud Solutions segment around it grew 84% to $3.81bn. Owned design therefore fell from about 58% of that segment to about half. Gross margin followed it down, to 12.29% from 12.82% a year earlier.
The quarter the shares ignored
Everything else in the print went the other way. Operating margin reached a record 9.75%, net income rose 75%, and full-year guidance was raised to $20.5bn of revenue and $11.30 of adjusted earnings per share — growth of 65% and 87%. "Celestica delivered very strong performance in the second quarter, achieving revenue of $4.70 billion and adjusted EPS (non-GAAP) of $2.54, each exceeding the high end of our guidance ranges," chief executive Rob Mionis said in the July 27 results release. Revenue growth has now accelerated four consecutive quarters, from 26.4% to 62.4%.
The balance sheet is carrying that ramp better than the headline suggests. Inventory reached $3.4bn, up $1.5bn on the year for coming cloud program ramps, yet cash cycle days improved to 47, a nineteen-day gain year on year. The concentration did not improve: three customers accounted for 32%, 17% and 14% of the quarter's revenue, roughly 63% between them.
What a year of gains actually bought
Sales multiples do not compare these companies — a dollar of Celestica revenue leaves 12.29 cents of gross profit, a dollar of Jabil's 9.46 cents. On price to trailing gross profit, Celestica trades at 21.14x, against roughly 22.4x twelve months ago and 26.26x in mid-May. The stock's 32% twelve-month gain was earned entirely by gross-profit growth; none of it came from a higher multiple. On fiscal 2027 consensus earnings the two names are struck at nearly the same price, about 17x each.
Jabil, the St Petersburg manufacturing-services group with 135,000 employees spanning healthcare, packaging, automotive, capital equipment and cloud infrastructure, is the one with a de-rating it earned. Revenue growth halved to 11.8% from 23.1%, and operating income grew 10.4% — slower than revenue, with leverage running backwards. Its diversification is also thinner than advertised: AI-related revenue of about $13.6bn against a roughly $35bn outlook is nearly two fifths of the company. "Our diversified model continues to work, allowing us to support strong growth while also driving higher margins and strong free cash flow," chief executive Mike Dastoor said on June 17. Jabil bought back $291m of stock in the May quarter and has retired 8.7% of its shares since August 2024; Celestica went the other way, selling $3bn of new stock at $310 on August 6, some 15% below the prior close.
One session, six companies
On September 14 all six US contract manufacturers fell together in a 6.09% to 9.24% range with no release from any of them — Sanmina worst, then Celestica, Benchmark, Flex, Plexus and Jabil. It was the day the ten-year Treasury yield touched 5.01%, its first reading above 5% since 2023, and the session on which, as this paper noted, an AI-safety essay knocked a semiconductor gauge down 5.9% while the S&P 500 lost under half a percent. Long yields discount 2027 order books and price data-center project finance. The order book itself has not deteriorated: the largest five hyperscalers are on course for more than $600bn of infrastructure spending in 2026. Celestica's shares are up about 7% over thirty days and roughly 20% above their September 2 low of $277.77; the bearish moving-average reading still attached to them dates from the August equity-offering gap.
So the sell-off is a cost-of-capital event, and the business earns none of it. But that verdict cuts both ways. If nothing in the multiple was expansion, nothing in the next year can come from it either, and the meter that matters is mix, not demand — gross margin has now slipped while revenue accelerated, because rack and assembly volume is outgrowing the designs. Jabil's problem is the reverse and simpler: its multiple rose roughly 10% over a year in which its growth rate halved, and the unwind is arithmetic.
Celestica's new 1.6-terabit switches run on Broadcom's Tomahawk 6 — merchant silicon any competitor can buy. What Celestica owns is the system design wrapped around it, and that is the part growing slower.