

BWXT's Backlog Grew 40% to $8.4bn While Its Operating Profit Fell for a Fourth Quarter
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
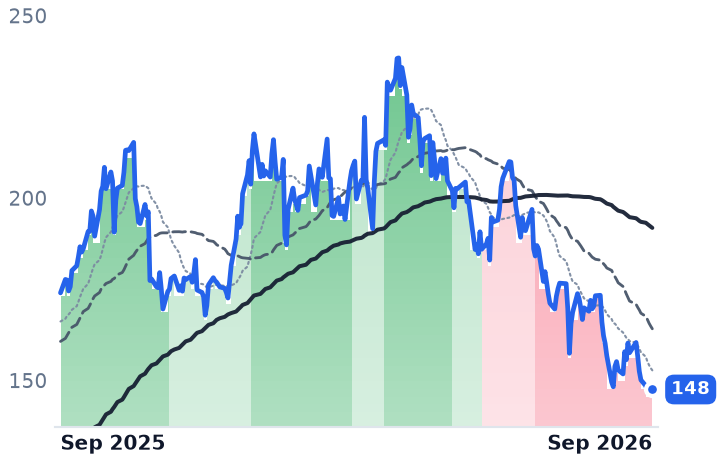
The company in the nuclear complex that cannot be touched by the uranium price fell harder than the two that can. BWX Technologies raised all four of its 2026 guidance lines on August 3, carries $8.4bn of backlog on a trailing book-to-bill of 1.7 times, and won a place in the US Army's microreactor program in August — and its shares are down 28.2% over ninety days.
Its own numbers give the sellers something: June-quarter revenue rose 18% to $901.6m while reported operating income fell 12.2%, the fourth straight quarter of that pattern, as commercial work grew at an 8% margin. Centrus fell on a $500m stock-and-warrant sale, Cameco on Westinghouse. None of that is fuel-cycle economics being marked down — it is the calendar.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
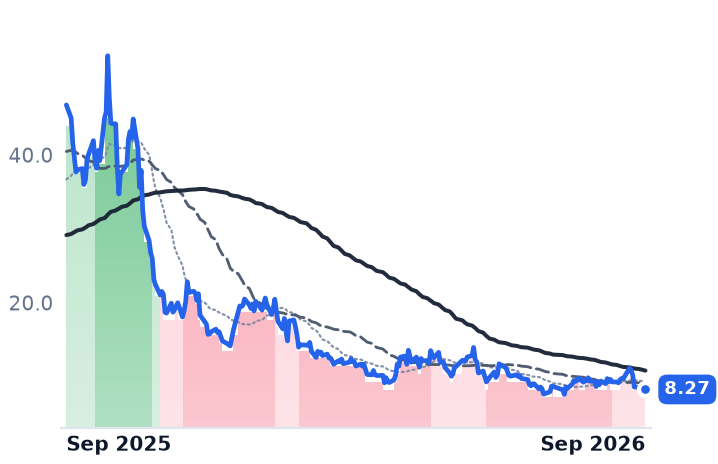
BWXT | BWX Technologies | Naval & Shipbuilding | ⚠️ Emerging Bear | −7.9% | −15.2% |
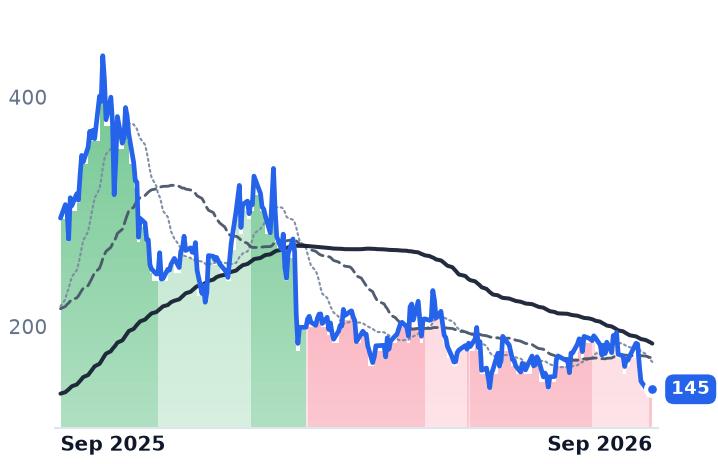
LEU | Centrus Energy | Uranium | ⚠️ Emerging Bear | −17.7% | −50.7% |
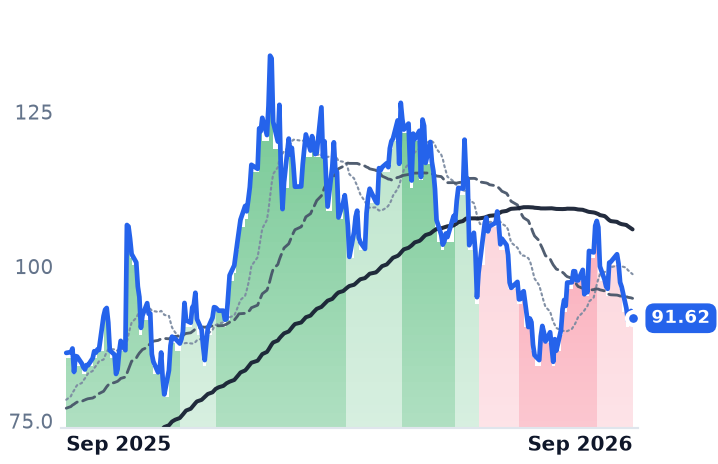
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | −4.4% | +6.5% |
| Compared against · context, not the story | |||||
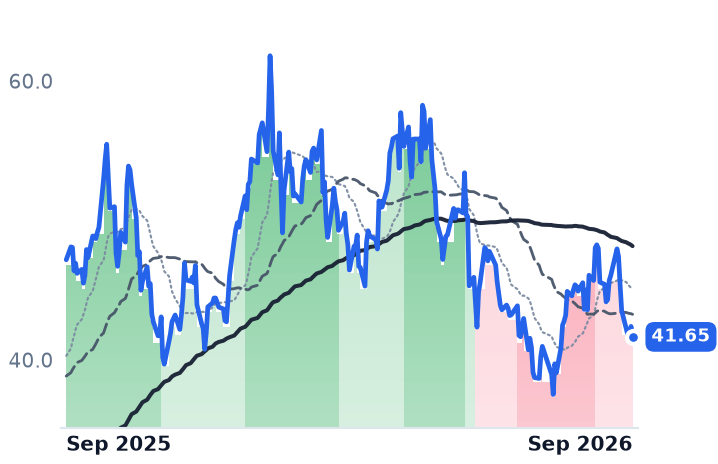
URA | Global X - Uranium ETF | Asset Management | ⚠️ Emerging Bear | −4.4% | −11.7% |
UEC | Uranium Energy | Uranium | ⚠️ Emerging Bear | −11.2% | −20.6% |
UUUU | Energy Fuels | Uranium | ⚠️ Emerging Bear | −15.8% | −21.3% |
NXE | NexGen Energy | Uranium | ⚠️ Emerging Bear | −8.5% | +6.1% |
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −8.8% | −71.9% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | −7.1% | −82.3% |
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | −6.7% | −22.8% |
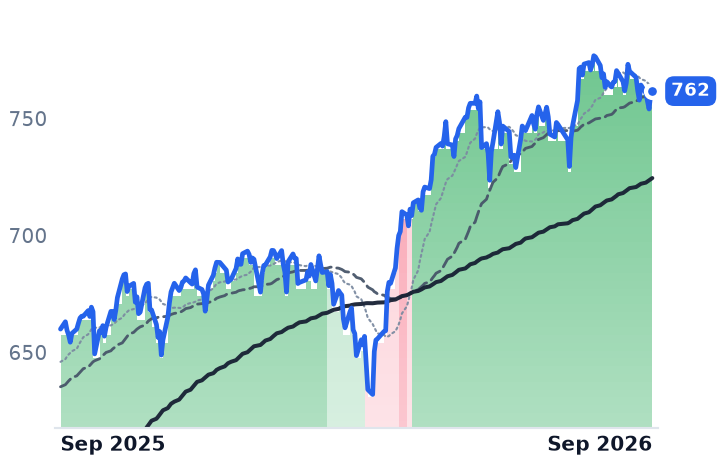
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.2% | +15.4% |
DNN | Denison Mines | Uranium | ⚠️ Emerging Bear | −8.6% | +7.1% |
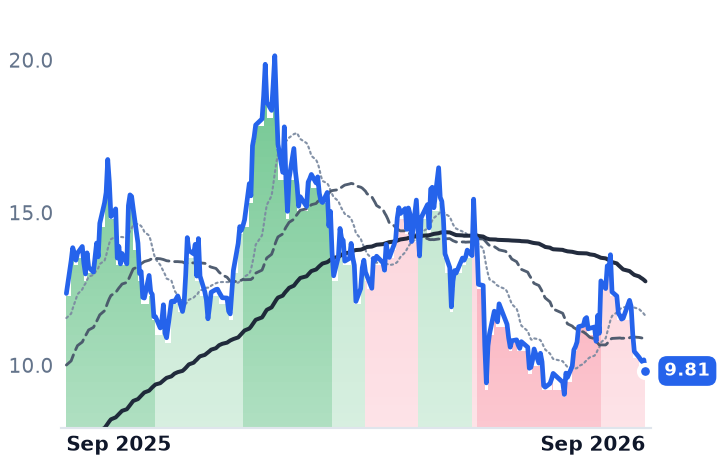
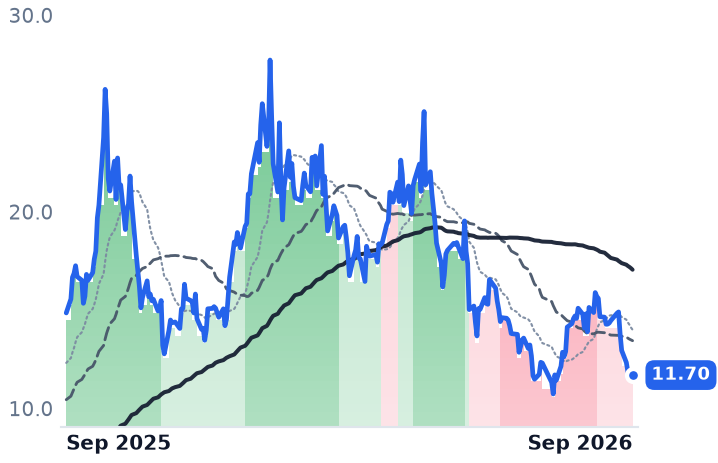
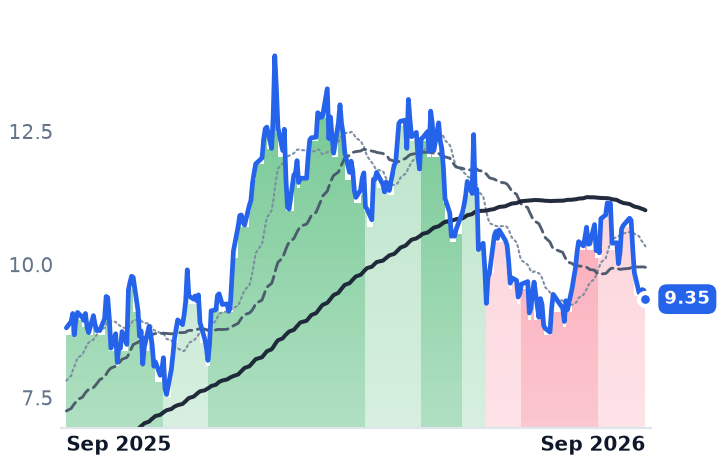
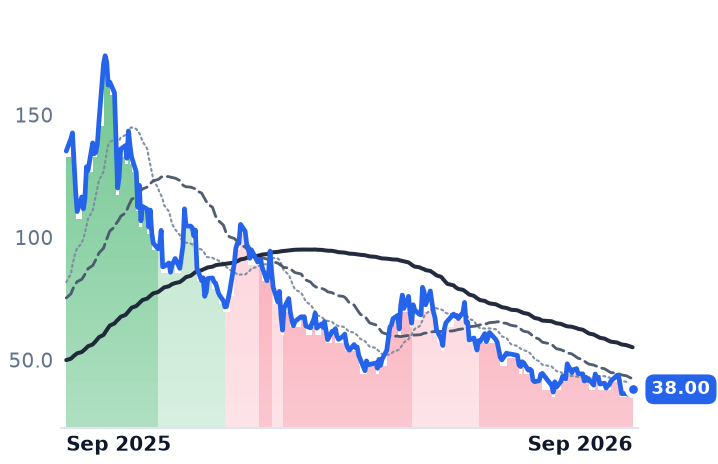
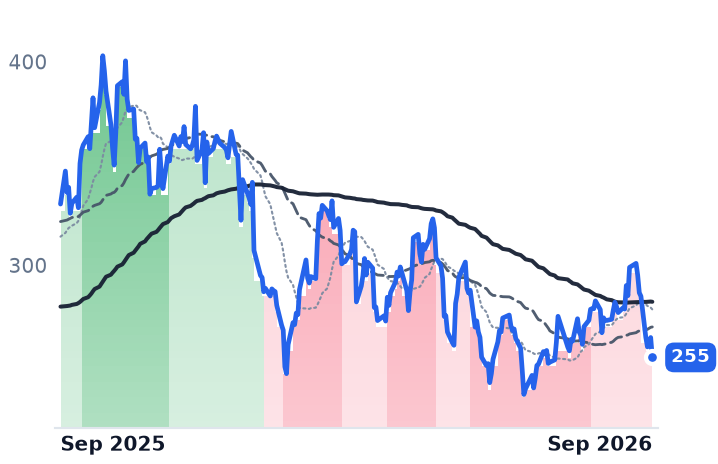
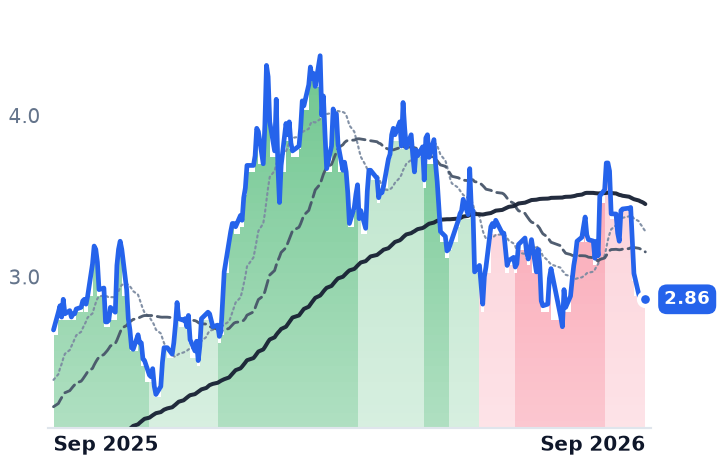
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $13.5B | 38.0x | 31.1x | 3.8x | 3.6x | 17.4x | 16.1x | 27.0x | 2.3% |
LEU | $2.8B | 57.9x | 57.0x | 5.8x | 5.8x | 25.0x | 25.1x | 28.4x | -8.1% |
CCJ | $39.9B | 156.7x | 59.2x | 16.1x | 11.2x | 58.2x | 40.5x | 64.6x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
URA | $3.9B | — | — | — | — | — | — | — | — |
UEC | $5.0B | n/m | — | 247.9x | 48.9x | 585.8x | 115.5x | n/m | -2.4% |
UUUU | $3.0B | n/m | — | 28.3x | 22.5x | 65.5x | 52.0x | n/m | -3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXE | $7.2B | n/m | — | n/m | — | — | — | n/m | -2.4% |
OKLO | $6.9B | n/m | — | — | — | — | — | n/m | -4.0% |
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEG | $102.3B | 27.7x | 23.6x | 3.3x | 3.1x | 3.4x | 3.2x | 14.8x | 0.3% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
DNN | $2.9B | n/m | — | 988.4x | 120.1x | — | — | n/m | -4.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWXT | Revenue | +20.6% | +9.8% | +7.3% |
| EPS | +24.1% | +11.5% | +11.8% | |
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.2% | +13.2% | −23.3% | |
CCJ | Revenue | +4.2% | +12.1% | +8.6% |
| EPS | +7.9% | +69.6% | +26.2% | |
UEC | Revenue | −61.4% | +301.4% | +159.3% |
| EPS | +51.4% | −73.5% | −428.1% | |
UUUU | Revenue | +128.1% | +88.3% | +62.7% |
| EPS | −37.3% | −160.5% | +170.0% | |
NXE | Revenue | −68.7% | +131.4% | +32282.1% |
| EPS | −38.6% | −10.8% | +37.8% | |
OKLO | Revenue | — | +252.7% | +552.9% |
| EPS | +57.1% | +9.6% | +13.5% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% | |
CEG | Revenue | +36.6% | +2.6% | +5.5% |
| EPS | +28.7% | +10.1% | +26.3% | |
DNN | Revenue | +394.2% | −27.3% | +1699.7% |
| EPS | −30.5% | −73.1% | −363.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
BWX Technologies makes the reactors, fuel and missile launch tubes for the US Navy's submarines and carriers, and it spent the summer taking orders. Backlog stood at $8.4bn at the end of June, up 40% year over year on a trailing book-to-bill of 1.7 times, and on August 3 the company raised its full-year revenue, adjusted EBITDA, adjusted earnings and free-cash-flow guidance. On August 26 the US Army selected its 20-megawatt BANR reactor for the Janus program, a set of agreements worth up to $2.2bn with fixed-price milestones running through 2031.
The shares are down 28.2% over ninety days, the worst of the three large listed nuclear-fuel names. BWXT neither mines nor enriches uranium — it is classified in aerospace and defense, and its largest business is paid on cost-reimbursable government contracts. That makes its decline the test of what has actually been marked down this month: the economics of the nuclear fuel cycle, or the number of years until the cash arrives.
What the sellers can point to
June-quarter revenue rose 18% to $901.6m, but gross margin fell to 22.4% from 25.1% and reported operating income fell 12.2% to $89.9m — the fourth consecutive quarter of rising revenue and falling operating profit. Mix explains it. Government Operations, $601.3m of the quarter, grew 2% at a 17.6% segment margin; Commercial Operations grew 72% to $302.5m at 8.0%. Under cost-reimbursable naval contracting reported revenue rises when costs rise, so the naval line is not a demand reading. Management cut the commercial margin guide to about 13% from about 14%, pushing recovery to 2027, and said on the August 3 call it expects "at least one new build nuclear equipment order by year-end" — meaning none had been booked at the half-year. On July 31 it agreed to sell its medical radioisotope business to Nordic Capital in a deal valued at up to $800m.
The other two had reasons of their own
Every nuclear name fell over the thirty sessions to September 18 while the S&P 500 tracker lost 1.4%: Centrus 21.0%, BWXT 14.9%, Cameco 7.9%. The week contained a Federal Reserve rate increase on September 16 and a ten-year Treasury yield that settled back above 5%. The commodity went the other way. The long-term uranium contract price reached $94 a pound at the end of June, an 18-year high, and Kazatomprom plans to cut 2026 output by roughly 10%.
Centrus Energy, the only US-owned commercial enricher and the sole domestic source of high-assay low-enriched uranium, fell on a dated event of its own: a $500m offering of stock and warrants priced September 9, including immediately exercisable warrants over as many as 6,992,382 shares — about 31% of the 22.5m diluted shares reported for the fourth quarter of 2025. The stock closed at $185.38 on September 8 and $145.23 on September 18. The underlying quarter pulled the same way: revenue up 14% to $176.1m, gross profit down 7.4%, separative work unit volumes down 23% with unit costs up 13%. At roughly 57 times both trailing and forward earnings, with consensus 2026 earnings per share down 43%, the shares embed no growth. Its $4.5bn backlog runs to 2040, but its largest enrichment supplier is Russia's TENEX, whose material is banned from January 1, 2028, and its own Piketon plant is guided to commercial production in 2029.
Cameco fell least, and the half of it that sells pounds improved: average realized price up 15% to C$93.13 a pound in Canadian dollars, about 28m pounds a year committed through 2030, and raised outlooks for realized price and revenue. "We are back into a mid-'90s long-term uranium price on its way to three digits likely, and this is in the absence of replacement rate demand," chief operating officer Grant Isaac told investors on July 31. The damage sat in the 49% stake in Westinghouse, whose contribution to Cameco's adjusted EBITDA fell to $163m from $352m — the prior year carried roughly $170m from a Czech construction milestone — and whose five-year growth framework was withdrawn outright. Cameco trades at 59.2 times forward earnings and 156.7 times trailing, the trailing figure having risen as profit fell faster than the price. Westinghouse confidentially filed a draft registration statement on July 31 for a US listing.
The verdict
Two of the three declines are earned by events with dates on them. BWXT's is only partly so: falling margins and an unbooked new-build order justify some compression, and its forward multiple has been cut by roughly a third, from about 47 times in May to 31.1 times, even as consensus put 2026 earnings at $4.74 a share. What the business does not explain is a rising order book and four raised forecasts being valued a third lower. The likelier reading is that the market is repricing the date rather than the contract book — cash flows that begin in the 2030s against a long bond above 5% — and that it is selling everything standing near a reactor without asking how each one is paid.
BWXT has promised its first new-build nuclear equipment order before the end of the year. Until it lands, the strongest fact in the company's favor is a delivery schedule in the next decade — and a schedule is precisely what the bond market has spent this month repricing.