

Moelis Grew 12%, Houlihan Lokey Fell 15.6%; the Market Marked Both Down as One Trade
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The countercyclical hedge that is supposed to protect an advisory firm through a rate shock failed at the house built on it. Houlihan Lokey's restructuring revenue fell 8% in the June quarter even as US Chapter 11 filings rose 37% year over year in the first quarter of 2026, and PJT Partners booked record restructuring revenue in the same period.
Moelis, the pure success-fee firm that should be suffering, grew revenue to $409.4m with its adjusted compensation ratio falling to 65.8% from 69.0% and an announced pipeline more than 80% larger than a year earlier. Both were sold with the group in September after Bank of America guided fees lower and the Federal Reserve raised rates.
Moelis is the name whose business and price now disagree. Houlihan Lokey's de-rating — about eight turns of multiple, with consensus earnings now being cut — is largely earned.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MC | Moelis | Specialized Investment Banking | 🟢 Cont. Bull | −11.4% | −19.4% |
HLI | Houlihan Lokey | Specialized Investment Banking | 🔴 Cont. Bear | +2.6% | −35.8% |
| Compared against · context, not the story | |||||
PJT | PJT Partners | Specialized Investment Banking | 🌱 Emerging Bull | −9.6% | −16.2% |
PWP | Perella Weinberg Partners | Specialized Investment Banking | 🔴 Cont. Bear | −18.8% | −40.4% |
LAZ | Lazard | Specialized Investment Banking | ⚠️ Emerging Bear | −13.2% | −29.1% |
EVR | Evercore | Wealth Management & Advisory | 🟢 Cont. Bull | −9.8% | −22.3% |
BAC | Bank of America | Global Investment Banking & Markets | 🟢 Cont. Bull | −8.8% | +15.1% |
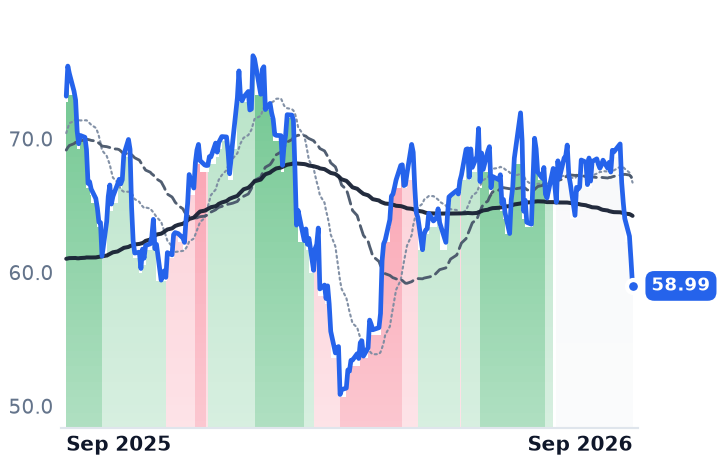
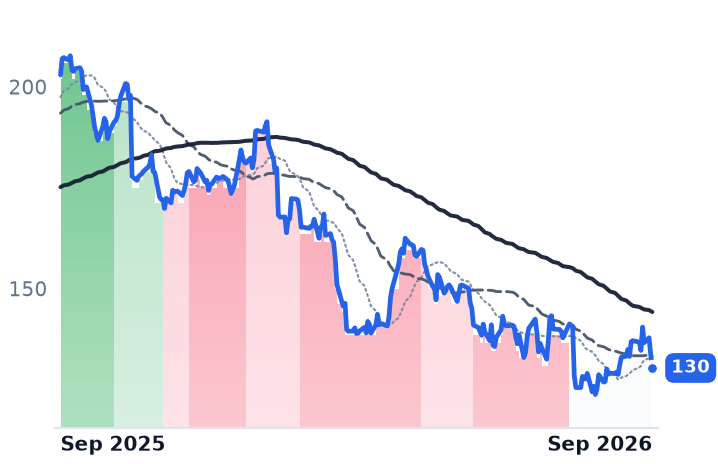
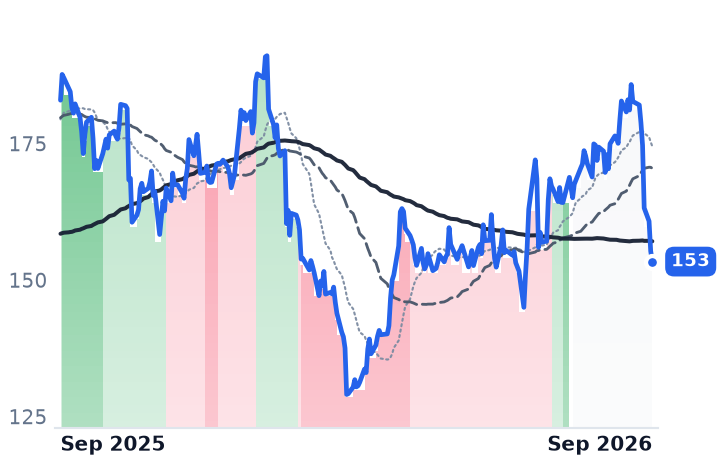
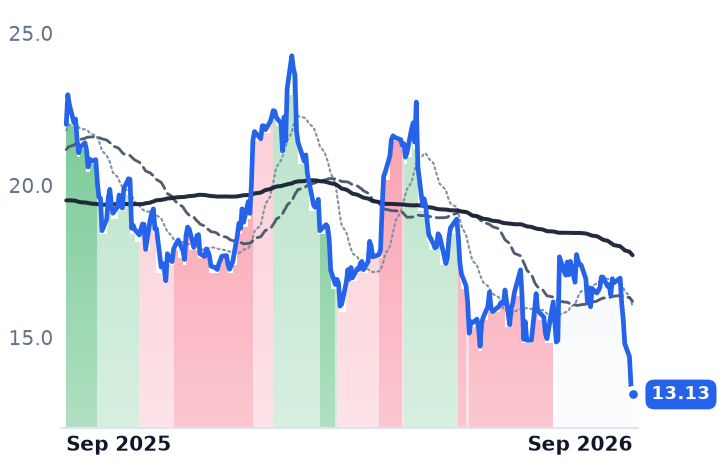
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MC | $4.4B | 19.5x | 19.1x | 2.8x | 2.5x | 4.0x | 3.6x | 14.1x | 10.0% |
HLI | $9.1B | 21.4x | 18.8x | 3.6x | 3.5x | 7.1x | 6.8x | 14.9x | 5.3% |
PJT | $4.1B | 17.9x | 20.1x | 2.2x | 2.1x | 3.4x | 3.2x | 10.0x | 16.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWP | $1.3B | 39.1x | 12.7x | 1.8x | 1.5x | 1.5x | 1.2x | 29.1x | 7.0% |
LAZ | $3.9B | 17.4x | 17.8x | 1.2x | 1.2x | 2.5x | 2.5x | 12.3x | 18.0% |
EVR | $10.7B | 14.3x | 14.1x | 2.2x | 2.2x | 2.3x | 2.2x | 9.9x | 15.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BAC | $353.2B | 11.4x | 11.2x | 2.0x | 2.9x | 3.2x | 4.6x | 11.8x | 16.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MC | Revenue | +16.1% | +17.3% | +8.5% |
| EPS | +12.1% | +27.9% | +8.7% | |
HLI | Revenue | +13.2% | −1.2% | +18.7% |
| EPS | +28.7% | −9.9% | +25.2% | |
PJT | Revenue | +14.4% | +10.6% | +4.4% |
| EPS | +18.2% | +13.4% | +10.4% | |
PWP | Revenue | +20.8% | +23.9% | +10.4% |
| EPS | +63.7% | +45.9% | +18.3% | |
LAZ | Revenue | +12.3% | +19.5% | +7.1% |
| EPS | −5.1% | +72.6% | +26.2% | |
EVR | Revenue | +32.1% | +12.7% | +5.6% |
| EPS | +45.6% | +15.6% | +10.5% | |
BAC | Revenue | +9.4% | +4.9% | +4.7% |
| EPS | +16.9% | +13.1% | +14.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The hedge that is supposed to protect an advisory firm from a rate shock — restructuring work, billed on retainers to distressed debtors — failed where it was most expected. Houlihan Lokey's restructuring revenue fell 8% in the June quarter even as US Chapter 11 filings rose 37% year over year in the first quarter, and PJT Partners booked record restructuring revenue in the same period.
Moelis & Company, which advises on mergers, recapitalizations and capital raises and owns no trading book, no loan book and no asset-management arm, collected $409.4m in the June quarter, 12% more than a year earlier, and widened its operating margin to 17.8% from 16.6%. On the 29 July call, conducted by chief executive Navid Mahmoodzadegan and chief financial officer Chris Callesano, management told investors: "Our announced pipeline had increased over 80% versus the prior year period. In addition, new business origination accelerated in the second quarter and we entered the back half of the year with a record total pipeline," according to a transcript of the call.
The listed independent advisers were nonetheless sold as a single instrument in September. Underneath that single trade the franchises are moving in opposite directions — and the countercyclical restructuring annuity that is supposed to make a house like Houlihan Lokey ownable through a rate shock is being earned by a rival.
One cost line, and it improved
A dollar at Moelis is earned one way: a success fee, struck as a percentage of transaction value and collected at closing, months after the announcement. Against it sits essentially one cost, compensation, promised to managing directors before the revenue arrives. In the June quarter that line took 65.8% of revenue on an adjusted basis, down from 69.0%, the firm reported, while six managing directors joined during 2026 and six more committed, in private credit, securitization, energy and healthcare information technology.
The hedge paid somebody else
Houlihan Lokey, worth roughly $9.1bn and the industry's designated restructuring specialist, runs Corporate Finance, Financial Restructuring — retainers plus completion fees for advising debtors and creditor committees — and Financial and Valuation Advisory. June-quarter revenue fell 15.6% to $511m, split Corporate Finance down 24%, restructuring down 8%, valuation advisory up 13%. Adjusted earnings fell to $1.35 a share from $2.14 — leverage running backwards against a fixed pay stack — with management blaming extended transaction timelines on larger-fee assignments. Chief executive Scott Adelson called the quarter "a temporary disruption and not a fundamental resetting of our outlook."
The demand was there. Chapter 11 filings rose 37% year on year in the first quarter of 2026, and Fitch put the private-credit default rate at 6.0% in April. PJT Partners, the advisory firm spun out of Blackstone, booked record second-quarter revenue of $486m, up 20%, with its restructuring team ranked first in global announced and completed restructurings. Houlihan Lokey's restructuring managing-director count was 58, flat on the year.
Paid on count, not on value
The Corporate Finance shortfall looks like mix. Announced global deal value ran $3.19trn through July, up 36%, while transaction count is tracking about 42,000 for the year, down 13%, and deals above $5bn took almost half of all value. A per-transaction mid-market house is paid on count. Houlihan Lokey's Corporate Finance bench grew to 260 managing directors from 244 while that segment's revenue fell 24% — roughly a 29% drop in revenue per banker. Moelis's 2026 mandates, meanwhile, run to Clear Channel Outdoor's $6.2bn sale and Kennedy Wilson's $9.5bn take-private.
What the market did with it
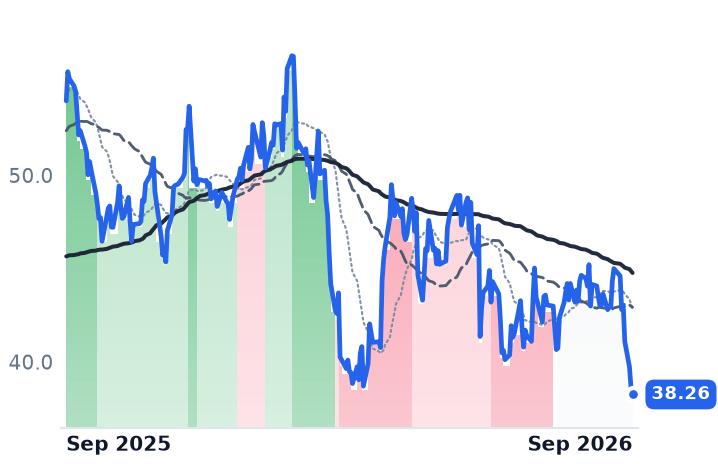
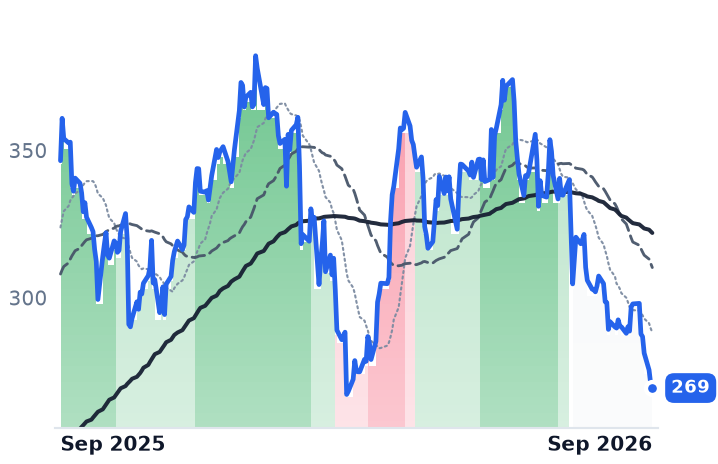
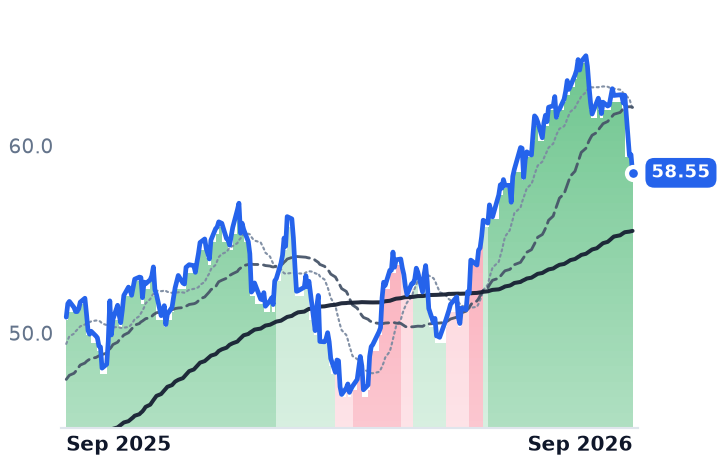
Between 8 and 16 September Moelis fell 15.2%, against 4.7% at Houlihan Lokey, which was the only one of the six listed advisers higher over the past month. The trigger was dated: Bank of America chief executive Brian Moynihan said on 14 September that third-quarter investment banking fees would be $1.6bn to $1.8bn, down 11% to 21%, and the Federal Reserve raised its target range to 3.75%–4% on 16 September, its first increase in three years. Over twelve months Houlihan Lokey is down 35.8% from a peak set last September; Moelis is down 20.5%.
Moelis trades at 19.1x forward earnings, on consensus of $3.08 a share this year rising to $3.94 next. A year ago the same estimate implied roughly 24x. The estimate has not moved; the multiple has.
Houlihan Lokey trades at 18.8x forward — but that rests on consensus adjusted earnings of $6.94 for the March-2027 year, 9.9% below the prior year's $7.70, against about 26x on the comparable measure a year ago. Of its 36% decline, roughly 29 points is multiple compression and about 10 points lowered estimates.
So the two houses now cost nearly the same for earnings streams pointed in opposite directions. Houlihan Lokey's de-rating is earned and mostly done: the business genuinely shrank, it is losing share of a restructuring pool that is growing, and it is no longer obviously expensive. Moelis's is explained by nothing in its own accounts. What its price embeds is a conversion failure — the argument UBS and Keefe, Bruyette & Woods made in downgrading the stock, that the announced pipeline never closes at these rates. Only completed fees settle that, and they arrive a quarter or two late by construction.
Houlihan Lokey's restructuring bench still numbers 58 managing directors, unchanged, heading into a default cycle its competitors are already billing.