

Centrus Sold $500m of Stock and Warrants Over 31% of Its Shares as Uranium Hit $90
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A fuel-cycle complex whose long-term contract price sits at an 18-year high just watched one of its members lose a fifth of its value in seven sessions, and the cause was on the company's own wire.
Centrus Energy, which sells enrichment services rather than uranium, issued stock plus warrants over 6,992,382 shares — struck between $226.86 and $362.98 — on 9 September, the same day it announced a long-term fuel partnership with reactor developer Radiant. Its enrichment volumes fell 23% in the June quarter while revenue rose 14% on uranium resales. Cameco, the contracted producer, realised C$93.13 a pound, up 15%, and fell anyway; what shrank there was Westinghouse, whose contribution to earnings more than halved.
Both order books grew through the decline and both stocks still trade near 60x forward earnings. Unhedged UEC and Energy Fuels and cost-plus BWX Technologies fell alongside them, which points at discount rates rather than fuel demand.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
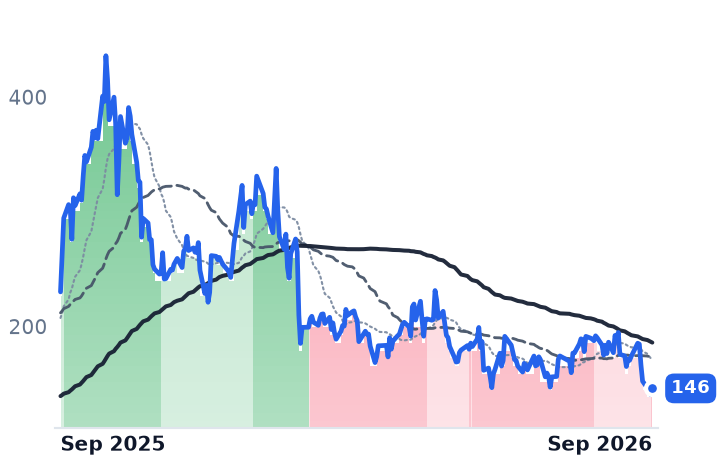
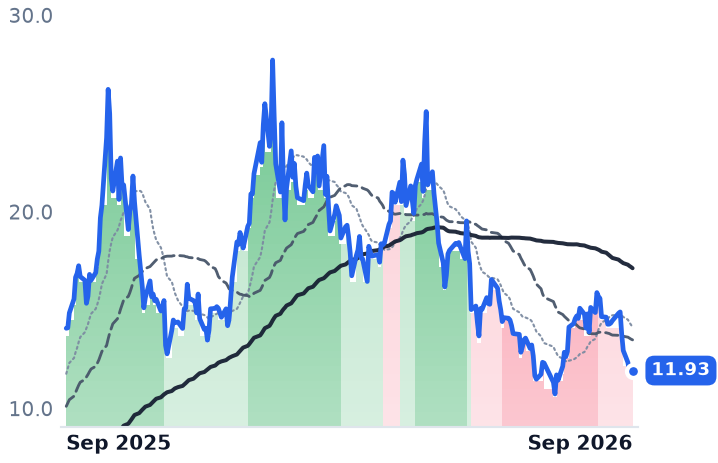
LEU | Centrus Energy | Uranium | ⚠️ Emerging Bear | −16.6% | −36.6% |
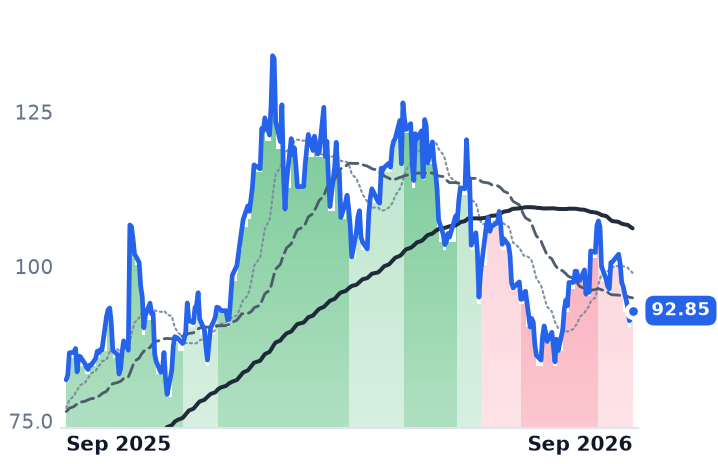
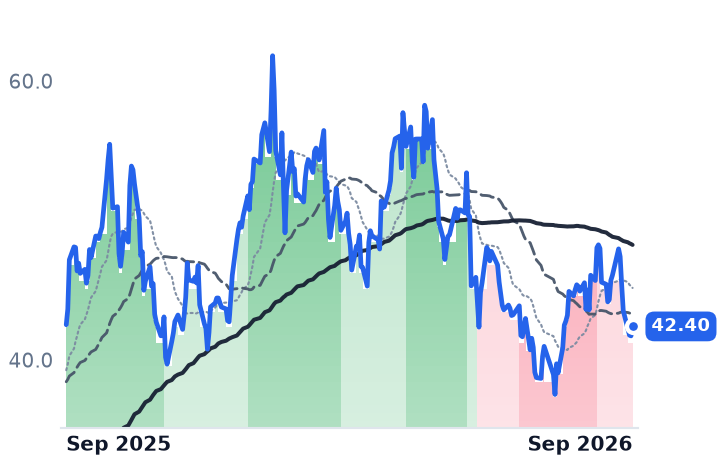
CCJ | Cameco | Uranium | ⚠️ Emerging Bear | −2.8% | +13.7% |
| Compared against · context, not the story | |||||
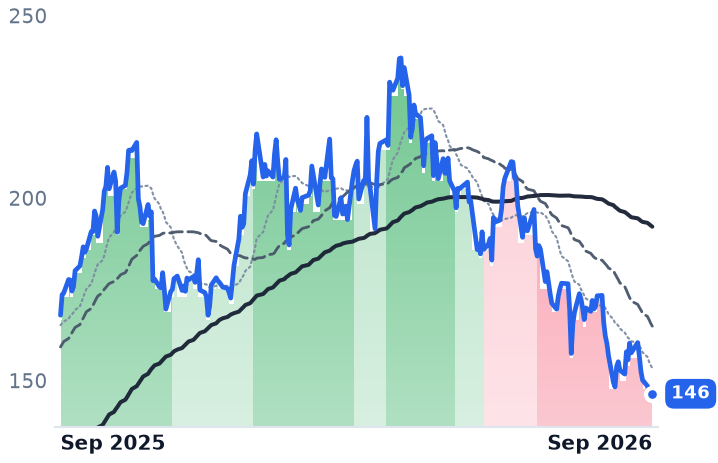
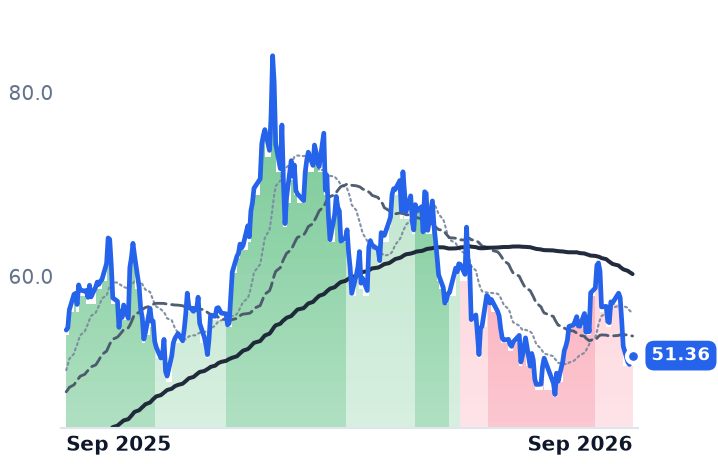
BWXT | BWX Technologies | Naval & Shipbuilding | ⚠️ Emerging Bear | −11.8% | −12.8% |
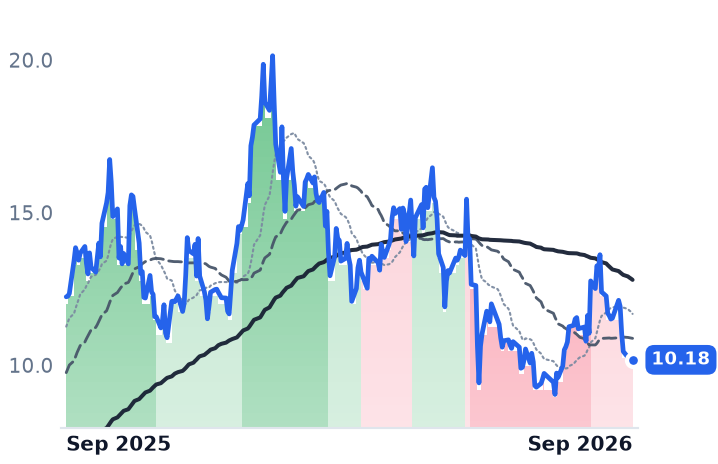
UEC | Uranium Energy | Uranium | ⚠️ Emerging Bear | −5.6% | −16.9% |
UUUU | Energy Fuels | Uranium | ⚠️ Emerging Bear | −15.3% | −15.3% |
URA | Global X - Uranium ETF | Asset Management | ⚠️ Emerging Bear | −2.8% | −0.3% |
URNM | Sprott Uranium Miners ETF | Asset Management | ⚠️ Emerging Bear | −4.7% | −5.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $2.8B | 59.7x | 58.9x | 6.0x | 6.0x | 25.7x | 25.9x | 29.6x | -7.8% |
CCJ | $40.4B | 158.8x | 60.0x | 16.3x | 11.3x | 59.0x | 41.1x | 65.4x | 0.9% |
BWXT | $13.5B | 37.9x | 31.0x | 3.8x | 3.5x | 17.4x | 16.1x | 26.9x | 2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UEC | $5.0B | n/m | — | 247.9x | 48.9x | 585.8x | 115.5x | n/m | -2.4% |
UUUU | $3.0B | n/m | — | 28.3x | 22.5x | 65.5x | 52.0x | n/m | -3.7% |
URA | $3.9B | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
URNM | $1.1B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.2% | +13.2% | −23.3% | |
CCJ | Revenue | +4.2% | +12.1% | +8.6% |
| EPS | +7.9% | +69.6% | +26.2% | |
BWXT | Revenue | +20.6% | +9.6% | +7.0% |
| EPS | +24.1% | +11.6% | +11.7% | |
UEC | Revenue | −61.4% | +301.4% | +159.3% |
| EPS | +51.4% | −73.5% | −428.1% | |
UUUU | Revenue | +128.1% | +88.3% | +62.7% |
| EPS | −37.3% | −160.5% | +170.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Centrus Energy raised half a billion dollars on 9 September and the market has spent the seven sessions since deciding what it cost. The Bethesda, Maryland company — which sells separative work units, the unit of enrichment service, rather than uranium — priced an underwritten offering of Class A stock and warrants at a combined $199.64 per unit, with common warrants over up to 6,992,382 further shares at exercise prices from $226.8625 to $362.98. Against the 22.5m diluted shares Centrus reported for the fourth quarter of 2025, that overhang is roughly 31% of the company. The stock closed at $185.38 on 8 September and $146.00 on 17 September.
That is the news, and it landed in a week when everything around it fell too. Uranium spot was $90 a pound on 14 September, the long-term contract price near an 18-year high, and Kazatomprom — the world's largest producer — has said it will cut about 8 million pounds from 2026 output, roughly 5% of global supply. Supply tightened; the equities broke. Between 8 and 17 September, Energy Fuels fell 19.6%, Uranium Energy Corp 16.1%, Cameco 8.9% and BWX Technologies 8.7%. What moved in that window was the cost of money: the 30-year Treasury yield reached a 19-year high in August and the 10-year pushed above 5.04% on 15 September, its highest since 2007, which is the discount rate applied to cash flows that begin in the 2030s.
Two ways to earn a fuel-cycle dollar
The two protagonists are paid on different meters, and both meters read better than their share prices. Centrus's June-quarter revenue rose 14% to $176.1m while gross profit fell 7.4% to $49.9m and operating income fell 69% to $10.4m. The growth was mix: enrichment revenue rose 22% to $153.4m on uranium resales of $53.4m, with actual separative work volumes down 23%, pricing up 3% and unit costs up 13%. Its government-funded half — Technical Solutions — fell 21% to $22.7m after the Department of Energy high-assay low-enriched uranium operations contract that paid for it expired on 30 June. Set against that: total backlog nearly doubled to $4.5bn stretching to 2040, $2.4bn of the enrichment piece now under definitive rather than contingent agreements, $1.9bn of cash, and the same-day long-term partnership with Radiant to fuel Kaleidos microreactors. Commercial production at Piketon is guided to 2029. Management told the August call that utilities remain in a "wait-and-see" posture until centrifuges are installed.
Cameco, the largest listed uranium producer, is the opposite case: its realised price rose while its stock fell. Second-quarter realisation was C$93.13 a pound, up 15% — about US$68, against that $90 spot — with 2026 unit costs guided to $63.00–$67.50 and term contracts covering average deliveries above 28 million pounds a year for five years. "We are back into a mid-'90s long-term uranium price on its way to three digits likely, and this is in the absence of replacement rate demand," chief operating officer Grant Isaac told investors on the 31 July call. What fell was the other half of the company: Cameco's share of Westinghouse adjusted earnings before interest, taxes, depreciation and amortisation dropped to US$163m from US$352m, and the company withdrew its framework outright — "we are no longer providing a five-year growth outlook for Westinghouse."
What the break did and did not discriminate
If the market were separating contracted pounds from government funding risk, BWX Technologies would have been spared: the naval-reactor and medical-isotope maker grew revenue 18% to $901.6m, carries $8.4bn of backlog, up 40%, and raised all four 2026 guidance lines. It fell with the rest. The likelier reading is a single rates-and-artificial-intelligence-capex trade in names held as data-center power proxies.
So the businesses earn part of this and not the rest. Cameco's per-pound economics are intact and its shares are still up 13.5% over twelve months; what nothing in the contract book explains is a forward earnings multiple of 60x, against roughly 56x in May, on consensus revenue growth of 4.2%. Centrus is the harder case: expensive at 58.9x forward earnings on consensus profit falling to $2.55 a share this year from $3.90, with free cash flow negative while Piketon is built, and now with a third of its share count sitting in warrants above $226.
The backlog belongs to the 2030s. The dilution is dated, priced and already on the record.