

Jan Mikkelsen Guaranteed No Patent Impact; Ascendis Then Gave BioMarin a 20% Royalty
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Ascendis Pharma's hypoparathyroidism drug Yorvipath added €55m of quarterly revenue between March and June, and the group operating margin swung to 18.4% from minus 33.5% a year earlier. The launch is real: roughly 1,000 new U.S. patients a quarter, five consecutive quarters of improving operating margin, no bank or convertible debt.
Then two counterparties repriced it inside three weeks. A 31 August settlement hands BioMarin a fifth of U.S. Yuviwel sales through May 2030, and on 14 September Novo Nordisk's licence to TransCon semaglutide reverted to Ascendis as that collaboration ended.
Cytokinetics is the mirror: the same launch archetype, product revenue up more than fivefold sequentially, but 57 times forward sales and consensus showing no net profit until 2029. One of these two de-ratings looks earned; the other does not.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ASND | Ascendis Pharma A/S | Rare Genetic & Metabolic Diseases | 🟢 Cont. Bull | −4.0% | +21.8% |
CYTK | Cytokinetics, Incorporated | CNS & Neurological | 🟢 Cont. Bull | −6.1% | +41.1% |
| Compared against · context, not the story | |||||
DYN | Dyne Therapeutics | Gene Therapy & Cell Therapy | 🟢 Cont. Bull | −30.2% | +37.7% |
MLTX | MoonLake Immunotherapeutics | Immunology & Autoimmune | 🌱 Emerging Bull | −25.6% | −77.0% |
DNLI | Denali Therapeutics | CNS & Neurological | 🟢 Cont. Bull | −16.5% | +53.2% |
CGON | CG Oncology | Other | 🟢 Cont. Bull | −4.5% | +105.5% |
PCVX | Vaxcyte | Infectious Diseases & Vaccines | 🟢 Cont. Bull | −0.7% | +91.5% |
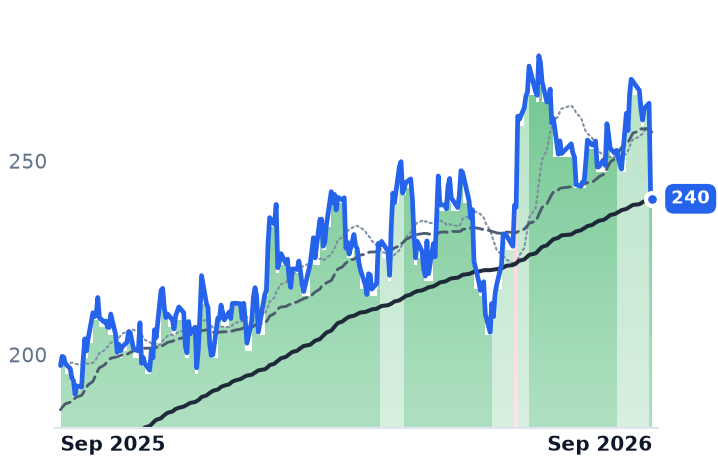
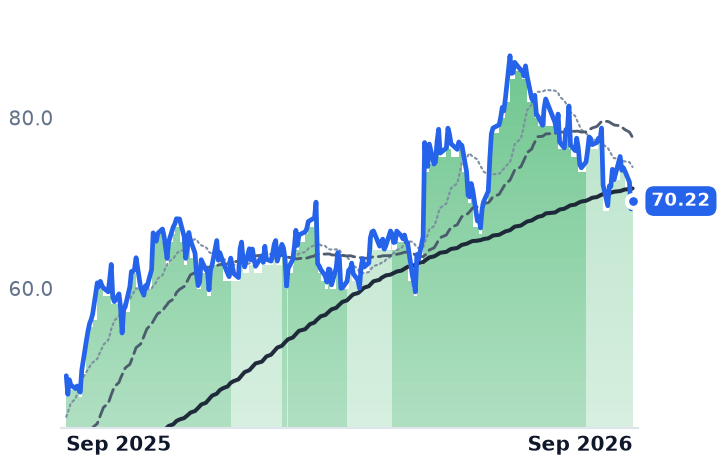
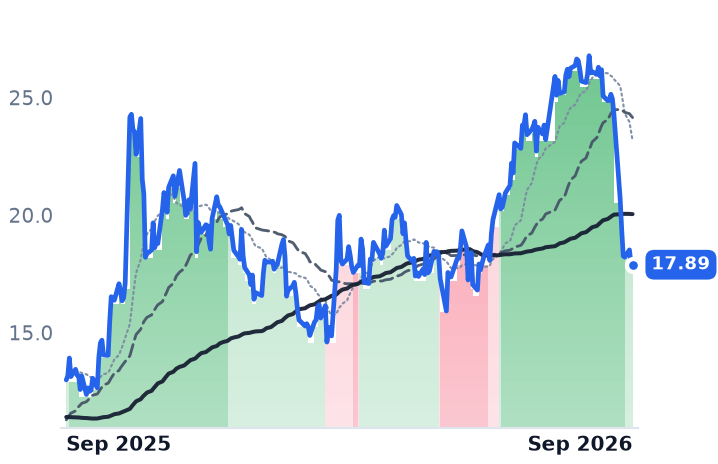
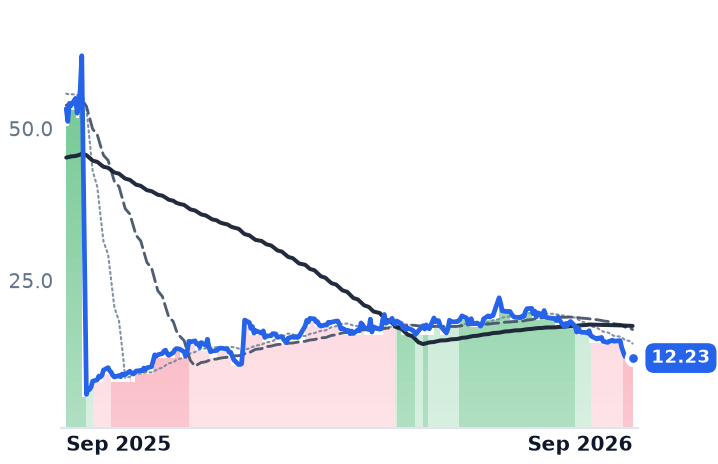
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ASND | $15.3B | 17.8x | 17.2x | 12.7x | 11.2x | 14.1x | 12.4x | 166.4x | 2.5% |
CYTK | $8.6B | n/m | — | 120.5x | 57.1x | 141.8x | 67.2x | n/m | -6.8% |
DYN | $4.7B | n/m | — | n/m | — | — | — | n/m | -10.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MLTX | $1.6B | n/m | — | n/m | — | — | — | n/m | -14.5% |
DNLI | $3.7B | n/m | — | n/m | 104.4x | — | — | n/m | -11.5% |
CGON | $6.3B | n/m | — | — | 568.3x | — | — | n/m | -2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCVX | $8.4B | n/m | — | n/m | 335.4x | — | — | n/m | -14.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ASND | Revenue | +93.3% | +46.1% | +26.7% |
| EPS | −527.6% | −36.5% | +59.5% | |
CYTK | Revenue | +94.9% | +183.6% | +109.5% |
| EPS | −6.8% | −26.1% | −52.9% | |
DYN | Revenue | +43.8% | +5023.7% | +465.7% |
| EPS | −1.3% | −5.6% | −23.8% | |
MLTX | Revenue | — | — | +499.2% |
| EPS | +6.4% | −5.3% | −19.5% | |
DNLI | Revenue | +1299.4% | +204.0% | +150.9% |
| EPS | −18.1% | +0.8% | −24.6% | |
CGON | Revenue | +292.5% | +669.5% | +432.7% |
| EPS | +26.5% | +2.4% | −97.0% | |
PCVX | Revenue | — | +248.6% | +103.3% |
| EPS | +51.9% | −19.8% | −5.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ascendis Pharma, a Danish rare-disease company whose three marketed drugs all run on one chemistry, sold €315m of product in the June quarter — double a year earlier. The operating line moved with it: a margin of 18.4%, against minus 33.5% in the same quarter of 2025, the fifth consecutive quarterly improvement.
What is being tested is not whether the science works but what a launch curve is worth once it stops being a promise. The market pays roughly 11 times forward sales for Ascendis and about 57 times for Cytokinetics, the South San Francisco company whose oral cardiac myosin inhibitor MYQORZO went on sale in January — two versions of the same specialist-launch archetype, priced five-fold apart.
One chemistry, three meters
TransCon is a prodrug: a parent hormone tethered to an inert carrier that releases it slowly, converting a daily injection into a weekly or monthly one. Ascendis sells it three ways and is paid differently by each. Skytrofa, a weekly growth hormone, is roughly flat at €55m a quarter and management guided it to stay stable — it is neither funding the story nor spoiling it.
Yorvipath is the engine. Quarterly revenue has compounded rather than stepped — €143.1m, €187m, €197m and then €252m in the June quarter — on roughly 1,000 unique new U.S. patients a quarter, with the drug available in more than 35 countries. Hypoparathyroidism had never had a replacement hormone, so the meter is not prescriber breadth but whether patients stay: the company cites 82–86% sustained multicomponent response and 95% retention at five years, and spends on patient-access staff rather than sales reach. "The majority of the drop-off is during that titration period in terms of when patients experience the most amount of change and where additional education and a higher touch support model makes sense," Jay Wu, president of Ascendis U.S., told investors on the 13 August call. AstraZeneca's eneboparatide hit its Phase 3 primary endpoint this year but was not approved as of September; GlobalData models Yorvipath at $1.66bn of 2030 sales against $492m for the challenger.
The third meter started this quarter. Yuviwel, for pediatric achondroplasia, booked €8m in its first partial quarter with more than 220 patient enrollments and over 65% of them reimbursement-approved. On that same 13 August call, chief executive Jan Mikkelsen dismissed BioMarin's patent suit: "whatever has happened, it will not have any material impact on Ascendis pathway. I can guarantee that." Eighteen days later Ascendis settled, agreeing to pay BioMarin 20% of U.S. Yuviwel net sales retroactive to first commercial sale, and 18% in Europe, Brazil and South Korea, until May 2030. Every dollar of the newest launch now carries a burden the June accounts did not.
What the tape has and has not paid for
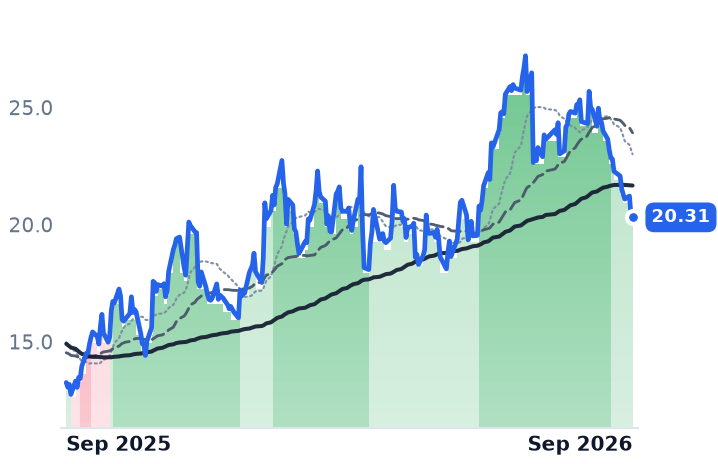
Ascendis is up 3.9% over ninety days and 21.8% over twelve months, against revenue that nearly doubled, and its 50-day average crossed above its 200-day on 14 September. The next session the shares fell 9.49%, from $264.92 to $239.77 on more than three times average volume, immediately after Ascendis disclosed that all licences granted to Novo Nordisk in metabolic and cardiovascular disease — including once-monthly TransCon semaglutide — revert to Ascendis with no continuing obligations either way. Management had described that programme as advancing four and a half weeks earlier. No source attributes the move, but it is the only dated company event in the window.
The wider group of small- and mid-cap biotechs flagged as acquisition candidates has fallen about 10% in thirty days, and the decline sits almost entirely in the names with no product to count: Dyne Therapeutics down 30.2% after a Novartis muscle-wasting failure read across to myotonic dystrophy developers on 8 September, MoonLake down 25.6%, Denali down 16.5%. The commercial-stage members average a loss of 1.7%.
The mirror at 57 times sales
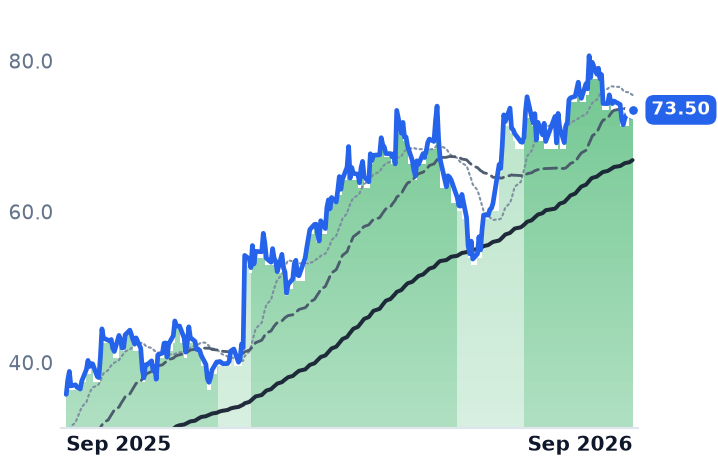
Cytokinetics' launch is inflecting too. MYQORZO went from $4.8m to $25.3m of net product revenue between the March and June quarters, with new-to-brand share above 40% and more than 700 prescribers, over half of them first-time or low-volume writers. "Just 5 months into the commercial launch of MYQORZO, we are demonstrating increased velocity that's exceeding expectations," chief executive Robert Blum said on 6 August. The friction is measurable: about 2,000 prescriptions in the quarter converted to 1,500 patients dispensed, the gap being risk-evaluation certification and prior authorization stretching to weeks.
The difference is what it costs to get there. The quarterly operating loss widened to $175.9m, combined research and selling expense guidance was raised to $860–890m, and the launch is funded by equity — a May offering raised about $760m net. Consensus shows no net profit until 2029. When the ACACIA-HCM trial hit both primary endpoints in non-obstructive disease, roughly doubling the treatable population, the shares fell about 7% on the day the data were presented in Munich.
The verdict
Cytokinetics' slide is a valuation doing its job: paying 57 times forward sales for revenue that arrives after three more years of losses leaves nothing for good news to buy. Ascendis is the opposite case — the doubling, the margin turn, the guided €500m-plus of 2026 operating cash flow and a debt-free balance sheet are all earned, and the share price has credited almost none of it. What the last month legitimately took back is narrower than the chart suggests: a fifth of Yuviwel's U.S. economics now belongs to BioMarin, and the metabolic option Novo Nordisk was carrying came home unfunded.
The guarantee is the tell. Ascendis's chemistry does what the label says; what each dollar of it earns is decided by counterparties — a court, a partner, a payer — and two of the three moved in three weeks.