

Wholesale Used-Car Volumes Fell 8% in July, and Copart Paid $1.9bn to Enter the Channel
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
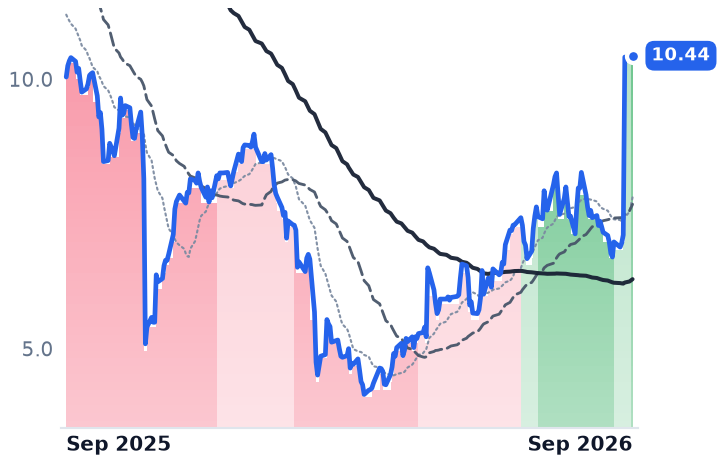
The dealer-to-dealer wholesale used-car market is contracting in the one unit its operators are actually paid on — transactions — and the response has been consolidation rather than expansion. Copart agreed on 10 September to buy ACV Auctions for $10.50 a share in cash, about $1.9bn, a month after ACV was buying back its own stock as undervalued.
ACV's June-quarter marketplace units, 211,472, were essentially flat year on year; all of its 10.4% revenue growth came from price per unit and attached services, and gross margin fell to 49.88% from 52.90%. Wholesale prices are not rescuing anyone either — the Manheim index sits 0.4% above a year ago.
What has genuinely improved is subprime credit, not volume. OPENLANE, the last independent digital wholesale platform, was awarded no consolidation premium at all.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
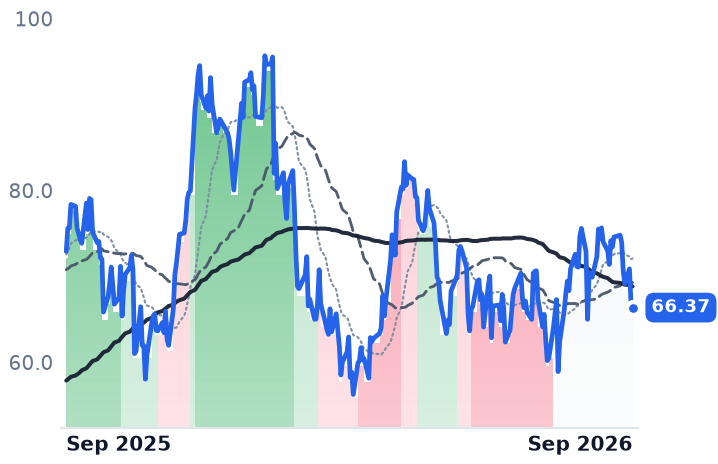
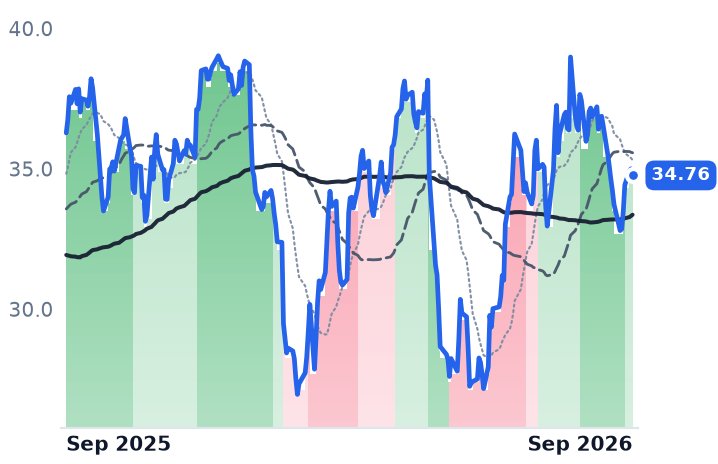
ACVA | ACV Auctions | Used Vehicle Specialists | 🌱 Emerging Bull | +32.8% | +3.9% |
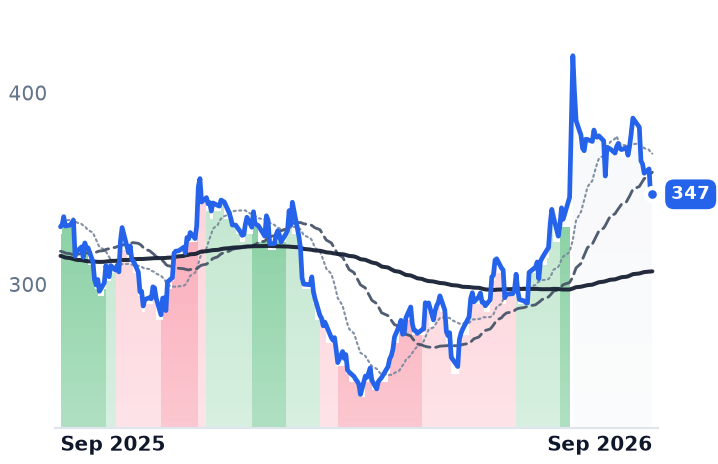
KMX | CarMax | Used Vehicle Specialists | 🌱 Emerging Bull | −0.4% | −1.7% |
| Compared against · context, not the story | |||||
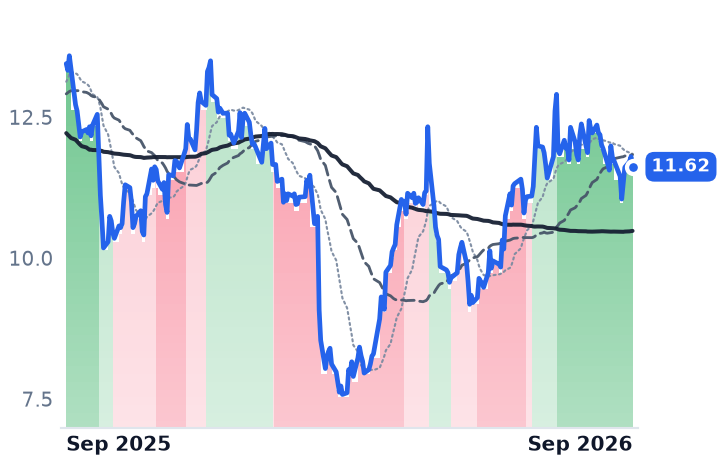
CPRT | Copart | Vehicle & Asset Auctions | 🔴 Cont. Bear | −4.0% | −34.4% |
OPLN | OPENLANE | Used Vehicle Specialists | 🟢 Cont. Bull | −1.3% | +22.7% |
CVNA | Carvana | E-Commerce Platforms | ⚠️ Emerging Bear | −8.9% | −9.0% |
LAD | Lithia Motors | Traditional Dealership Groups | 🌱 Emerging Bull | −7.4% | +5.1% |
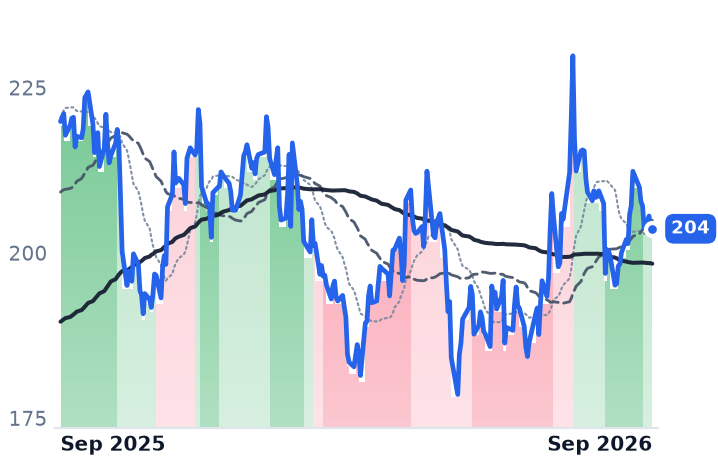
AN | AutoNation | Traditional Dealership Groups | 🟢 Cont. Bull | −1.8% | −7.4% |
PAG | Penske Automotive | Traditional Dealership Groups | 🌱 Emerging Bull | −1.6% | +23.6% |
CARG | CarGurus | E-Commerce Platforms | 🟢 Cont. Bull | −3.4% | −4.2% |
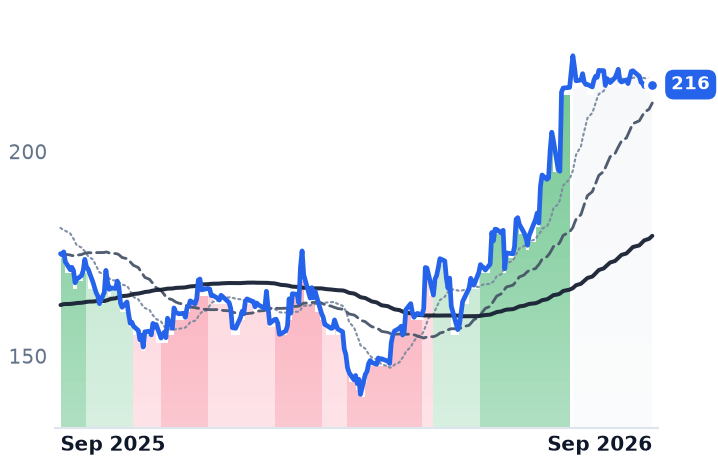
CARS | Cars.com | Marketplace & Local Services | 🌱 Emerging Bull | −3.1% | −13.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ACVA | $1.8B | n/m | 51.2x | 2.3x | 2.1x | 3.6x | 3.4x | n/m | 0.3% |
CPRT | $28.6B | 19.8x | 18.9x | 6.1x | 5.9x | 13.7x | 13.2x | 13.0x | 4.4% |
OPLN | $3.7B | 103.6x | 24.4x | 1.8x | 1.7x | 4.4x | 4.1x | 9.9x | 9.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KMX | $8.5B | 37.0x | 22.0x | 0.3x | 0.3x | 3.1x | 3.0x | 23.9x | 11.8% |
CVNA | $72.8B | 30.0x | 44.4x | 3.2x | 2.6x | 16.2x | 13.1x | n/m | 1.0% |
LAD | $8.3B | 12.4x | 10.4x | 0.2x | 0.2x | 2.0x | 2.0x | 17.4x | -6.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AN | $6.9B | 9.4x | 9.5x | 0.3x | 0.2x | 1.4x | 1.4x | 11.1x | 0.2% |
PAG | $14.3B | 16.1x | 16.1x | 0.4x | 0.4x | 2.7x | 2.7x | 13.7x | 4.1% |
CARG | $2.8B | 18.1x | 11.3x | 2.9x | 2.7x | 3.2x | 3.0x | 10.4x | 10.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CARS | $550.6M | 21.5x | 4.5x | 0.8x | 0.8x | 0.9x | 0.9x | 6.0x | 28.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ACVA | Revenue | +12.0% | +11.1% | +14.6% |
| EPS | +21.1% | +68.9% | +61.8% | |
CPRT | Revenue | −0.0% | +4.3% | +6.2% |
| EPS | +2.3% | +3.3% | +8.9% | |
OPLN | Revenue | +14.5% | +8.0% | +8.3% |
| EPS | +15.7% | +20.0% | +53.1% | |
KMX | Revenue | −2.7% | +5.8% | +2.1% |
| EPS | −17.8% | +0.5% | +14.7% | |
CVNA | Revenue | +38.8% | +25.6% | +20.9% |
| EPS | +50.1% | +37.0% | +33.9% | |
LAD | Revenue | +1.8% | +3.6% | +5.0% |
| EPS | +2.6% | +16.7% | +12.2% | |
AN | Revenue | −0.4% | +3.2% | +2.1% |
| EPS | +9.1% | +13.5% | +13.9% | |
PAG | Revenue | +6.7% | +2.5% | +2.2% |
| EPS | +1.0% | +6.6% | +7.0% | |
CARG | Revenue | +8.4% | +9.3% | +7.3% |
| EPS | +13.6% | +15.9% | +9.5% | |
CARS | Revenue | +0.9% | +2.5% | +2.2% |
| EPS | +20.8% | +18.1% | −12.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Copart agreed on 10 September to acquire ACV Auctions for $10.50 a share in cash, valuing the company at roughly $1.9bn, according to the merger announcement. The buyer runs salvage auctions, mostly for insurers disposing of totaled cars. The seller runs a digital marketplace where franchised and independent dealers sell used vehicles to one another, taking a fee per transaction plus inspection, transport and short-term financing, and never owning the car. The premium was 45.4%; ACV shares gapped from 7.11 to 10.41 in a single session on 114.9m shares, against about 1.1m the day before.
The reason the price is the less interesting number: the channel Copart is buying into is shrinking in the only unit that pays it. Neither ACV nor its rivals are paid for used-car prices. They are paid per car that changes hands, and cars are changing hands less often.
The dislocation that stops a car from selling
When wholesale values slide, sellers anchor to last month's price and buyers bid this month's. ACV management put a figure on the gap in the June quarter — roughly 600 basis points between what sellers wanted and what buyers would pay, which knocked 300 to 350 basis points off auction conversion rates. The market-wide count went with it: dealer wholesale volumes, per the National Auto Auction Association, were down about 6% year on year in June and down 8% in July, a figure ACV's incoming chief financial officer Timothy Fox cited directly on the 10 August call.
Prices are not compensating. The Manheim Used Vehicle Value Index stood at 208.2 in August, up 0.4% on the year and down 0.9% on the month.
ACV grew revenue without growing transactions
ACV sold 211,472 marketplace units in the June quarter, essentially flat against roughly 210,000 a year earlier. Revenue still rose 10.4% to $213.9m — all of it from price per unit and attach. Auction revenue per unit rose 6% to $554; the transport, capital and data businesses grew 17%, with transport up 19% on 125,000 deliveries. Gross profit grew 4.1%, gross margin fell to 49.88% from 52.90%, and the quarter produced a $6.0m operating loss.
"We delivered record adjusted EBITDA per unit, increasing 11% year over year in Q2," outgoing chief financial officer Bill Zerella told investors on 10 August. Per-unit economics were the story precisely because units were not. A $50m accelerated buyback was in progress that day, with management calling the shares undervalued. One month later the board agreed to sell at $10.50, or about 2.2x consensus revenue for the year.
The name that did not move
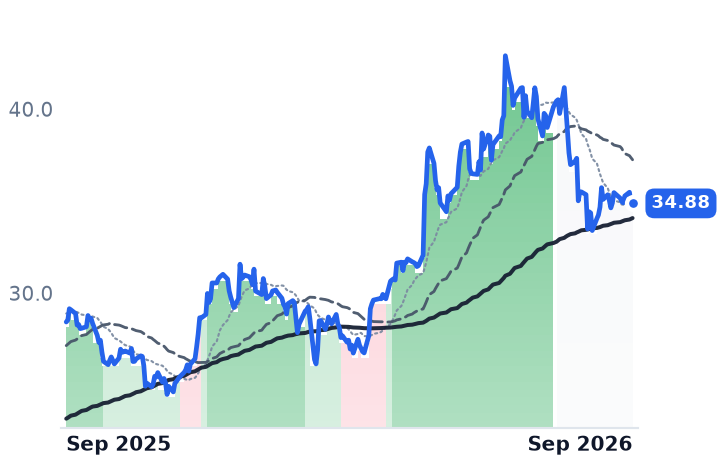
OPENLANE, the former KAR Auction Services, runs the other listed digital wholesale marketplace plus a floorplan lending arm for independent dealers. Its only listed competitor being consolidated should have been worth something. It rose 1.1% on deal day and closed 16 September a shade below its pre-announcement price. Its June quarter shows the same squeeze from the other side: revenue up 15.1% to $554.6m, gross margin down to 40.12% from 42.41%, operating income down 19.4%. It trades at 9.9x enterprise value to earnings before interest, tax, depreciation and amortization, against 13.0x for Copart.
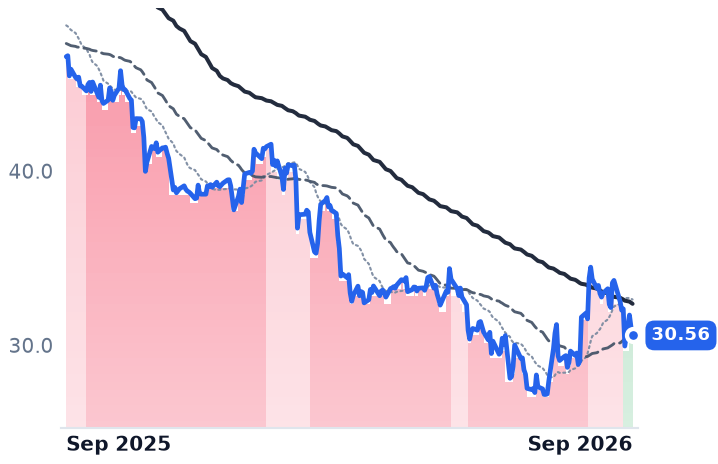
Copart itself fell 6.65% on the announcement and remains 4.8% below its pre-deal close. Its own growth had stalled — fiscal 2026 revenue of $4.666bn was up 0.4%, net income down 4.4% — at 19.8x trailing and 18.9x forward earnings. Buying the dealer channel is what a salvage auctioneer does when its own lane stops widening.
What is actually healing is credit, not volume
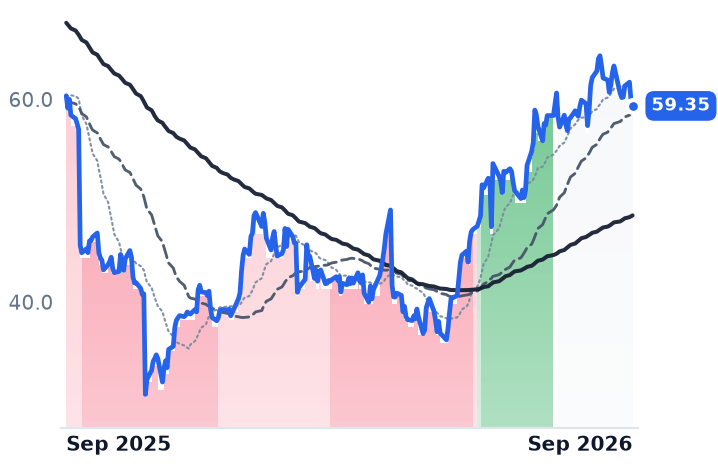
CarMax, the largest used-car retailer and the one that also lends, cut gross profit per retail used unit by $230 to $2,177 in the quarter to 31 May, and comparable used-unit sales still fell 0.8%. It trades at 22.0x forward earnings against 37.0x trailing, on consensus earnings per share of $2.708 for the year to February — about 0.5% growth, and below the $3.21 it earned in fiscal 2025. Meanwhile subprime 60-day-plus auto delinquencies, a record 6.90% in January, improved to 5.67% by June.
That is the honest split. The consumer-credit side of used vehicles is repairing off a record-bad peak; the transaction count is not. Strip out ACV's takeover pop and the group has been falling — CarMax down 1.0% over thirty days, OPENLANE down 1.8%, Carvana down 12.2%. ACV's quote, pinned within three cents of the deal price every session since, now carries no information about wholesale volumes at all.
The tender is expected to close by year-end. The next hard count of used-vehicle units, rather than of dollars per unit, arrives when CarMax reports before the open on 29 September.