

Analog Devices Paid $1.5bn for the AI Power Socket Monolithic Power Already Holds
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Monolithic Power Systems is paid per accelerator on one power rail, and on 14 September a research note questioning its allocation on Nvidia's next platform knocked 7.39% off the shares — the first time that concentration risk showed up in the price rather than only in the risk disclosures.
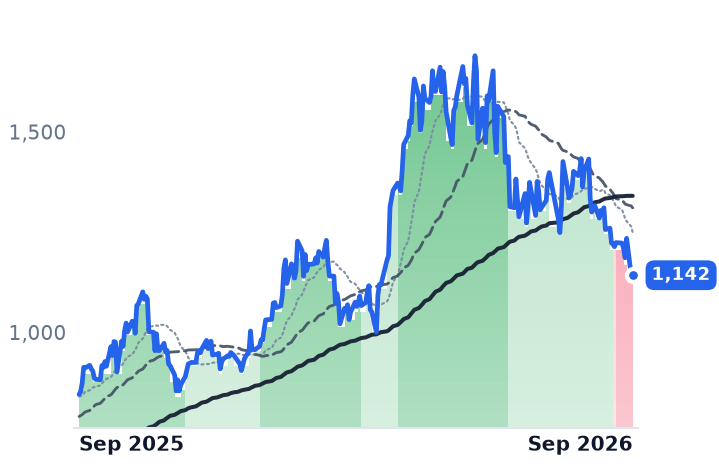
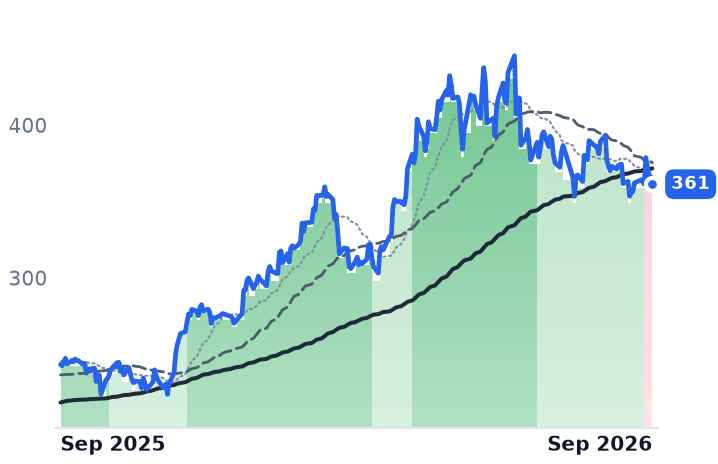
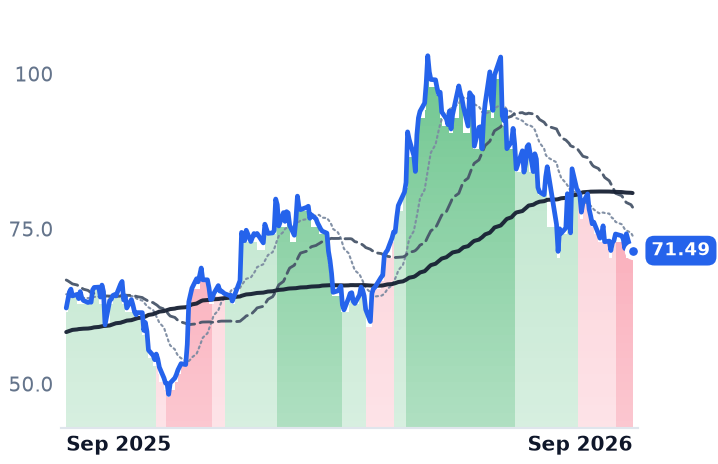
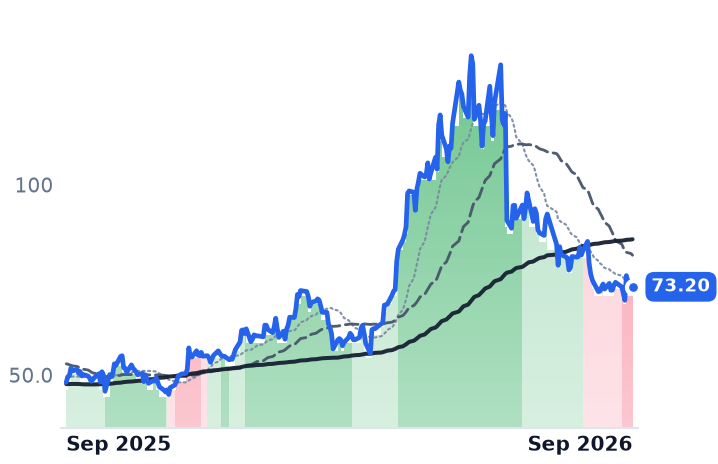
Both businesses are accelerating. Monolithic's enterprise-data revenue grew 164.3% year on year last quarter; Analog Devices grew total revenue 39.6% to its first $4bn quarter, with data-center optical and data-center power each more than doubling. The split is in what investors pay for it: Monolithic at 24.5x forward gross profit, the most expensive of the group, against Analog Devices at 17.7x, the cheapest — and Analog Devices is the one that just spent $1.5bn on Empower Semiconductor to attack the same socket. The market is marking down AI power content, and marking down the incumbent hardest.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | −20.2% | +35.2% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | −8.1% | +48.5% |
| Compared against · context, not the story | |||||
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | −7.3% | +50.9% |
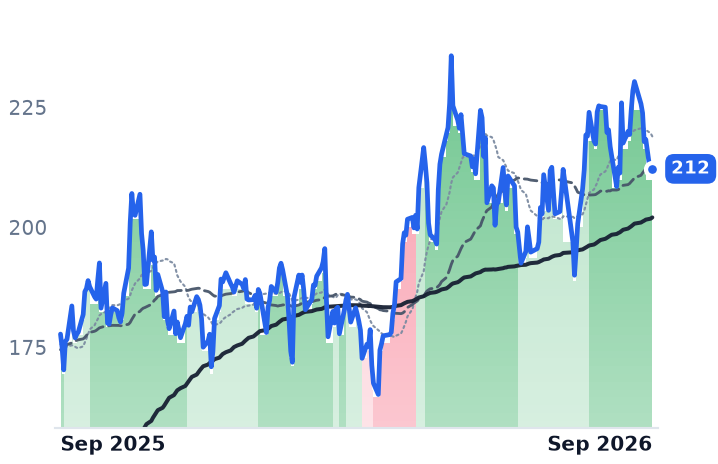
VICR | Vicor | Other | ⚠️ Emerging Bear | −27.4% | +254.5% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | ⚠️ Emerging Bear | −11.3% | +14.9% |
ON | ON Semiconductor | Analog & Mixed-Signal | ⚠️ Emerging Bear | −14.0% | +52.2% |
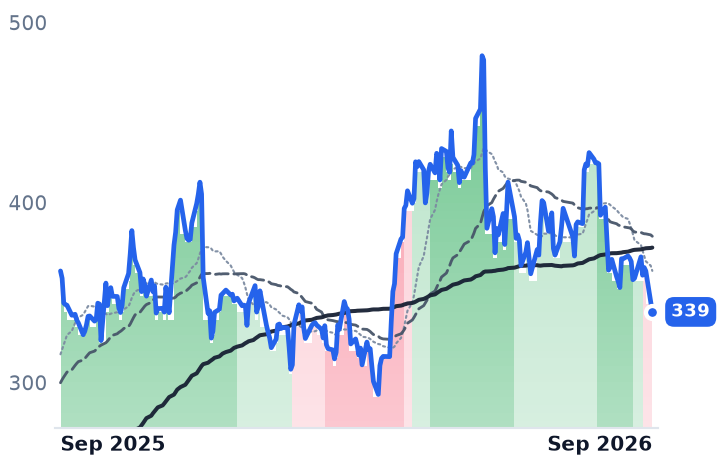
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | −5.7% | +19.4% |
AVGO | Broadcom | Semiconductor Subsystems | 🟢 Cont. Bull | −14.6% | −6.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $56.1B | 69.7x | 41.7x | 17.1x | 13.5x | 31.1x | 24.5x | 54.5x | 1.0% |
ADI | $176.0B | 42.7x | 28.1x | 12.7x | 11.7x | 19.3x | 17.7x | 28.0x | 2.8% |
TXN | $240.6B | 39.9x | 31.0x | 12.4x | 11.0x | 21.2x | 18.8x | 27.6x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VICR | $8.8B | 60.6x | 56.3x | 18.5x | 14.5x | 32.6x | 25.7x | 65.2x | 0.6% |
MCHP | $40.3B | 102.8x | 20.4x | 7.9x | 6.3x | 13.1x | 10.5x | 27.0x | 2.8% |
ON | $32.5B | 52.8x | 26.1x | 5.2x | 5.0x | 14.0x | 13.2x | 26.4x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
AVGO | $1.6T | 42.1x | 29.1x | 18.1x | 15.2x | 26.8x | 22.5x | 31.6x | 2.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MPWR | Revenue | +49.2% | +28.7% | +20.2% |
| EPS | +54.8% | +31.0% | +20.2% | |
ADI | Revenue | +37.8% | +22.1% | +11.6% |
| EPS | +65.8% | +29.4% | +18.0% | |
TXN | Revenue | +24.0% | +13.8% | +10.6% |
| EPS | +55.6% | +20.7% | +17.2% | |
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% | |
MCHP | Revenue | +6.2% | +37.1% | +16.4% |
| EPS | +20.7% | +132.2% | +25.6% | |
ON | Revenue | +9.2% | +12.9% | +13.5% |
| EPS | +37.1% | +41.7% | +31.7% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
AVGO | Revenue | +67.2% | +64.2% | +60.7% |
| EPS | +72.9% | +65.1% | +57.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Edgewater Research told clients on 14 September that Monolithic Power Systems' supplier allocation on Nvidia's next-generation accelerator platform was at risk, and the shares fell 7.39%. The session was ugly for chips generally — Nvidia fell 3.36% and a broad semiconductor exchange-traded fund 4.75% after Anthropic's Dario Amodei published an essay urging AI developers to slow down, with Elon Musk and Sam Altman echoing him — but Monolithic fell roughly half again as far as the index, and the excess belongs to the note.
The note hit the one thing Monolithic's income statement cannot show. The company sells power-management semiconductors — the controllers and modules that step rack voltage down to the sub-1-volt rails an accelerator's processor runs on — and it wins those designs years ahead, then gets paid per unit on a platform the customer can re-architect or second-source at the next generation. Content per accelerator is a decision made annually, at somebody else's desk. And since 7 July, a company eight times Monolithic's market value has been inside the same socket: Analog Devices closed a $1.5bn all-cash purchase of Empower Semiconductor, whose integrated voltage regulators put conversion in the processor package.
The incumbent is growing faster than ever
Monolithic's June quarter was the best in its history. Revenue rose 47.6% year on year to $980.6m, operating income rose 84.4%, and the operating margin went from 24.8% a year earlier to 31.0%. The enterprise-data end market — the accelerator business — produced $380.6m, up 164.3% year on year and 38.8% of the company. Management raised its full-year floor for enterprise-data growth from 85% to 130%. Founder-chief executive Michael Hsing told investors the company had become "the highest power density company in the world", with solutions for "not only top-of-rack switches but TPUs, NIC cards, and other things in the rack."
One line did not move: gross margin has sat between 55.1% and 55.4% in all eight reported quarters. The AI mix has brought volume, and it has not brought price.
The challenger is buying the socket
Analog Devices sells tens of thousands of catalog parts into industrial, automotive and communications customers, which is why it was supposed to be the analog-cycle name here. It isn't. In the quarter reported on 19 August, revenue rose 39.6% to $4.02bn, gross margin reached 67.3% from 63.1% a year earlier, and operating income nearly doubled. Communications grew 84%, with data center now about 80% of that segment, and data-center optical and data-center power each more than doubled as the industry moves to 800-volt distribution. Chief executive Vincent Roche called energy "the most persistent constraint to scaling next-generation systems". Management called intermediate-to-core conversion for 6,000-amp processors one of the fastest and largest growing analog opportunities, and said book-to-bill was "not unusually elevated" with customers running lean — so the channel restocking that usually explains an analog upswing is not the explanation here. The fourth quarter is guided to roughly $4.3bn.
Analog Devices was already among the main suppliers of voltage regulator modules — Monolithic's territory — before it bought Empower.
What fell, and what didn't
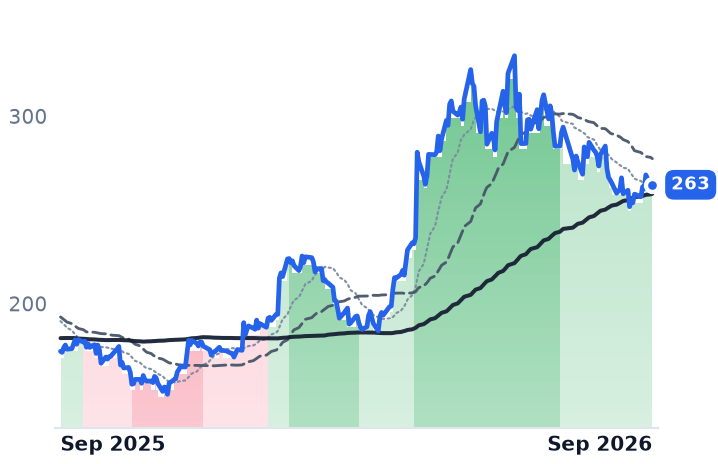
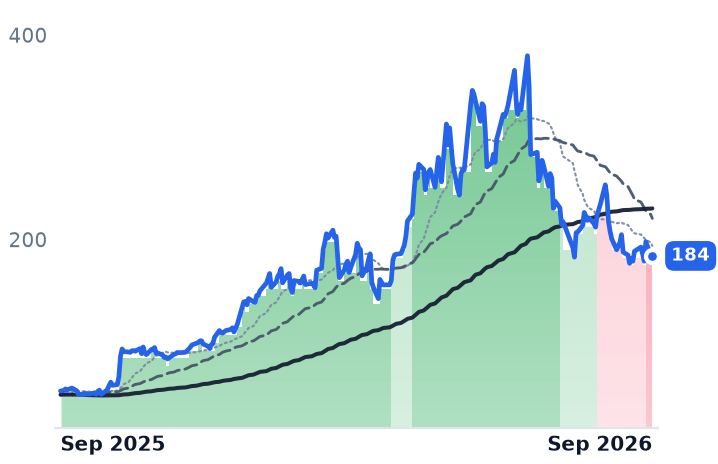
Over thirty days the drawdowns scale with AI-power content rather than with analog exposure: Vicor down 21.6%, Monolithic 18.5%, Analog Devices 7.2%, Texas Instruments 5.8%. Texas Instruments is the honest cycle control, and it is the one name of the group still in an uptrend, with revenue growth accelerating to 22.8% and operating margin at 42.3%. Monolithic's trend rolled over hardest and earliest, turning down in the first week of September; it closed Monday 32.4% below its 52-week high.
On forward gross profit, Monolithic is the most expensive of the four at 24.5x, against Texas Instruments at 18.8x, Vicor at 25.7x on consensus that has its revenue growing 55.6% next year, and Analog Devices the cheapest at 17.7x. Monolithic's trailing multiple of gross profit is 31.1x, down from 48.7x in May and 35.4x in mid-August. This is a de-rating that started four months before the Edgewater note.
The verdict
Monolithic earns the growth; what nothing in the reported numbers earns is the premium. A flat gross margin plus revenue concentrated in one accelerator program is a volume business dressed as a franchise, and the compression from 48.7x to 31.1x is the market pricing a risk the income statement will only ever show after the fact. Monolithic's management has said it has no concentrated customers, and Nvidia's published partner list for high-voltage racks names ten suppliers rather than one — the allocation risk is a claim about next generation, not a disclosed fact about this one.
Analog Devices is the harder one to square. Its business accelerated for four straight quarters, its margins expanded, it guided up, it is the cheapest of the group on gross profit, and it spent $1.5bn to move up the same power tree — and the shares turned down on 10 September anyway. If the market is marking down AI power content, it has marked down the company attacking the socket less than the one holding it, which is at least internally consistent, and it has marked both down while their customer's shares rose.
Vicor held the accelerator power socket inside Nvidia's H100 before Monolithic took it away, and now monetizes the patents behind that architecture, collecting $30.4m of royalties in the June quarter. It is the standing proof that this socket changes hands — and a fair picture of what a company is left with afterward.