

Chewy Borrowed $600m to Take Its Vet Clinics From 18 to 47; Petco Already Owns 300
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two pet retailers reported within a week of each other, and both said the same uncomfortable thing: the pet category is flat and neither is forecasting a consumer recovery. So both are building veterinary capacity instead, because vet service prices are rising 7.8% a year while pet food inflation runs 1.4%.
Chewy's quarter was the stronger one — sales up 7.3% to $3.33bn, operating income up 41%, subscriptions at 84.6% of net sales, full-year margin guidance raised — and the shares fell 9.1% on the day, because gross margin was flat at 30.4% and every dollar of improvement came from expenses below it. Petco's sales were flat for a second quarter, its profit gain bought with expense discipline and $170m of debt paydown. The turn here is mix, not demand, and only one of the two has a balance sheet that can wait.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CHWY | Chewy | Pet & General Specialty | 🔴 Cont. Bear | −8.4% | −44.7% |
WOOF | Petco Health and Wellness | Pet & General Specialty | 🔴 Cont. Bear | −10.4% | −29.4% |
| Compared against · context, not the story | |||||
FRPT | Freshpet | Pet Food & Nutrition | 🔴 Cont. Bear | −12.0% | +21.5% |
TSCO | Tractor Supply | Sporting Goods & Outdoor | 🔴 Cont. Bear | −5.7% | −44.1% |
AMZN | Amazon.com | Online Marketplaces | 🟢 Cont. Bull | −1.7% | +11.0% |
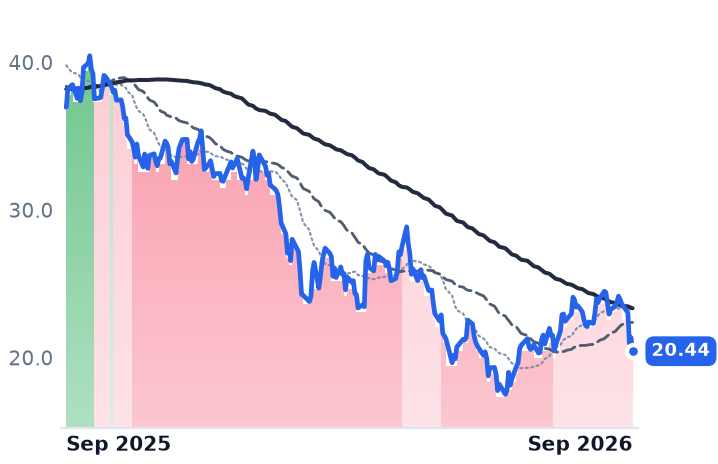
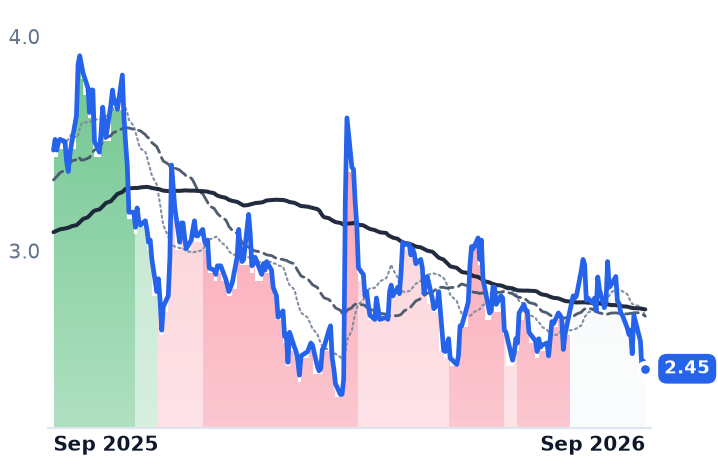
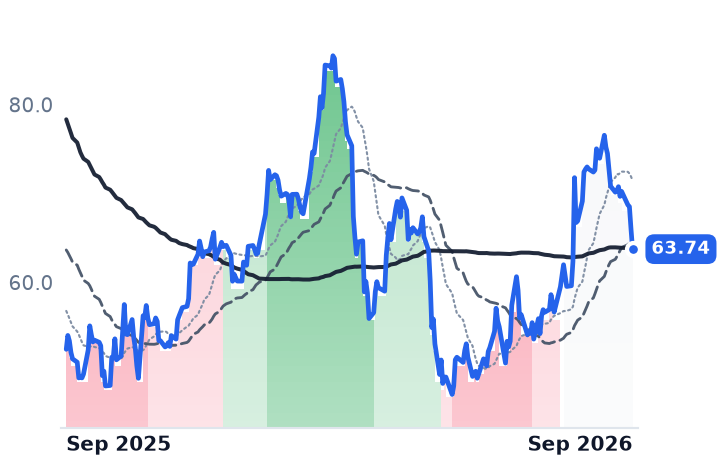
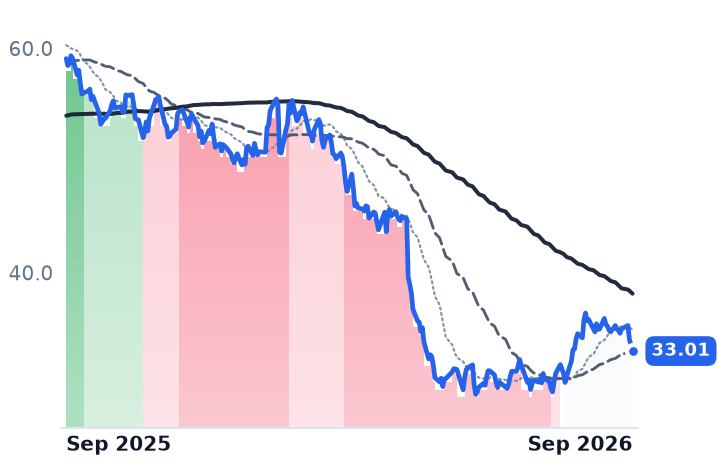
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CHWY | $8.5B | 39.3x | 26.2x | 0.7x | 0.6x | 2.2x | 2.1x | 22.6x | 6.7% |
WOOF | $699.6M | 22.1x | 9.9x | 0.1x | 0.1x | 0.3x | 0.3x | 5.6x | 44.1% |
FRPT | $3.2B | 15.7x | 33.7x | 2.7x | 2.6x | 6.9x | 6.7x | 13.3x | 5.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TSCO | $16.0B | 14.9x | 14.3x | 1.0x | 1.0x | 3.2x | 3.0x | 11.4x | 3.6% |
AMZN | $2.9T | 21.2x | 21.1x | 3.7x | 3.5x | 7.3x | 6.8x | 11.9x | -0.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CHWY | Revenue | +6.7% | +7.3% | +6.8% |
| EPS | −32.6% | +48.5% | +37.4% | |
WOOF | Revenue | −2.7% | +0.6% | +1.1% |
| EPS | −275.3% | +68.5% | +3.2% | |
FRPT | Revenue | +11.1% | +8.5% | +8.0% |
| EPS | −20.4% | −3.9% | +11.3% | |
TSCO | Revenue | +3.8% | +5.5% | +6.9% |
| EPS | +1.8% | +8.3% | +11.2% | |
AMZN | Revenue | +15.9% | +14.6% | +16.0% |
| EPS | +76.8% | −16.1% | +30.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Chewy paid $400m for Modern Animal, a chain of veterinary clinics, and funded it with an inaugural $600m term loan — the first material debt in the capital structure of a company that has never needed any. The deal takes Chewy Vet Care from 18 locations to 47, with 60 expected by the end of fiscal 2026 and embedded revenue approaching $290m at steady state, according to the company's disclosure. An online retailer of about 100,000 products from 3,000 brands is becoming a landlord of medical practices.
The reason sits in the price data. Veterinary services prices rose 7.8% year over year against pet supplies at 1.5%, while pet food inflation ran just 1.4% in February 2026 — well under the food-at-home rate. And US dog households shrank 4.2% between 2019 and 2025. Selling more bags of kibble to more dogs is not the available growth.
What Chewy's quarter actually showed
On September 9 Chewy reported second-quarter net sales of $3.33bn, up 7.3% — an acceleration from 4.8% the prior quarter — with operating income of $98.4m, up 41%. Autoship subscription sales grew 9.3% to a record 84.6% of net sales, active customers reached 21.7m and net sales per active customer hit $602, each up 3.8%. Full-year adjusted EBITDA margin guidance was raised to 6.7–6.8%.
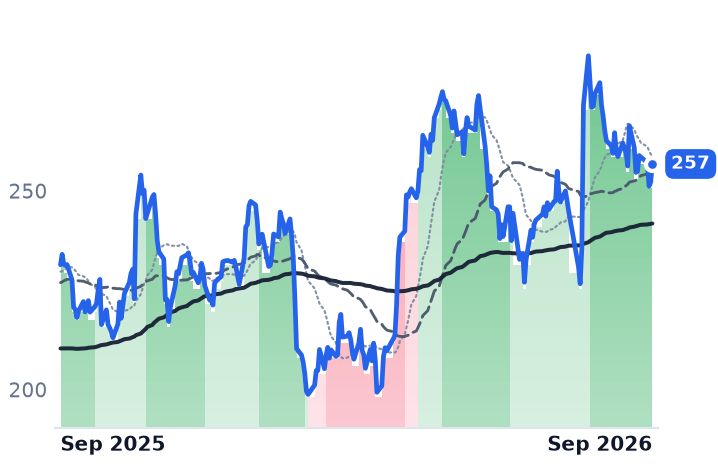
The shares fell 9.1% that session and have since traded at $20.44, down 43.3% over twelve months, with the 50-day average below the 200-day since late July. Two things explain the reaction. Gross margin was flat year over year at 30.4%; the entire margin gain came from selling and administrative costs falling 70 basis points to 18.4% of sales. And chief executive Sumit Singh told investors plainly: "We are not assuming a meaningful consumer recovery for the balance of this fiscal year." Roughly $15m of the quarter's EBITDA beat was timing — tariff refunds, rebates, gift-card breakage.
Chewy price-matches Amazon on the merchandise itself — the two carried identical prices 93% of the time — so the incremental gross-profit dollar has to come from sockets a marketplace cannot occupy: a sponsored-ads network sold to the brands it resells, running at roughly 2% of net sales against a 1–3% entitlement with about two-thirds flowing to the bottom line, a pharmacy, and the clinics. Modern Animal's mature locations earn EBITDA margins above 20%.
Petco is doing it from the other end
Petco, which runs roughly 1,500 leased pet stores plus grooming, training and 300 in-store veterinary hospitals, reported on September 2: net sales of $1.489bn, up 0.05%, comparable sales up 0.6% for a second consecutive positive quarter, adjusted EBITDA of $122m including a $6.8m tariff refund. Selling and administrative costs rose $1m. That is expense discipline against fixed occupancy, and it is working: $170m of debt retired over nine months against $1.48bn outstanding, a 2.0x leverage target, seven consecutive quarters of hitting cash-flow goals, in CFO Sabrina Simmons' account on the call. Its veterinarians are employees, not franchised partners, and hospital expansion begins in 2027. Chief executive Joel Anderson was blunt about the fleet: "We have not been the best custodians of the physical part of our brand."
Petco is also importing Chewy's mechanism, rolling Autoship into stores; it already accounts for about half of Petco's digital sales.
The verdict
Neither company is being paid for demand, because there isn't any to speak of — the US pet market grew 3.7% to $158bn in 2025. What Chewy earns is the mix shift: a subscription base compounding faster than the company, an ad network at a media margin, and now clinics bought with borrowed money. What nothing yet explains is a 43% twelve-month decline against 26.2x forward earnings versus 39.3x trailing, a 6.7% free-cash-flow yield and consensus fiscal-2027 earnings growth of 48.5% — though 26x forward on a 7%-growth retailer is not cheap in absolute terms. Petco at 5.6x trailing enterprise value to EBITDA and 0.58x book is a $700m equity stub beneath $1.48bn of gross debt, and the operating-lease liability on 1,500 stores is not disclosed in its results, so true leverage is worse than the 3.4x the guidance implies.
The market values a dollar of Chewy's gross profit at seven times what it pays for Petco's. Both are now buying the same veterinary dollar — one with a term loan it never needed before, the other with cash it is currently using to pay down debt.