

Snowflake Is Paying About $1bn for Observe and Entering Datadog's Market
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two software businesses that bill by metered volume each reported four straight quarters of accelerating growth, and the market moved them in opposite directions. Snowflake's product revenue grew 37% and it raised its full-year product forecast to $6.07bn; Datadog's revenue grew 35.6% on a record $115m sequential addition, then it disclosed that one large artificial-intelligence customer renewed and cut usage, pulling third-quarter guidance to 28-29%.
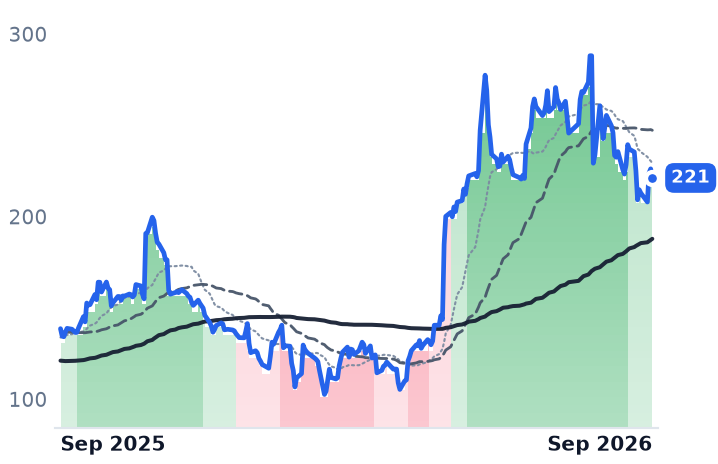
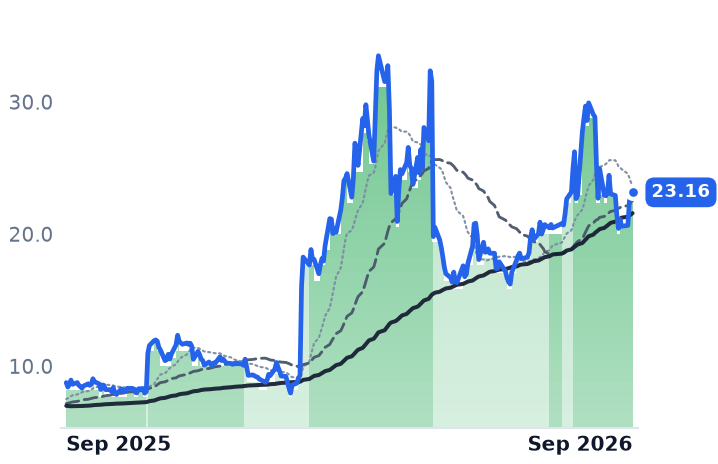
Since late July Snowflake's price against trailing gross profit has risen from 27.7x to 31.3x while Datadog's has fallen from 30.4x to 25.0x. Snowflake's premium is being paid for volume management says arrives at a worse margin — full-year product gross margin guidance was cut to 74%. And with Observe, Snowflake is now bidding for the telemetry bill Datadog meters.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
DDOG | Datadog | Data & Analytics Platforms | 🌱 Emerging Bull | −11.5% | +59.5% |
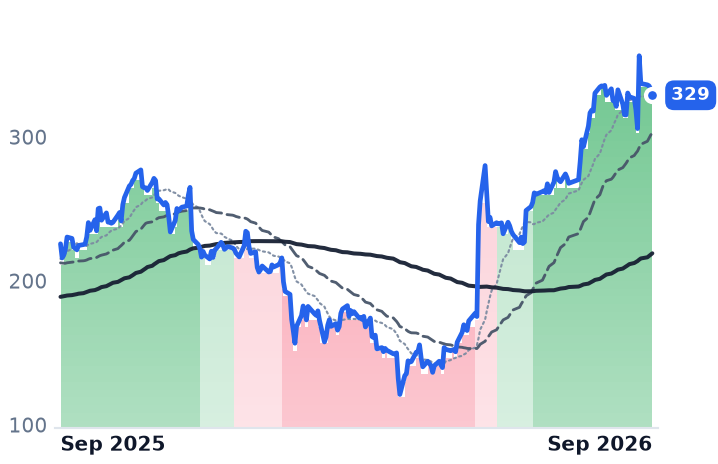
SNOW | Snowflake | Data & Analytics Platforms | 🌱 Emerging Bull | −1.4% | +45.7% |
| Compared against · context, not the story | |||||
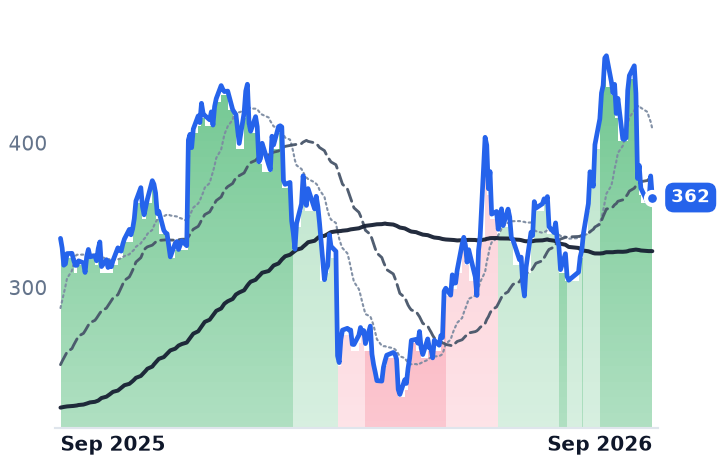
MDB | MongoDB | Data Management & Analytics | 🟢 Cont. Bull | −18.1% | +8.5% |
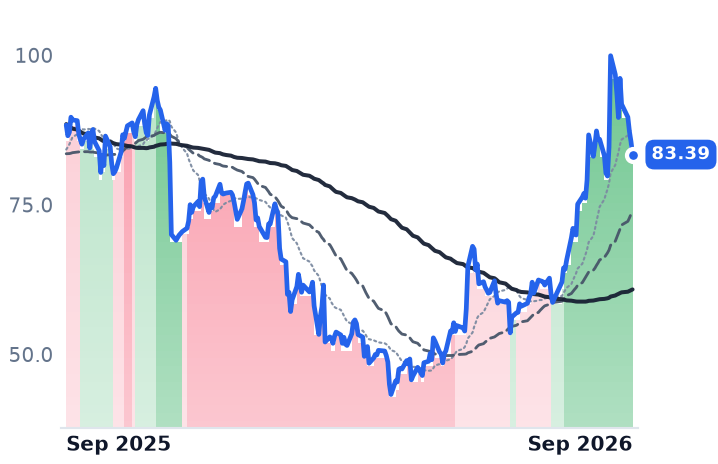
ESTC | Elastic | Data & Analytics Platforms | 🌱 Emerging Bull | +0.3% | −5.6% |
FSLY | Fastly | Cloud Infrastructure & Platform | 🟢 Cont. Bull | −20.2% | +164.4% |
PLTR | Palantir Technologies | AI & Data Intelligence | 🟢 Cont. Bull | −3.8% | −2.3% |
AMPL | Amplitude | Other | 🌱 Emerging Bull | −0.3% | +15.8% |
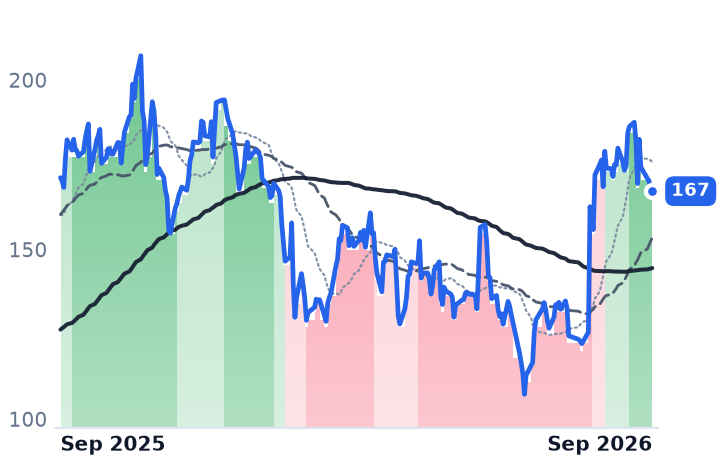
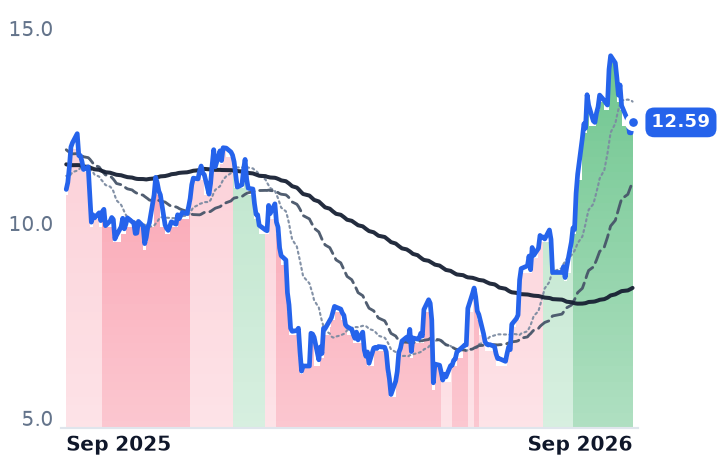
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DDOG | $78.7B | 444.9x | 87.4x | 19.9x | 17.6x | 25.0x | 22.1x | 302.3x | 1.5% |
SNOW | $114.0B | n/m | 148.5x | 21.0x | 18.0x | 31.3x | 26.9x | n/m | 1.0% |
MDB | $36.5B | n/m | 74.0x | 14.0x | 12.3x | 19.5x | 17.1x | — | 1.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ESTC | $10.1B | 27.0x | 29.1x | 5.6x | 5.1x | 7.5x | 6.7x | 155.2x | 3.4% |
FSLY | $3.6B | n/m | 43.9x | 5.2x | 4.9x | 8.5x | 7.9x | n/m | 1.2% |
PLTR | $394.9B | 136.5x | 108.2x | 64.2x | 48.6x | 75.7x | 57.3x | 126.8x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMPL | $1.8B | n/m | 187.3x | 4.7x | 4.3x | 6.5x | 5.9x | n/m | 1.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DDOG | Revenue | +31.8% | +22.4% | +22.8% |
| EPS | +25.4% | +17.0% | +22.1% | |
SNOW | Revenue | +29.4% | +35.7% | +28.9% |
| EPS | +72.3% | +82.7% | +36.2% | |
MDB | Revenue | +23.1% | +21.5% | +18.0% |
| EPS | +59.1% | +27.3% | +19.7% | |
ESTC | Revenue | +17.6% | +15.6% | +14.6% |
| EPS | +30.3% | +32.3% | +17.4% | |
FSLY | Revenue | +20.9% | +12.0% | +11.2% |
| EPS | +897.9% | +11.2% | +17.0% | |
PLTR | Revenue | +86.1% | +49.3% | +48.2% |
| EPS | +122.1% | +42.4% | +50.3% | |
AMPL | Revenue | +19.9% | +16.3% | +19.1% |
| EPS | +1.6% | +133.8% | +61.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Snowflake used its September 2 earnings call to confirm it has agreed to acquire Observe, a company that builds monitoring software on the open Apache Iceberg standard rather than a proprietary data store. The price is reported at about $1bn, with roughly one percentage point of Snowflake's raised full-year product revenue forecast attributed to it.
That puts Snowflake — which sells credits consumed per second of virtual-warehouse compute, on a cloud data platform used for analytics and data sharing — into the market where Datadog meters a bill per monitored host, per gigabyte of logs ingested and per application trace. Both companies bill for volume. Both just reported four straight quarters of accelerating volume. Over six weeks the market has priced them apart: Datadog's share price against its trailing gross profit fell from 30.4x in late July to 25.0x, while Snowflake's rose from 27.7x to 31.3x.
What Snowflake bought the re-rating with
Product revenue reached $1.49bn in the July quarter, up 37% and accelerating for a third consecutive quarter. Net revenue retention was 126%, and remaining performance obligations reached $9.0bn, up 30%, with about 54% expected to convert inside twelve months. Management raised full-year product revenue guidance to $6.07bn from $5.84bn in May, and the shares rose more than 22% after hours. "AI is bringing new workloads onto the platform," chief executive Sridhar Ramaswamy told investors on September 2, describing first-party products Cortex Code and CoWork as a second leg and "AI activation" lifting overall platform consumption as a third.
The volume arrives at a cost. Snowflake cut full-year non-GAAP product gross margin guidance to 74% because the fast-growing AI workloads carry lower contribution margins today — the first reversal of a gross margin trend that had improved every year since fiscal 2022. The company remains unprofitable on a reported basis, with a $191.7m quarterly net loss, narrowed from $298.0m a year earlier.
What Datadog lost the re-rating with
On August 6 Datadog reported $1.12bn of revenue, up 35.6%, the fourth straight quarter of acceleration from 28.4% and a record $115m sequential addition. Then it disclosed that a significant AI customer using 17 of its products had renewed with a usage reduction starting in the third quarter. Guidance for that quarter implies 28-29% growth, and the shares fell about 19% in the session, with analysts widely assuming the account is OpenAI.
"If you back out our largest customer from our growth, you get pretty much the same growth rate as the rest of the business has been accelerating very steadily," chief executive Olivier Pomel said on the call. The supporting number is real: revenue from non-AI customers grew in the high 20s, a fifth consecutive quarter of acceleration off that base. But Datadog discloses no figure for what its AI customers or its largest account contribute. The most granular concentration data it gives is that 4,720 customers spending above $100,000 a year generate 91% of annual recurring revenue. The single relationship now setting the share price is not quantified in any public percentage.
The verdict
Datadog trades at 25.0x trailing and 22.1x forward gross profit; Snowflake at 31.3x and 26.9x, on a 67% gross margin against Datadog's 79%, and with reported operating losses. The market is paying more for consumption that management has told it will come at a lower margin than for consumption that has been growing faster and is disclosed as concentrated. MongoDB's 13.6% fall on September 2, after beating every estimate and raising guidance, says the judgment across metered-database software is about forward consumption rather than reported results.
Datadog's discount has a named, prospective cause, which is why it is not a pure mispricing — but nothing in the disclosure explains why the accelerating remainder of the base earns no credit at all. Snowflake's premium rests on guidance and a backlog it has yet to convert, and on a margin line it has already guided down.
Datadog's largest customer renewed and then consumed less. The next thing arriving in that market is a competitor that already holds the customer's data.