

First Solar Booked New US Panels at $0.36 a Watt as Washington Set a $0.38 Import Floor
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
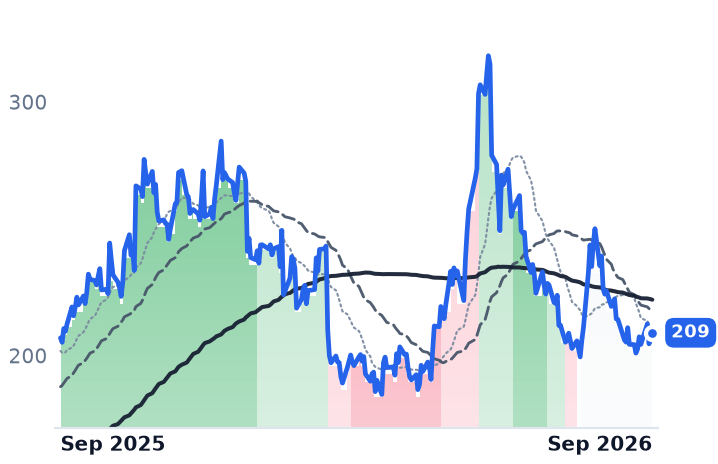
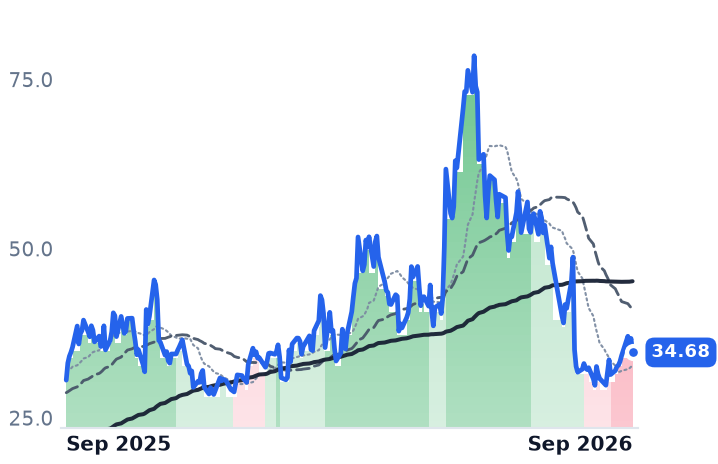
Three federal trade actions in five weeks have built a price wall around the American solar market, and the one large US panel maker exempt from all of it by chemistry has watched its shares fall 22.9% over three months.
First Solar's June-quarter gross margin reached 57.3%, but a Section 45X production credit guided at $330m-$400m and a net tariff benefit of $89m sit inside $605.0m of gross profit; strip both and the manufacturing business earned an 11-18% gross margin. Backlog pricing held near $0.302 a watt and new US bookings were struck above it. Volume is the soft spot, with the book down 2.8 gigawatts in the quarter.
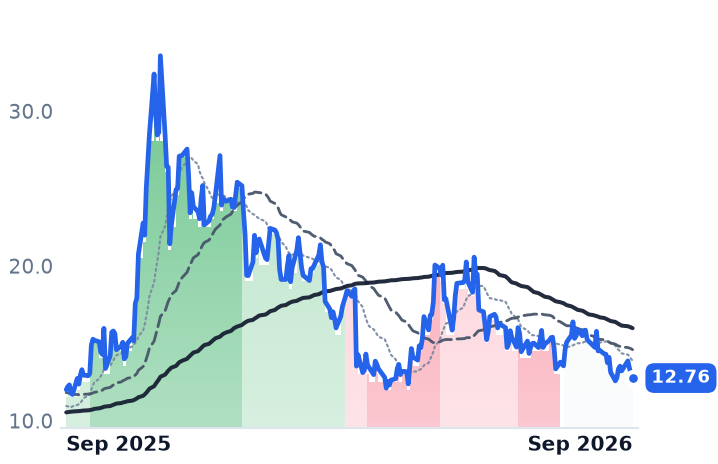
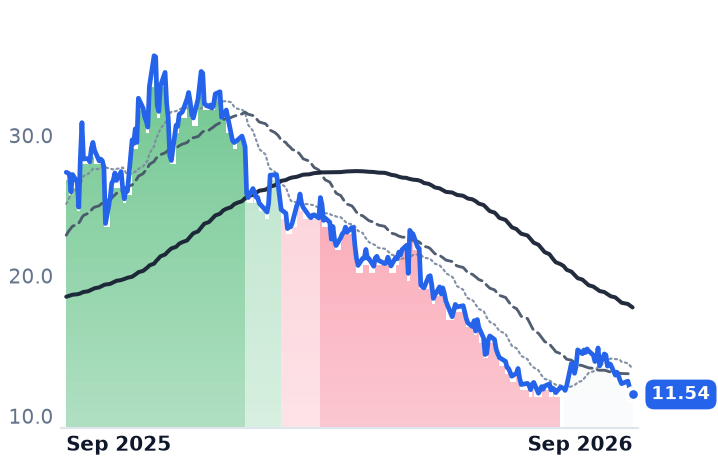
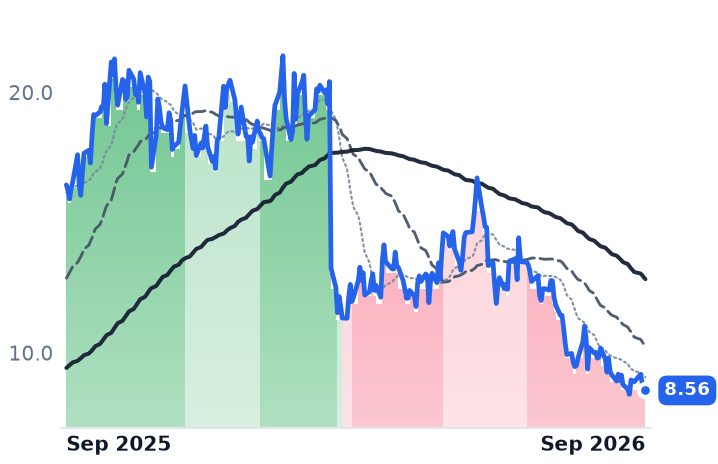
Canadian Solar, on the crystalline-silicon side, saw revenue fall 28.7% and gross margin halve to 13.9%. Daqo, selling polysilicon below cash cost, is shut out of the US by a $21-a-kilogram floor.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
FSLR | First Solar | Solar Module Manufacturers | 🟢 Cont. Bull | −7.3% | +1.0% |
CSIQ | Canadian Solar | Solar Module Manufacturers | ⚠️ Emerging Bear | −15.7% | +6.2% |
DQ | Daqo New Energy | Solar Module Manufacturers | ⚠️ Emerging Bear | −21.2% | −57.9% |
| Compared against · context, not the story | |||||
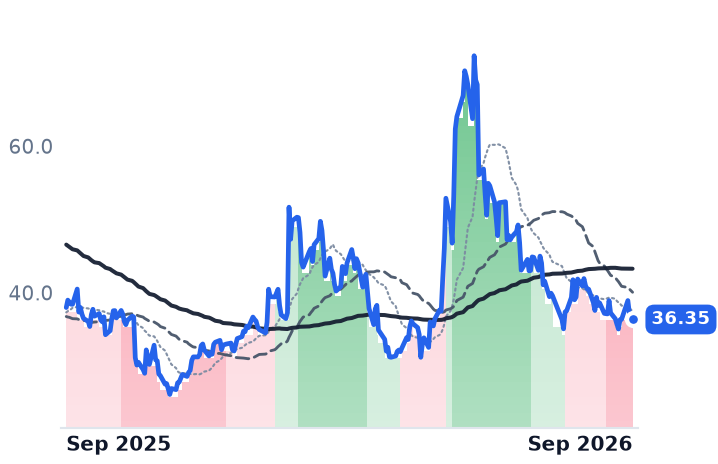
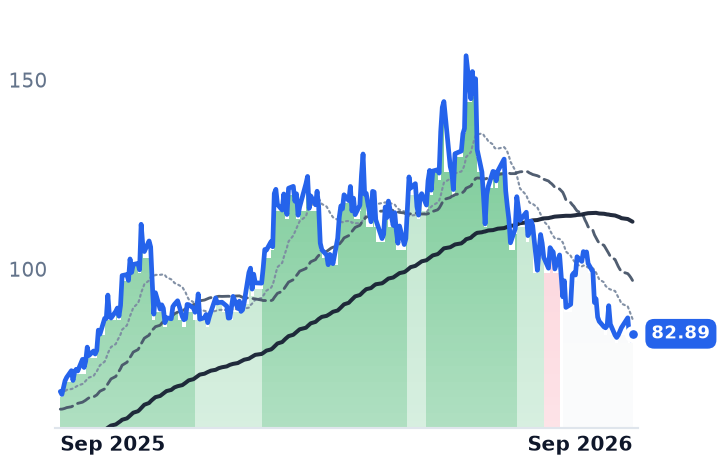
ENPH | Enphase Energy | Inverters & Power Electronics | 🔴 Cont. Bear | −10.2% | −4.3% |
SEDG | SolarEdge Technologies | Inverters & Power Electronics | ⚠️ Emerging Bear | +7.0% | +13.4% |
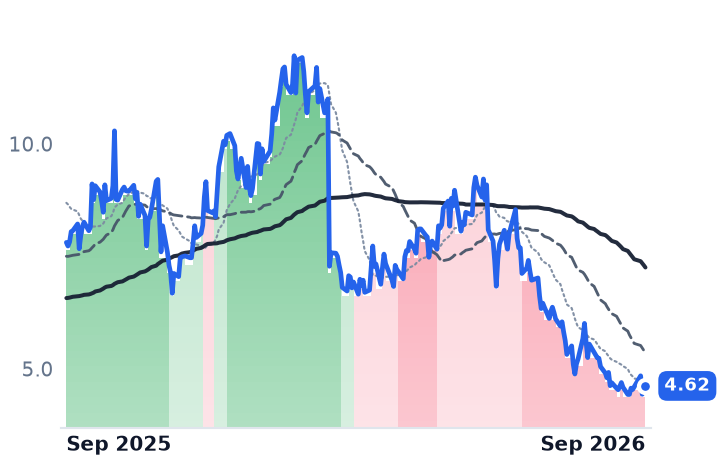
RUN | Sunrun | Residential Solar Installers | ⚠️ Emerging Bear | −16.0% | −48.0% |
NXT | Nextpower | Other | 🟢 Cont. Bull | −18.3% | +22.5% |
ARRY | Array Technologies | Solar Tracking Systems | ⚠️ Emerging Bear | −8.5% | −40.8% |
SHLS | Shoals Technologies | Solar System Components | 🟢 Cont. Bull | −13.6% | +3.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLR | $22.5B | 12.9x | 12.0x | 4.2x | 4.5x | 9.5x | 10.2x | 8.6x | 6.7% |
CSIQ | $866.4M | n/m | — | 0.2x | 0.1x | 1.1x | 0.9x | 79.4x | -182.3% |
DQ | $780.9M | n/m | — | 1.4x | 1.6x | — | — | n/m | -33.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ENPH | $4.9B | 36.1x | 18.4x | 3.7x | 4.1x | 7.8x | 8.7x | 27.9x | 3.1% |
SEDG | $2.2B | n/m | — | 1.7x | 1.7x | 7.6x | 7.6x | n/m | 4.0% |
RUN | $2.1B | 5.2x | 7.0x | 0.6x | 0.7x | 1.8x | 2.0x | 23.4x | -64.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXT | $14.9B | 24.7x | 21.2x | 4.1x | 3.5x | 12.3x | 10.4x | 18.3x | 3.7% |
ARRY | $807.6M | n/m | 7.2x | 0.7x | 0.6x | 2.8x | 2.3x | 301.0x | 12.1% |
SHLS | $1.4B | 45.8x | 21.0x | 2.5x | 2.3x | 7.7x | 7.2x | 23.5x | -3.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FSLR | Revenue | −1.7% | +17.1% | +11.8% |
| EPS | +19.5% | +34.3% | +25.9% | |
CSIQ | Revenue | +2.6% | +21.0% | +0.2% |
| EPS | +49.6% | −142.0% | +234.3% | |
DQ | Revenue | −38.8% | +85.0% | +37.2% |
| EPS | +71.5% | −43.5% | −112.4% | |
ENPH | Revenue | −19.1% | +6.2% | +10.8% |
| EPS | −28.8% | +14.0% | +18.9% | |
SEDG | Revenue | +12.0% | +11.1% | +11.4% |
| EPS | −86.2% | −370.0% | +91.7% | |
RUN | Revenue | +29.7% | +3.5% | +12.9% |
| EPS | −8.2% | −65.9% | −38.3% | |
NXT | Revenue | +22.3% | +22.3% | +18.0% |
| EPS | +13.8% | +6.1% | +21.9% | |
ARRY | Revenue | +14.9% | +9.8% | +5.6% |
| EPS | +9.8% | +23.8% | +13.9% | |
SHLS | Revenue | +32.7% | +9.1% | +11.0% |
| EPS | +5.1% | +27.4% | +16.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The Commerce Department issued final antidumping and countervailing duties on crystalline-silicon solar cells from India, Indonesia and Laos on 11 September, with combined margins running as high as 234% on Indian cells and 178% on Indonesian ones. The International Trade Commission's injury vote is set for 14 October, and duty orders would issue on 2 November if that vote is affirmative.
That was the last piece of a structure begun on 6 August, when a Section 232 proclamation set, effective 4 December, minimum import prices of $0.38 per watt for modules and $0.22 per watt for cells, alongside $21 per kilogram for polysilicon and $100 for ingots and wafers. The module floor sits roughly 27% above the $0.30 median price Anza recorded for US-assembled modules in the June quarter. Every imported crystalline-silicon panel bidding for an American utility contract now has to be repriced upward into a market where one supplier is already sold out at less than that.
The one panel the floors do not touch
First Solar, a Tempe, Arizona manufacturer of cadmium-telluride thin-film modules sold to utility developers and independent power producers, deposits its semiconductor directly onto glass. It skips polysilicon, ingots, wafers and crystalline cells entirely, and none of its product codes are covered by the proclamation. Its contracted backlog stood at 45.1 gigawatts worth $13.6bn at the end of June, deliveries running to 2030 — about $0.302 a watt, with roughly 41 GW of it carrying domestic-content requirements. New business is being written above that average: 1.9 GW of US bookings at about $0.36 a watt including adjusters, plus 1.1 GW in India near $0.20.
Volume is the soft spot. The backlog shrank 2.8 GW in the quarter because shipments outran gross bookings, and 1.8 GW of Malaysian and Vietnamese capacity sits idle at roughly $30m a quarter. "We are really waiting for the outcome of 232," chief financial officer Alexander Bradley told investors on 30 July. "We would expect to evaluate that and have a view shortly thereafter."
What actually pays First Solar
June-quarter revenue fell 3.7% to $1,056.2m while gross profit rose 21% to $605.0m, taking gross margin to 57.3% from 45.6% a year earlier. Two policy items did that work. The company's quarterly filing states it qualifies for a Section 45X advanced-manufacturing credit of about 17 cents for every watt produced in the United States and sold, and it guided those credits to $330m-$400m for the period; the quarter also carried an estimated net tariff-related benefit of $89m. Strip both and the manufacturing business earned roughly $116m-$186m, an 11-18% gross margin. This is cash, not a deferred asset — in October 2025 the company sold $699.7m of credits for $668.2m. Keeping them requires clearing Treasury's foreign-entity rules, which set a 50% material-assistance threshold for components sold in 2026, rising to 85% by 2030. Operating income rose 24.6%, and net income reached $422.6m.
The mirror and the input
Canadian Solar, the Guelph, Ontario group whose CSI Solar arm makes cells, modules and batteries while Recurrent Energy builds projects, shows what the same market does to a crystalline-silicon producer. June-quarter revenue fell 28.7% to $1,207.7m, gross margin halved to 13.9%, and the manufacturing segment ran a $49m operating loss inside a $76.9m net loss. Its module book of more than 13 GW is worth over $4.5bn, near $0.35 a watt. "This backlog and the respective revenue value does not include the 232 adjustment yet," Thomas Koerner told investors on 27 August. "This is going to increase and grow further as we are adjusting contracts." The shares trade at a quarter of book value, and consensus expects no operating profit before 2028.
Daqo New Energy makes no modules at all — it produces Chinese polysilicon, the input. It sold at $4.04 a kilogram last quarter against $4.57 of cash cost, roughly a fifth of the new $21 US floor, which closes the American market to it outright. It holds $1.9bn of cash and deposits and no debt against a $781m market value, while burning $276m of operating cash in the first half.
Rates did the damage
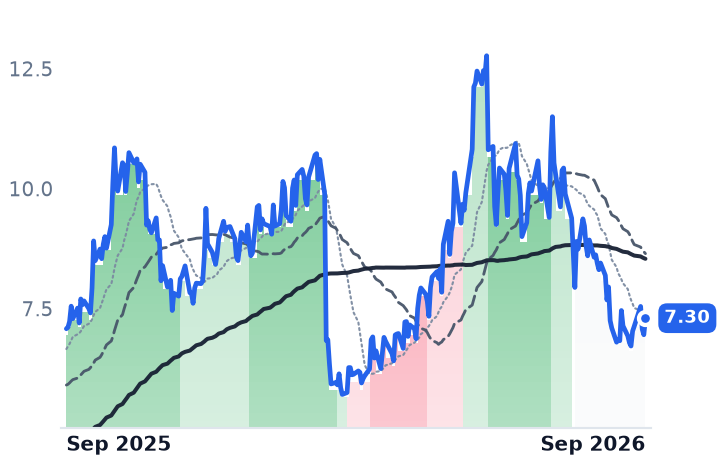
First Solar's three-month decline is not a module story. The 30-day fall is measured off a spike — the shares rose 18.5% in five sessions to 7 August around the proclamation, then gave all of it back. Over the same 30 days Nextracker fell 20.1% and Sunrun 12.7%, with the inverter maker SolarEdge the lone gainer, while the ten-year Treasury reached 4.98% on 11 September, its highest since October 2023. A hawkish reading of Fed Chair Warsh's Jackson Hole speech had already pushed September rate-hike odds from 36% to 67% and cut the Solar Energy Index 9.02% in August. Solar assets are long-dated and capital-heavy; the discount rate moves them.
So the business earned its profit growth from policy rather than from selling more panels at better prices, and the market marked it down for reasons that have nothing to do with either. Consensus has 2026 revenue falling 1.7% to $5.02bn while earnings per share rise 19.5% to $17.44. At about 12 times that figure, against 15.5 times at the 11 June high, the shares are cheaper than they were — but most of the earnings is a federal payment scheduled to phase down.
And the wall cuts both ways. Intertek CEA expects the floors to lift domestic module prices toward $0.35 a watt, cancel utility-scale projects and reduce annual US installations from 2027 onward.
Protection raises what an American panel fetches and lowers how many get built. First Solar's contracted book runs to 2030 — and so does the wind-down of the credit that supplies most of its profit.