

Edwards Won the Medicare Valve-Coverage Change It Requested and Left 2026 Guidance Alone
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A company that asked Washington to widen the market for its biggest product got exactly that, and told investors nothing had changed. Medicare's finalized coverage rule for transcatheter aortic valve replacement removes hospital procedure-volume requirements, allows a single qualified operator, and extends coverage to patients with severe aortic stenosis who have no symptoms yet.
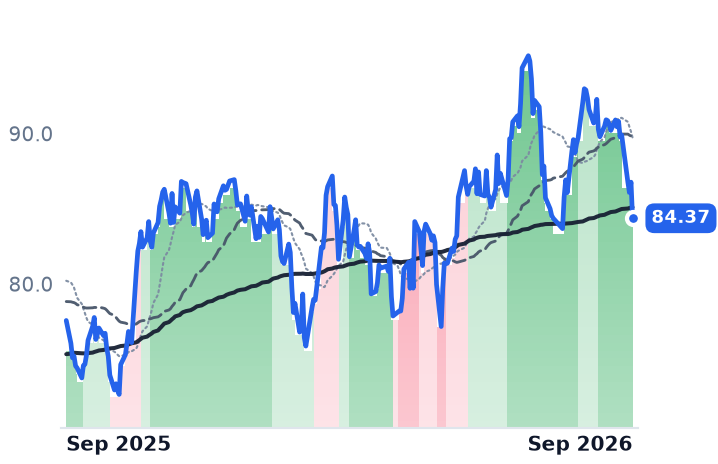
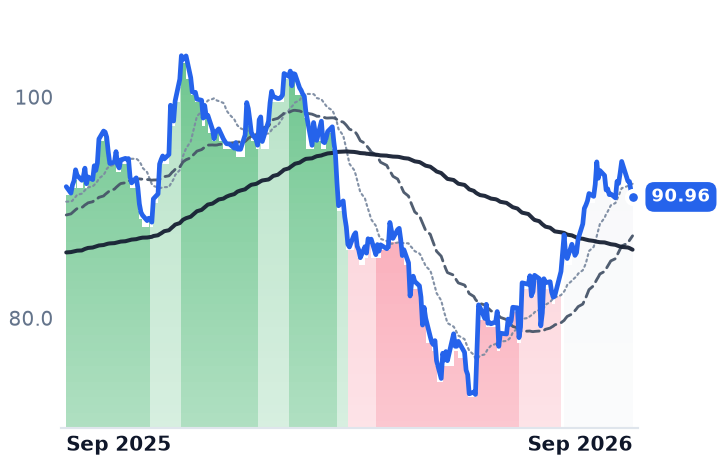
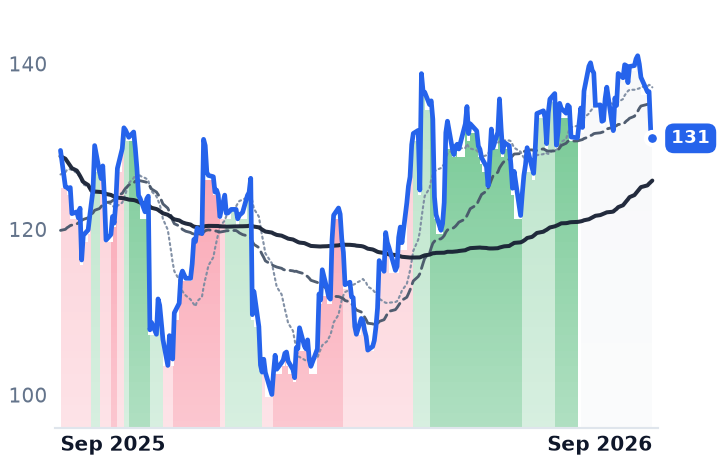
Edwards Lifesciences, which holds more than 60% of the US market for the procedure and books $1.26bn a quarter from it, said the policy "will take time to implement" and kept its 10-11% sales guidance — already raised twice this year from January's 8-10%. The shares have fallen 9.2% in a month anyway, inside a medtech selloff driven by cyberattacks at Stryker and Boston Scientific rather than by anything happening in cardiac catheterization labs.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
EW | Edwards Lifesciences | Cardiovascular & Structural Heart | 🟢 Cont. Bull | −8.7% | +8.8% |
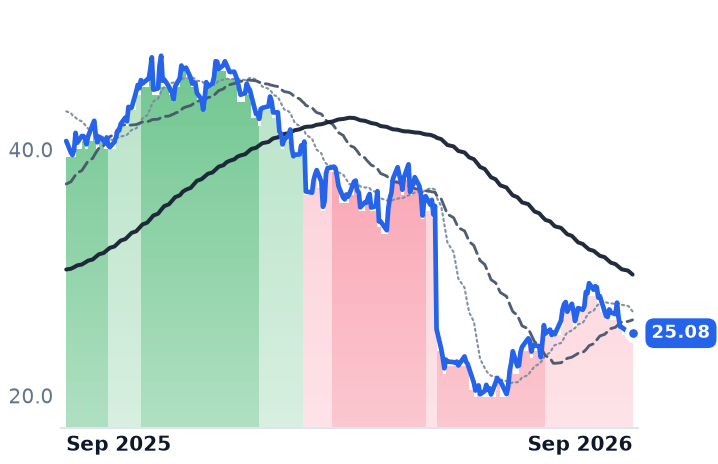
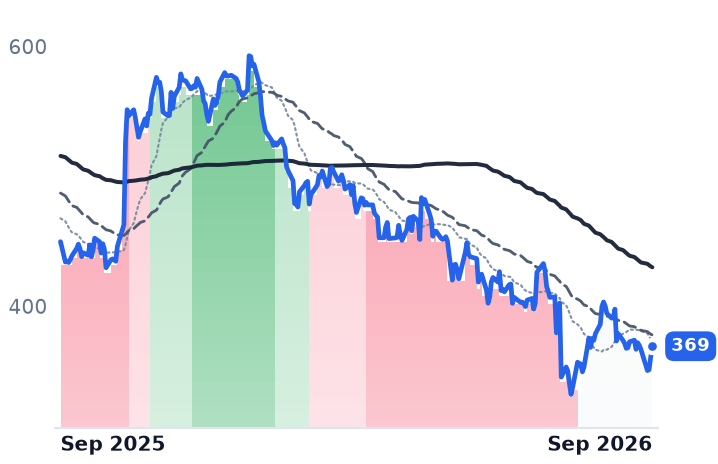
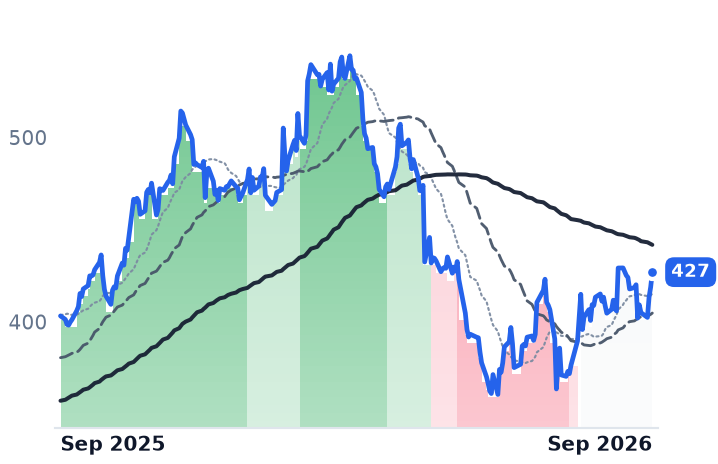
AORT | Artivion | Cardiovascular & Structural Heart | ⚠️ Emerging Bear | −11.4% | −38.4% |
| Compared against · context, not the story | |||||
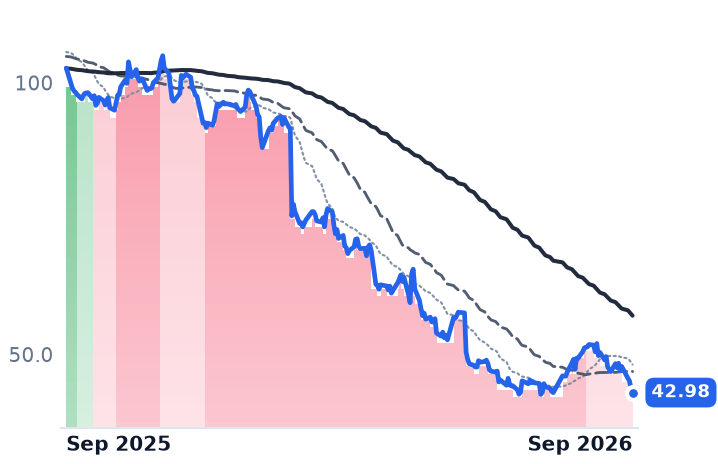
BSX | Boston Scientific | Spinal Surgery & Neuromodulation | 🔴 Cont. Bear | −16.4% | −58.2% |
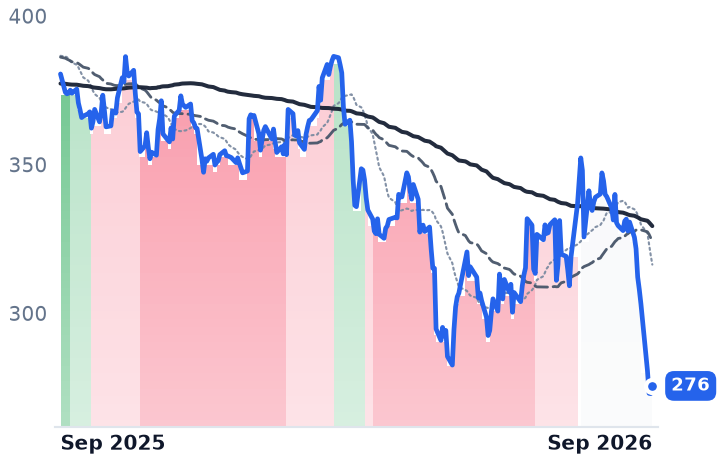
SYK | Stryker | Orthopedic Implants & Trauma | 🔴 Cont. Bear | −19.0% | −27.6% |
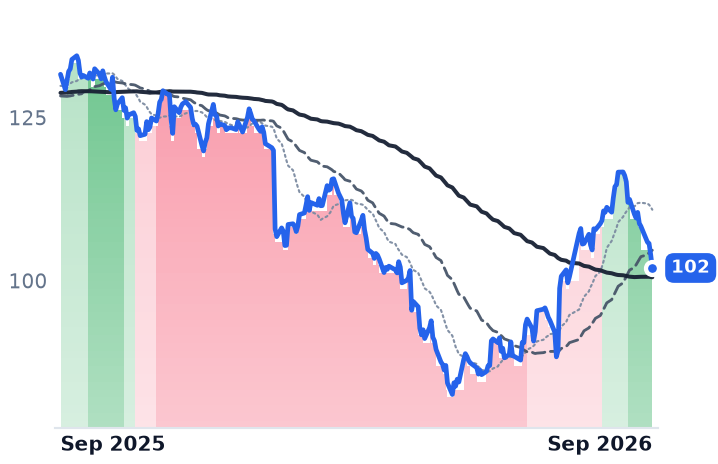
MDT | Medtronic | Spinal Surgery & Neuromodulation | ⚠️ Emerging Bear | +0.4% | −1.0% |
ISRG | Intuitive Surgical | Surgical Robotics & Minimally Invasive Surgery | 🔴 Cont. Bear | −7.8% | −17.9% |
ABT | Abbott Laboratories | Other | 🌱 Emerging Bull | −7.7% | −22.6% |
ZBH | Zimmer Biomet | Orthopedic Implants & Trauma | 🔴 Cont. Bear | −4.6% | −8.6% |
TFX | Teleflex Incorporated | IV & Vascular Access | 🌱 Emerging Bull | −3.5% | +1.1% |
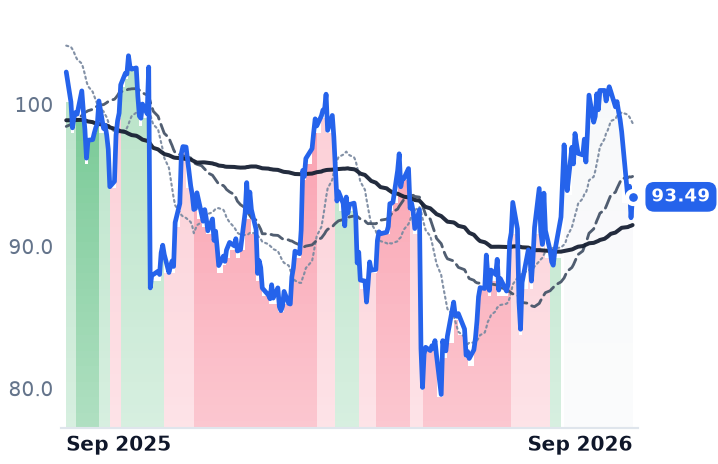
HCA | HCA Healthcare | Hospital Systems | ⚠️ Emerging Bear | +4.5% | +5.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EW | $48.6B | 48.5x | 28.1x | 7.5x | 7.2x | 9.6x | 9.2x | 30.1x | 3.0% |
AORT | $1.2B | n/m | — | 2.6x | 2.5x | 4.1x | 4.0x | 27.0x | -0.9% |
BSX | $63.9B | 17.3x | 13.1x | 3.0x | 3.0x | 4.3x | 4.2x | 13.4x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SYK | $117.6B | 35.2x | 20.5x | 4.7x | 4.3x | 7.3x | 6.8x | 22.3x | 3.9% |
MDT | $116.4B | 22.2x | 15.2x | 3.1x | 3.0x | 4.7x | 4.5x | 15.1x | 5.3% |
ISRG | $149.1B | 50.2x | 40.6x | 14.1x | 12.8x | 21.3x | 19.2x | 39.1x | 1.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ABT | $147.1B | 23.5x | 15.4x | 3.3x | 2.9x | 5.8x | 5.2x | 16.1x | 5.0% |
ZBH | $16.2B | 21.4x | 9.9x | 1.9x | 1.9x | 2.7x | 2.7x | 10.5x | 11.3% |
TFX | $5.8B | n/m | 18.3x | 2.2x | 2.6x | 4.2x | 4.8x | n/m | 6.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HCA | $93.8B | 14.1x | 14.0x | 1.2x | 1.2x | 3.5x | 3.4x | 9.1x | 8.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EW | Revenue | +12.0% | +9.6% | +10.5% |
| EPS | +15.6% | +12.8% | +12.1% | |
AORT | Revenue | +11.0% | +10.8% | +11.9% |
| EPS | −226.2% | −206.9% | +60.2% | |
BSX | Revenue | +6.2% | +4.4% | +7.0% |
| EPS | +8.3% | +3.9% | +10.8% | |
SYK | Revenue | +8.8% | +8.6% | +8.1% |
| EPS | +10.4% | +11.8% | +11.5% | |
MDT | Revenue | +7.9% | +8.0% | +3.5% |
| EPS | +1.1% | +8.3% | +7.1% | |
ISRG | Revenue | +17.5% | +13.5% | +13.7% |
| EPS | +19.6% | +13.4% | +13.0% | |
ABT | Revenue | +12.8% | +9.0% | +7.3% |
| EPS | +6.2% | +10.7% | +11.6% | |
ZBH | Revenue | +4.2% | +3.6% | +3.8% |
| EPS | +3.7% | +6.3% | +7.1% | |
TFX | Revenue | −31.2% | +4.3% | +4.6% |
| EPS | −48.6% | +52.0% | +10.6% | |
HCA | Revenue | +3.7% | +4.8% | +5.4% |
| EPS | +9.2% | +10.0% | +13.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
On September 10 the Centers for Medicare and Medicaid Services finalized a national coverage rule for transcatheter aortic valve replacement — the procedure in which a new heart valve is threaded up through an artery instead of implanted in open surgery. The reconsideration had been formally requested by Edwards Lifesciences in July. The company won it, and then told investors to change nothing.
That is worth pausing on, because the rule loosened the exact constraint the industry has spent a decade complaining about. The final policy removes hospital facility-level procedural-volume requirements, replacing them with expectations on infrastructure and quality improvement, and recognizes that the procedure may be performed by a single qualified operator. It also drops the evidence-development condition for symptomatic severe aortic stenosis and extends Medicare coverage to asymptomatic patients — resting on Edwards' own Early TAVR trial, which the Food and Drug Administration used to approve an expanded SAPIEN 3 label in May 2026. More hospitals may do it, and more patients qualify.
The company's own answer
Edwards called the decision "an important step toward improving and expanding patient access," then added the sentence that explains the flat share price: the policy "will take time to implement," and the company "has confidence in its previously communicated financial guidance for 2026." Longer-term numbers wait for a December investor conference.
Those previously communicated numbers are not modest. Edwards, which sells the SAPIEN valve platform plus mitral and tricuspid devices and a legacy surgical valve line to hospitals worldwide, has raised 2026 guidance twice: January's 8-10% sales growth became 9-11% in April and 10-11% in July, with aortic valve growth guidance going from 6-8% to 8-9% and the transcatheter mitral and tricuspid line lifted to $760-780m. Second-quarter revenue was $1.741bn, up 13.6%, at a 77.6% gross margin, and operating income grew 20.6% — faster than sales. Aortic valve sales reached $1.26bn, up 10.5% in constant currency; the mitral and tricuspid business grew 44.8% to $195.9m. Chief executive Bernard Zovighian told investors on the July 23 call that "years of technology advancement and world-class evidence" had positioned SAPIEN as "the benchmark TAVR platform globally." Edwards holds more than 60% of the US market.
What actually moved the shares
The month's decline came from elsewhere in the device complex. On September 8 Stryker fell 7.4% after its finance chief told the Wells Fargo Healthcare Conference that supply disruption from a March cyberattack on its peripheral-vascular manufacturing would persist into the fourth quarter. Boston Scientific fell 4.6%, having disclosed that an August 25 cyberattack disrupted global ordering and shipping badly enough that it will miss third-quarter and full-year sales and earnings expectations. Edwards fell 3.5% alongside them. Over thirty days Stryker is down 20.0% and Boston Scientific 16.3%, against Edwards' 9.2%; Medtronic, the direct rival in aortic valves, is up slightly. When HCA Healthcare flagged soft surgical volumes in July, the weakness was in orthopedics and spine among under-65 patients — cardiovascular was the category analysts explicitly spared.
Artivion, the other name that looks broken here, is a different business and a different story. It sells On-X mechanical valves, aortic stent grafts, surgical adhesive and cryopreserved human tissue — open surgery and endovascular, nothing transcatheter. Its 40.7% twelve-month loss is anchored on one session, May 8, when it fell 28.3% after cutting guidance. The second quarter was better: revenue of $125.8m, stent grafts up 12% and On-X up 18% in constant currency. But operating income swung to a loss of $8.4m from a profit of $8.4m, gross margin slipped to 64.0%, and net leverage sits at 3.1x after the Endospan purchase. Chief executive Pat Mackin described the bottleneck on the August 6 call as procurement rather than patients: accounts with ethics-board and value-committee approval "waiting on a PO because this is not normal that they have to write a check for $100,000." With earnings negative, the usable anchor is price against gross profit, at 4.11x trailing — a de-rating the income statement earned.
The verdict
There is no procedure-volume signal running through structural heart. There are two cyberattacks, one small company's balance sheet, and one large company whose regulatory gate just widened while its growth accelerated. Edwards at 28.1x forward earnings is roughly double Medtronic's 15.2x and Boston Scientific's 13.1x, for roughly double their forward revenue growth — an expensive share that has given back a slice of its premium, not a business in trouble.
What the September 10 rule is worth in dollars, nobody has said — including the company that asked for it. Edwards put a number on everything else this year and deferred this one to December.