

Texas Roadhouse Met 7% Beef Inflation With a 1.9% Menu Increase and Won 3% More Guests
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A steakhouse chain posting the best sales volumes of its 33-year history just reported lower operating profit than a year ago, and it did so on purpose. Texas Roadhouse reviews menu prices twice a year and deliberately prices below its costs to protect traffic — so food and beverage cost climbed to 35.4% of restaurant sales from 34.0%, and restaurant-level margin fell to 16.4%.
It worked on the top line: same-store sales rose 6.2%, half of that from guest counts, while the wider US restaurant industry lost 4% of its customers in July. Bloomin' Brands ran the opposite play — roughly 4.5% pricing against 4.5–5.5% inflation — and raised guidance while Outback traffic fell.
The cost shock is not over: the cattle herd is at a multi-decade low and only 40% of Texas Roadhouse's fourth-quarter basket is locked.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
TXRH | Texas Roadhouse | Casual Dining - Steakhouse & Seafood | 🌱 Emerging Bull | −13.9% | +9.6% |
BLMN | Bloomin' Brands | Casual Dining - Steakhouse & Seafood | 🌱 Emerging Bull | −21.0% | +28.2% |
| Compared against · context, not the story | |||||
EAT | Brinker International | Casual Dining - Full Service | 🌱 Emerging Bull | −11.1% | +38.3% |
DRI | Darden Restaurants | Casual Dining - Full Service | 🟢 Cont. Bull | −5.8% | +1.0% |
CAKE | The Cheesecake Factory Incorporated | Casual Dining - Full Service | 🟢 Cont. Bull | −9.2% | +84.5% |
CBRL | Cracker Barrel Old Country Store | Casual Dining - Full Service | 🌱 Emerging Bull | −15.7% | −1.2% |
SHAK | Shake Shack | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −12.7% | −36.8% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.6% | +17.2% |
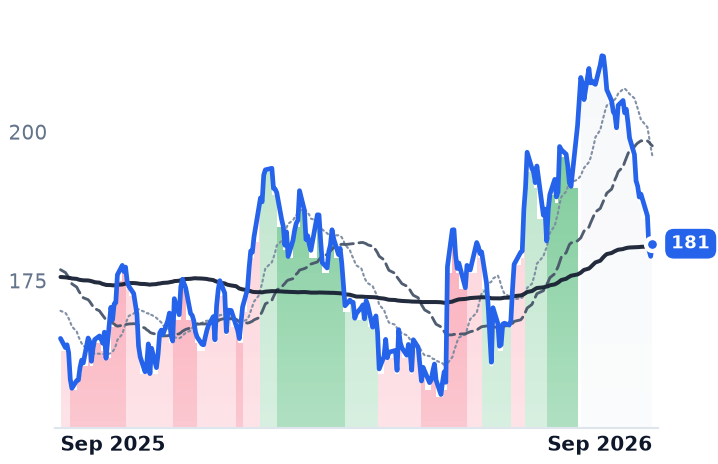
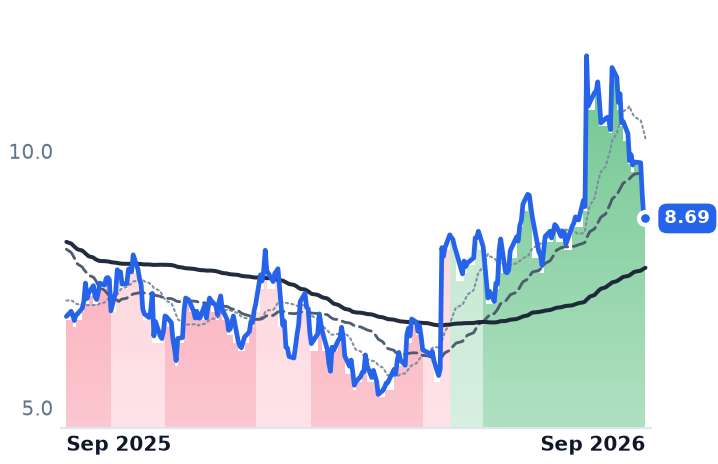
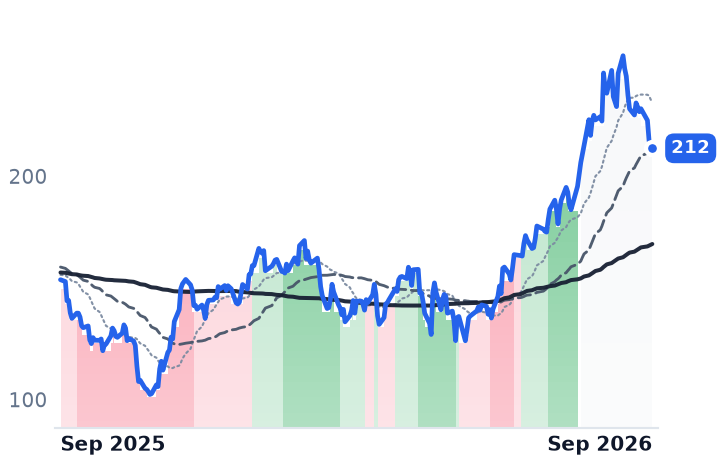
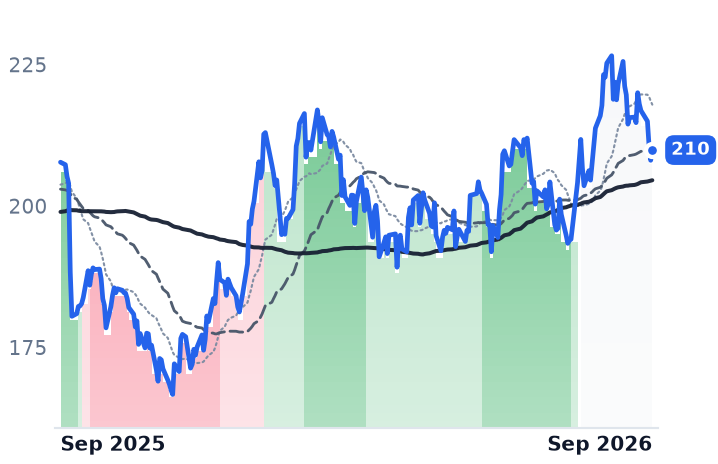
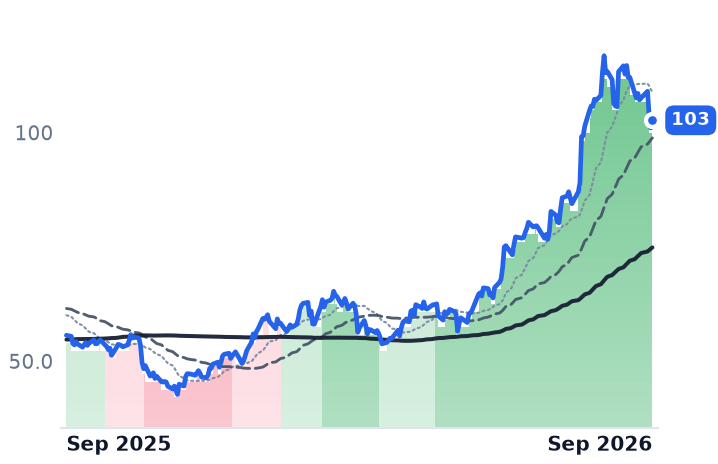
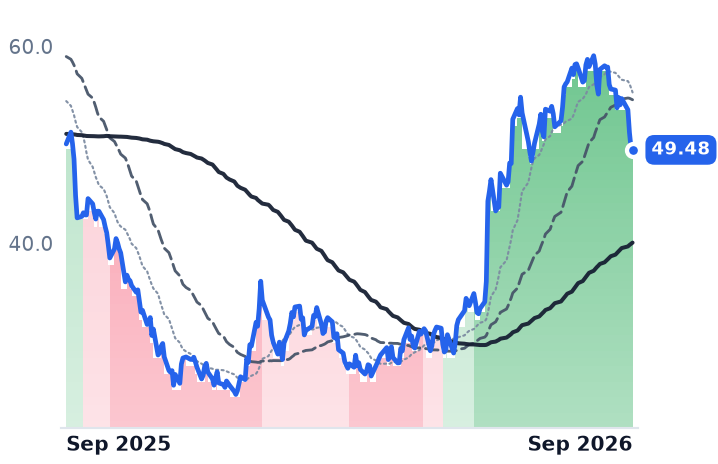
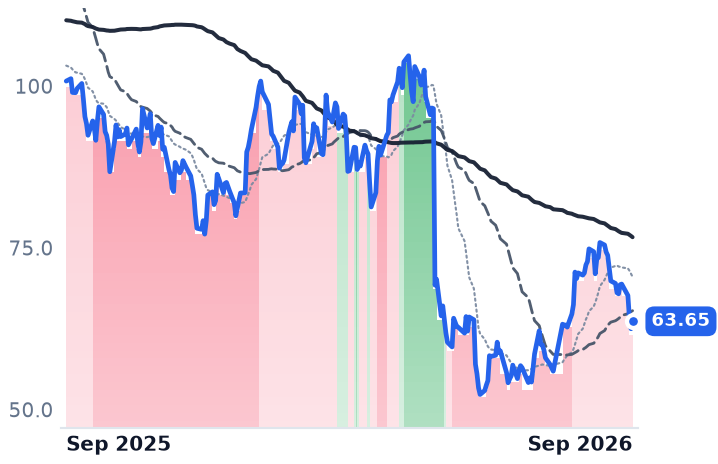
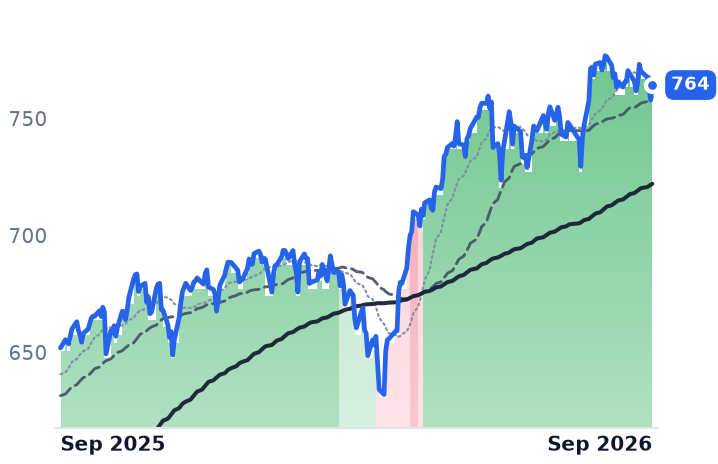
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXRH | $11.9B | 28.9x | 27.4x | 1.9x | 1.8x | 12.5x | 11.9x | 16.7x | 3.4% |
BLMN | $744.0M | 27.2x | 8.9x | 0.2x | 0.2x | 0.5x | 0.5x | 11.1x | 20.8% |
EAT | $10.2B | 21.2x | 18.9x | 1.8x | 1.7x | 9.4x | 8.9x | 14.0x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DRI | $25.8B | 21.5x | 20.0x | 2.0x | 1.9x | 2.8x | 2.7x | 13.5x | 4.3% |
CAKE | $5.6B | 29.6x | 25.4x | 1.5x | 1.4x | 3.1x | 3.0x | 23.6x | 3.7% |
CBRL | $1.3B | 49.2x | 52.6x | 0.4x | 0.4x | 1.1x | 1.1x | 14.6x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SHAK | $2.4B | 59.1x | 49.0x | 1.6x | 1.5x | 8.5x | 7.6x | 16.8x | 1.5% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TXRH | Revenue | +11.0% | +9.3% | +8.6% |
| EPS | +4.7% | +18.3% | +20.8% | |
BLMN | Revenue | +0.6% | +1.6% | +2.6% |
| EPS | −12.9% | +9.8% | +17.1% | |
EAT | Revenue | +8.1% | +6.0% | +4.2% |
| EPS | +21.2% | +16.7% | +10.0% | |
DRI | Revenue | +9.5% | +3.6% | +6.0% |
| EPS | +11.5% | +6.2% | +9.9% | |
CAKE | Revenue | +7.3% | +7.3% | +8.4% |
| EPS | +18.7% | +10.6% | +12.9% | |
CBRL | Revenue | −4.9% | +2.7% | +2.7% |
| EPS | −101.4% | −2570.0% | +42.1% | |
SHAK | Revenue | +14.8% | +15.1% | +13.2% |
| EPS | −4.4% | +29.2% | +26.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Texas Roadhouse served more guests in its June quarter than in any quarter of its 33-year history, and made less money doing it. Average weekly sales per restaurant passed $175,000 for the first time, while operating income fell 2.4% from a year earlier on revenue up 11.1% to $1.68bn.
That gap is a decision, not an accident. The chain — which runs company-owned and franchised steakhouses under the Texas Roadhouse, Bubba's 33 and Jaggers names from Louisville, Kentucky — took a menu price increase of about 1.9% into a quarter that carried 7% commodity inflation. Food and beverage cost rose to 35.4% of restaurant and other sales from 34.0%, and restaurant-level margin slipped 66 basis points to 16.4%. The company's 10-Q for the 26 weeks ended June 30 puts the half-year figures at $1,165.8m of food cost against $3,299.6m of restaurant sales.
"We are not going to be able to price for every beef inflation as of right now, but we want to make sure that we protect the value side of our business," chief executive Jerry Morgan told an earnings call, describing a practice of reviewing menu prices only twice a year.
What the unpriced inflation bought
Traffic. Guest counts rose 3% in the quarter, and with 3.2 points of higher average check that made same-store sales of 6.2% — bought while the American restaurant industry was shedding customers, with nationwide guest counts down 4% in July, the weakest reading since 2017. Share was taken from somebody. It is arriving at the cheap end of the menu: "Some of those are probably going more towards the value side of our menu, the 6-ounce sirloin and the other lower-priced items," investor relations vice president Michael Bailen said on the second-quarter call.
Labor is what keeps the model standing. Restaurant labor improved 40 basis points to 32.5% of sales, with hours up just 0.8% against those record volumes — near-flat staffing absorbing more covers.
The cost side is structural rather than seasonal. The US cattle herd stood at 86.2 million head in January, a multi-decade low, and feeder prices are high enough that producers are selling heifers rather than breeding them, so rebuilding has not started. The choice cutout was still firming in early September at $373.78 per hundredweight. Washington's 90-day suspension of tariffs on up to 300,000 metric tons of imported beef, effective September 1, targets ground beef — not the steak cuts that dominate a steakhouse basket. Texas Roadhouse nonetheless cut its own full-year commodity guide to roughly 5% from 6–7% on cheaper sirloin, and has about 80% of its basket locked for the third quarter but only 40% for the fourth.
The mirror, and the price
Bloomin' Brands, the Tampa operator of Outback Steakhouse, Carrabba's, Bonefish Grill and Fleming's, runs the same trade backwards. "We still see commodity inflation running basically 4.5% to 5.5% for the year. That's been consistent. We see pricing in about the 4.5% range. So pretty balanced," chief financial officer Eric Christel told investors on August 5. Average check rose 420 basis points; Outback traffic fell 280. Adjusted earnings per share reached $0.39 from $0.32 and full-year guidance was raised to $0.90–$1.00 that same day. Bloomin' defends the profit line and keeps losing guests; at 8.9x forward earnings, with lease-adjusted net leverage of 3.7x against a 3.0x target and the dividend suspended, the market is not paying for the defense either.
Both shares fell hard through late August and early September — Texas Roadhouse 14.8% in the month to September 11, Bloomin' 23.4% — but so did Brinker, Cracker Barrel and Cheesecake Factory, all down between 12% and 15%, while the S&P 500 exchange-traded fund slipped 1.1%. No company-level negative revision appeared in either name during the window; the likelier reading is a de-rating of a group that had run roughly 62% at the median over the prior three months.
Some of the de-rating is earned. Texas Roadhouse's forward earnings multiple has compressed to 27.4x from 32.2x in mid-August, and that still buys a year in which consensus has earnings per share growing 4.7%, against Brinker's Chili's — which took 4.3 points of pricing and still grew traffic — at 18.9x. The business is not breaking: it is converting record volumes into flat profit by design, and the market has begun charging it for the design. What nothing in the fundamentals explains is the speed, or why a favorable commodity revision landed in the same weeks as the worst drawdown of the year.
The fourth quarter is where the choice gets tested. Only two-fifths of the basket is locked, another 1% of menu price goes on at the start of it, and 2027 is open at spot.