

Dell's Data-Center Profit More Than Tripled to $4.8bn; HPE Now Reprices Booked Orders
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Server assemblers were supposed to be the victims of the memory shock. Both of the big American ones came out of it with fatter margins than they went in.
Dell's group gross margin recovered to 20.9% in the July quarter from 17.8% three months earlier, and its Infrastructure Solutions Group earned a record operating profit at a 15% margin, 6.2 percentage points better than a year ago. Hewlett Packard Enterprise posted a record 40.1% gross margin after amending its quoting terms so that a booked order can be repriced for component-cost increases between quote and shipment. Contract DRAM roughly doubled in the first quarter of 2026; both companies repriced faster.
The unresolved part: the 11 September jump in both stocks followed Oracle's capital-expenditure numbers rather than their own, and HPE's management says the record margin moderates from here.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
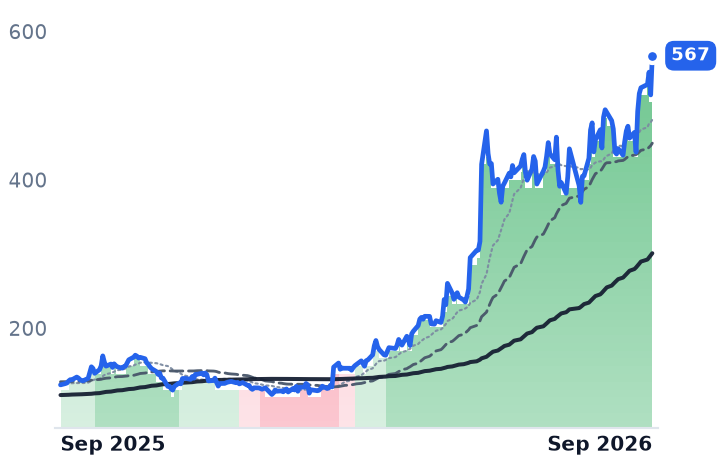
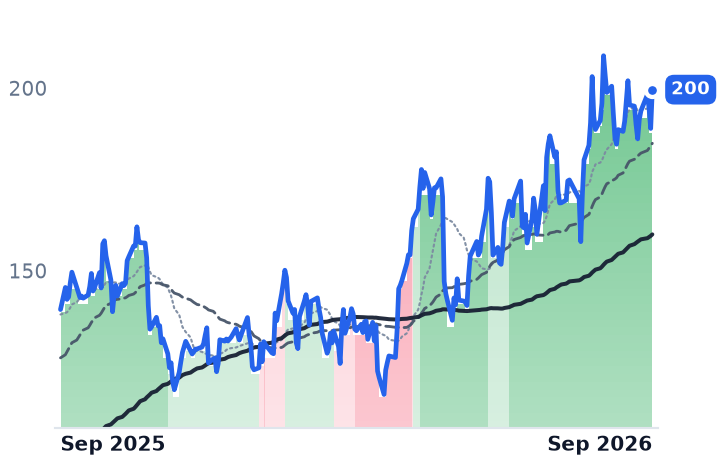
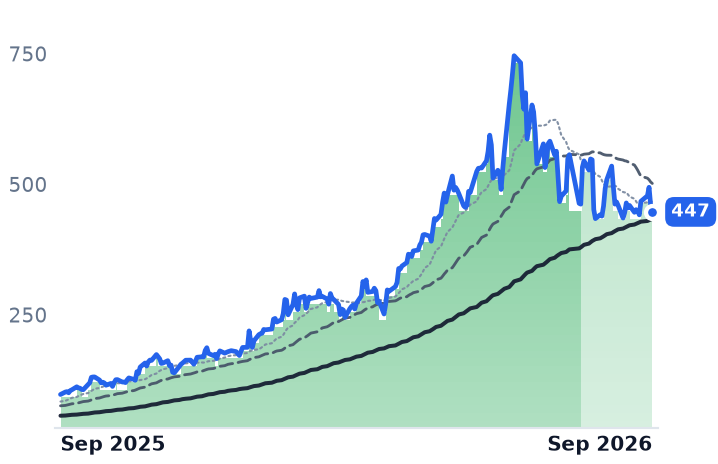
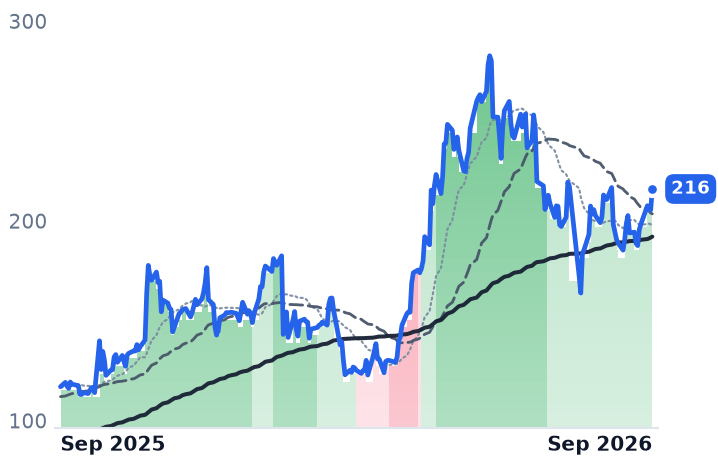
DELL | Dell Technologies | Enterprise Storage & Software | 🟢 Cont. Bull | +14.7% | +358.7% |
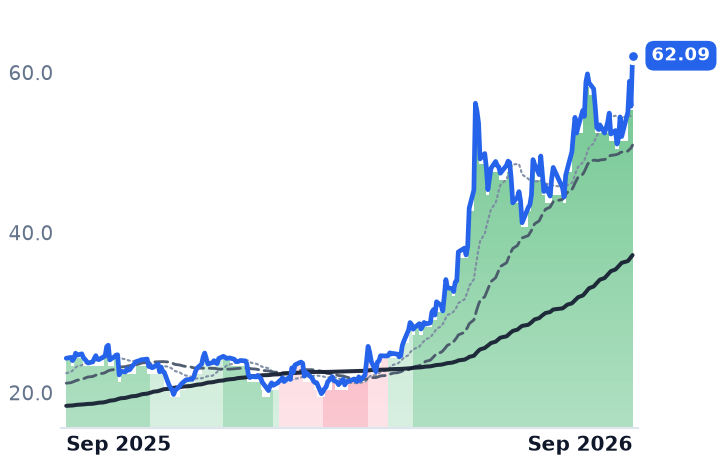
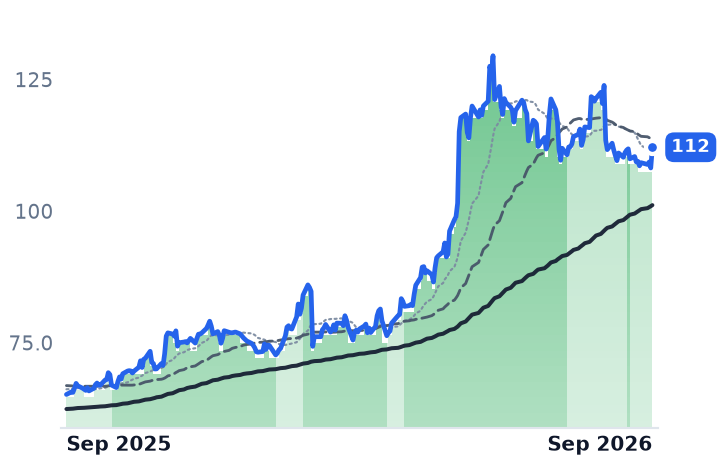
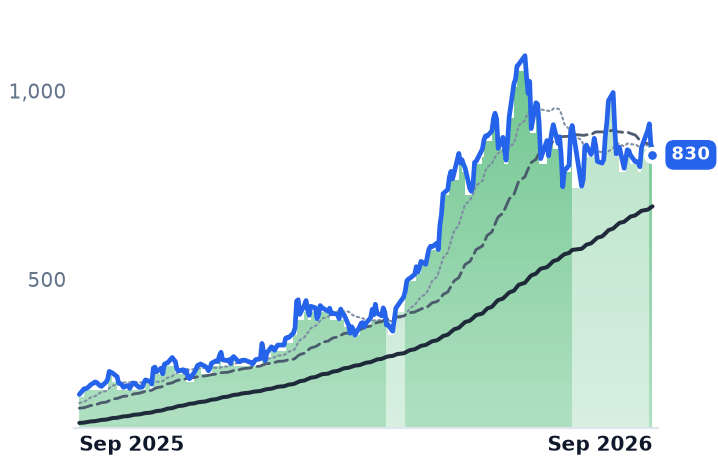
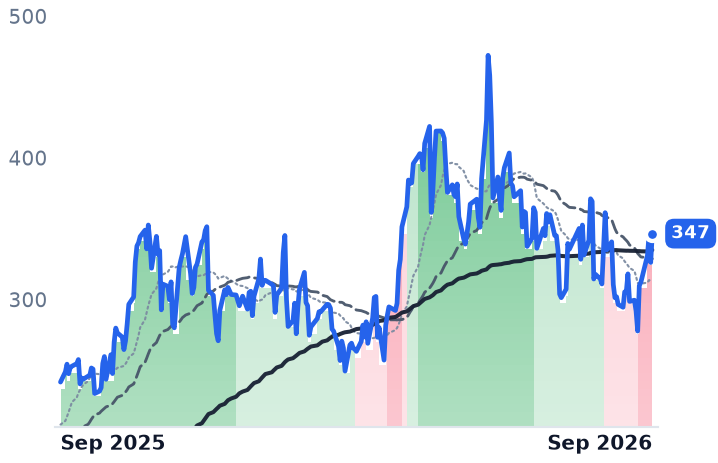
HPE | Hewlett Packard Enterprise | Enterprise Storage & Software | 🟢 Cont. Bull | +3.8% | +155.6% |
| Compared against · context, not the story | |||||
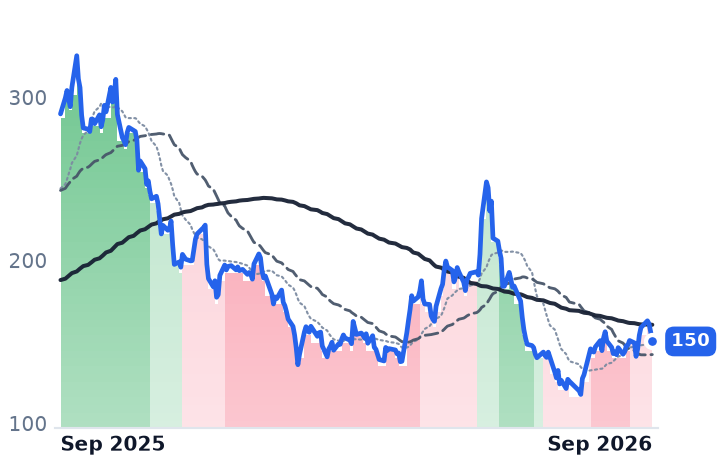
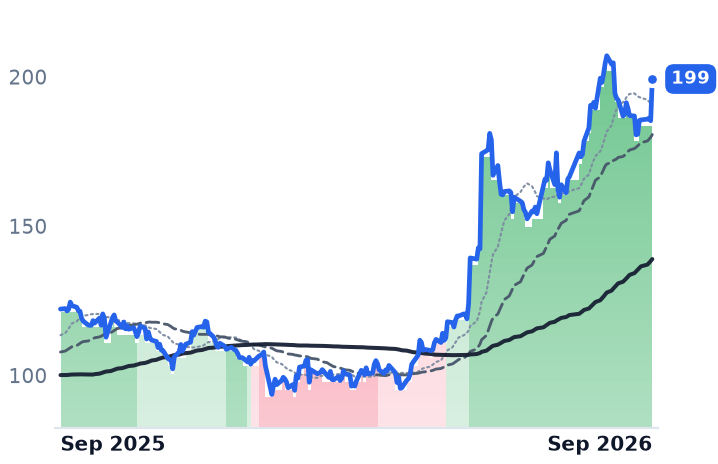
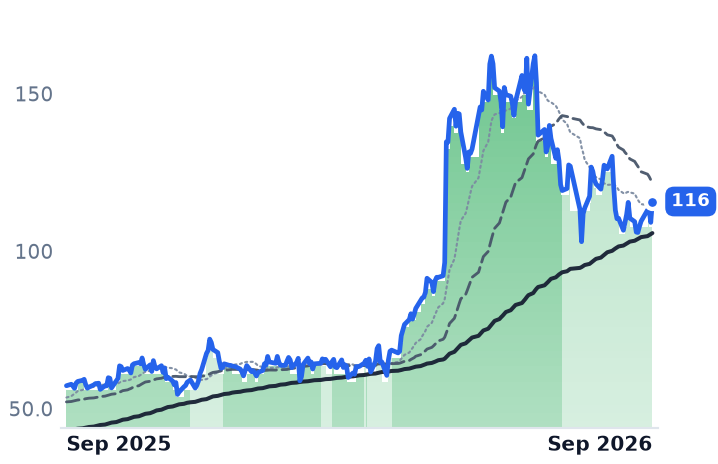
ORCL | Oracle | Cloud Infrastructure & Platforms | 🔴 Cont. Bear | −3.8% | −48.2% |
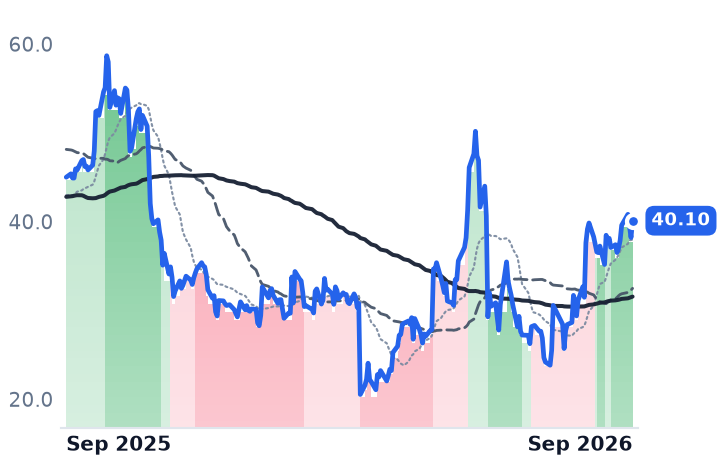
SMCI | Super Micro Computer | Server & Infrastructure Systems | 🌱 Emerging Bull | +2.4% | −10.9% |
ANET | Arista Networks | Cloud Networking | 🟢 Cont. Bull | −2.0% | +43.2% |
CSCO | Cisco Systems | Enterprise Networking Infrastructure | 🟢 Cont. Bull | −1.2% | +72.0% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | −3.1% | +22.8% |
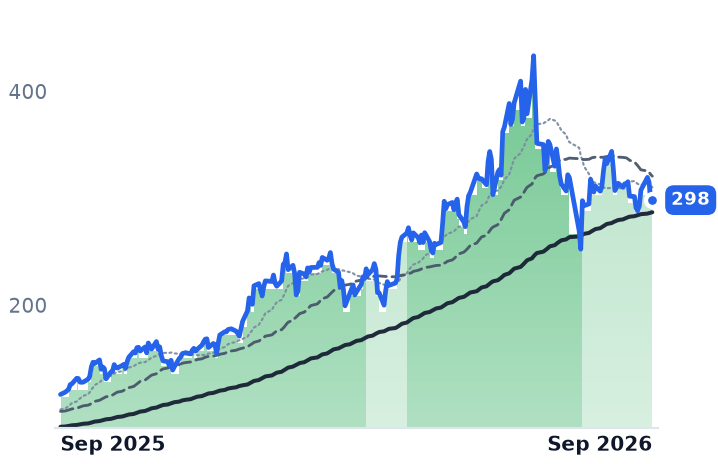
MU | Micron Technology | Memory (DRAM/NAND) | 🟢 Cont. Bull | +0.3% | +521.2% |
WDC | Western Digital | Data Storage Devices | 🟢 Cont. Bull | −9.1% | +358.5% |
STX | Seagate Technology | Data Storage Devices | 🟢 Cont. Bull | −9.4% | +326.8% |
LRCX | Lam Research | Semiconduct Equipment | 🟢 Cont. Bull | −11.5% | +156.2% |
NTAP | NetApp | Enterprise Storage & Software | 🌱 Emerging Bull | −2.6% | +63.0% |
SANM | Sanmina | Electronic Manufacturing Services | 🟢 Cont. Bull | +2.6% | +84.6% |
CLS | Celestica | Electronic Manufacturing Services | ⚠️ Emerging Bear | −4.1% | +43.3% |
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | −8.6% | +102.1% |
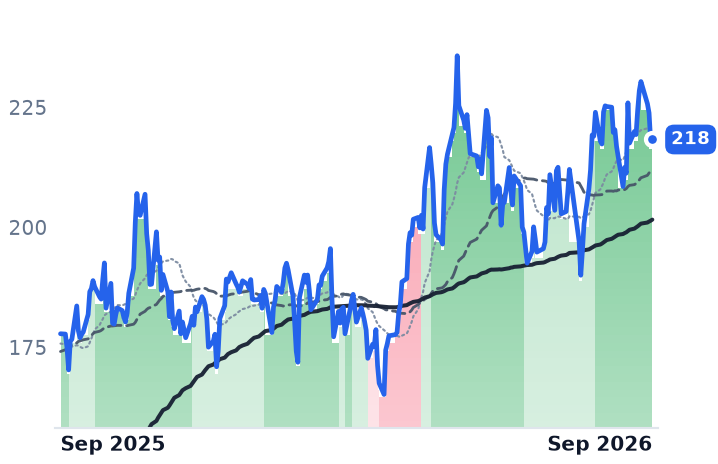
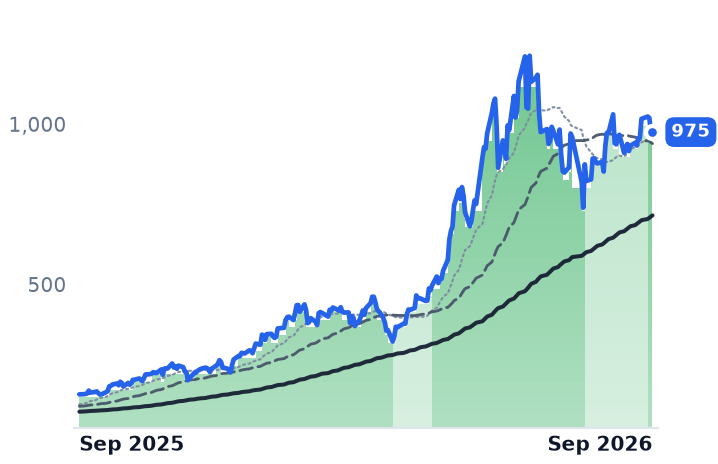
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DELL | $376.7B | 32.4x | 21.9x | 2.5x | 1.9x | 12.6x | 9.8x | 21.7x | 2.3% |
HPE | $82.2B | 30.9x | 16.3x | 2.0x | 1.8x | 5.4x | 4.9x | 17.0x | 5.1% |
ORCL | $433.0B | 25.3x | 18.7x | 6.4x | 4.8x | 9.8x | 7.3x | 17.4x | -5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SMCI | $24.1B | 10.2x | 8.6x | 0.6x | 0.4x | 5.7x | 3.3x | 7.7x | -28.9% |
ANET | $237.5B | 58.8x | 45.9x | 22.5x | 18.7x | 35.8x | 29.8x | 46.1x | 2.2% |
CSCO | $442.9B | 33.4x | 21.9x | 7.0x | 6.1x | 10.8x | 9.4x | 23.2x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
WDC | $166.1B | 25.6x | 48.3x | 14.1x | 12.9x | 31.1x | 28.4x | 31.1x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STX | $178.4B | 73.9x | 53.5x | 16.2x | 14.8x | 39.0x | 35.7x | 53.6x | 1.5% |
LRCX | $430.0B | 59.4x | 36.7x | 18.5x | 12.4x | 36.7x | 24.6x | 49.2x | 1.1% |
NTAP | $35.9B | 28.5x | 20.3x | 5.2x | 4.8x | 7.3x | 6.7x | 18.7x | 5.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SANM | $10.1B | 33.1x | 15.6x | 0.8x | 0.7x | 8.8x | 7.9x | 16.0x | 5.9% |
CLS | $33.6B | 30.1x | 25.9x | 2.2x | 1.6x | 18.6x | 14.0x | 22.5x | 1.5% |
FLEX | $39.5B | 41.3x | 22.7x | 1.3x | 1.1x | 14.2x | 12.0x | 22.4x | 2.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DELL | Revenue | +16.2% | +74.0% | +21.0% |
| EPS | +27.3% | +159.6% | +19.4% | |
HPE | Revenue | +34.6% | +16.4% | +7.3% |
| EPS | +100.3% | +19.9% | +11.6% | |
ORCL | Revenue | +17.8% | +33.2% | +45.5% |
| EPS | +25.3% | +7.6% | +35.6% | |
SMCI | Revenue | +77.7% | +69.8% | +17.7% |
| EPS | +33.5% | +54.8% | +23.3% | |
ANET | Revenue | +42.4% | +30.0% | +23.9% |
| EPS | +42.4% | +27.2% | +22.5% | |
CSCO | Revenue | +11.1% | +16.2% | +7.1% |
| EPS | +12.9% | +19.7% | +9.2% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
WDC | Revenue | +36.9% | +37.2% | +26.5% |
| EPS | +106.2% | +72.8% | +48.0% | |
STX | Revenue | +32.7% | +35.9% | +24.9% |
| EPS | +86.9% | +77.9% | +48.0% | |
LRCX | Revenue | +27.0% | +49.0% | +18.6% |
| EPS | +41.9% | +64.7% | +25.5% | |
NTAP | Revenue | +4.3% | +10.1% | +5.7% |
| EPS | +10.4% | +13.1% | +11.5% | |
SANM | Revenue | +74.9% | +15.8% | +11.8% |
| EPS | +103.4% | +15.2% | +12.7% | |
CLS | Revenue | +68.2% | +71.8% | +32.5% |
| EPS | +89.2% | +73.1% | +34.7% | |
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.7% | +51.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The memory-price shock was supposed to be the thing that broke the companies that bolt other people's silicon into racks. Dell Technologies, which builds servers, storage and networking for data centers under Infrastructure Solutions Group and sells PCs through Client Solutions Group, bought its July-quarter components into a market where conventional contract DRAM prices had risen roughly 93% to 98% in the first quarter of 2026 and a further 58% to 63% in the second. Its gross margin came out of the quarter higher than it went in: 20.9%, against 17.8% in April.
That is the whole question for an assembler. Its earnings are a spread between a dollar figure contracted quarters ago and a bill of materials bought later, and Dell exited July with a record $95bn of AI server backlog priced against components nobody has purchased yet. The evidence from the two prints that preceded this month's rally is that both American integrators have won that argument with their customers — so far.
Dell repriced, and the dollars followed
Infrastructure Solutions Group revenue reached a record $31.8bn, up 89%, with operating income of $4.8bn, up 225% at a 15% margin — 6.2 percentage points better than a year earlier. Group revenue rose 58% to $47bn and operating income 209%. Orders ran far ahead of shipments: $60.9bn of AI server orders booked against $16.4bn recognized. "We exited the quarter with a record $95 billion of AI backlog, and our pipeline continued to grow sequentially and remains multiples of our backlog even after converting $131.7 billion into orders over the past 12 months," Jeff Clarke, Dell's chief operating officer, told investors on September 1.
Dell named DRAM and NAND as its primary bottlenecks and said its raised full-year guidance — $192bn of revenue and $25.50 of earnings per share — reflects supply reconfiguration, including redirecting PC components into infrastructure. Client Solutions Group still grew 20% to $15.0bn, and traditional server and networking revenue rose 122%. Diluted share count fell to 652m from 702m.
HPE made the quoted price provisional
Hewlett Packard Enterprise took the contractual route. "We have amended our quoting terms with a right to reprice existing orders for commodity cost increases between quoting and shipment," chief executive Antonio Neri said, a clause that covers ProLiant servers, Alletra and Nimble storage and GreenLake orders. Gross margin hit a record 40.1% against 28.4% a year earlier, and Neri has said no customer in a round of European meetings called the increases too expensive.
The mix did the rest. "We are at the core becoming a networking company," Neri said on September 2. Networking revenue grew 10% but orders grew 36%, and chief financial officer Marie Myers told investors: "Cumulative networks for AI orders were $2.2 billion, surpassing our FY '26 target. As a result, we are increasing our year-end target to $2.5 billion to $3 billion." The merged Cloud and AI segment did $9bn at a 17% operating margin. Against that, GreenLake is the slow limb — customers up 18% to 52,000, with no run-rate figure given against a $3.5bn target for the year — and the ~$14bn Juniper purchase leaves net leverage at 1.8x plus mandatory convertible preferred stock paying a 7.625% dividend. Management guides the record gross margin to moderate in the fourth quarter and next year as AI systems take more of the mix.
The day that repriced the customer
Neither company changed guidance on September 11, when Dell rose 10.3% and HPE 11.3%. The session followed Oracle's quarterly capital expenditure of $28.5bn against $8.5bn a year earlier, with the full-year budget held at $90–95bn. The move was confined to the integrators and the network — Arista gained 5.6%, Super Micro 5.0%, Cisco 3.6% — while the memory and disk makers selling into the same racks did nothing or fell, Micron flat and Western Digital and Seagate down. The buyer was repriced; the bill of materials was not. HPE has a direct claim on that budget: on September 8 the two companies announced a gigawatt-scale deal putting Juniper routing and switching across Oracle's data centers.
What the business earns and what it does not
The margin expansion is earned, and it is the answer to the worry that a fixed-price backlog is a trap. Dell sits at 21.9x forward earnings against 32.4x trailing, barely above the roughly 18x it carried in May at $240, because forward estimates were rebuilt faster than the price rose; consensus has earnings up 160% this year and 19% next. HPE is at 16.3x forward and about 13.6x next year's consensus, against a 10–13x anchor from the spring, and its trailing enterprise value to EBITDA has fallen to 17.0x from 21.2x on September 1 — the new quarter added profit to the denominator while the stock rose.
What neither print settles is who pays for the backlog. Dell's financing arm originated $7.5bn in the quarter against $2.4bn a year earlier, and its principal charge-off rate went to 0.5% from 0.1% — small, but five times larger. Oracle, the customer whose budget moved both stocks, carries $125bn of debt and burned $5.4bn of free cash flow in the quarter while promising tens of billions more of issuance.
The repricing clause protects the seller from its suppliers. It does not protect the seller from a buyer that cannot pay, and the largest order books in this industry are now written against balance sheets that are funding them with debt.