

Two-Thirds of BWXT's Revenue Grew 2% While the Rest Grew 72% at Half the Margin
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
BWX Technologies told investors its naval revenue would grow more slowly this year because it is spending less of the Navy's money — under cost-reimbursable contracting, reported revenue falls when costs do. Management cut Government Operations revenue-growth guidance to high single digits from low teens and simultaneously raised that segment's adjusted EBITDA margin target to about 20.5% from above 19%.
The rest of the company behaves in the opposite way: Commercial Operations grew fast, largely on an acquisition, at an 8.0% operating margin. That mix is why June-quarter revenue rose 18% while reported operating income fell 12.2%. Backlog stands at $8.4bn and all four 2026 guidance lines were raised, including free cash flow.
The other name filed under the same advanced-fuels heading, Lightbridge, has never reported revenue and trades slightly below its $237.5m of cash.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
BWXT | BWX Technologies | Naval & Shipbuilding | ⚠️ Emerging Bear | −10.1% | −10.1% |
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −17.2% | −47.8% |
| Compared against · context, not the story | |||||
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −13.4% | −50.1% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | +7.9% | −71.0% |
LEU | Centrus Energy | Uranium | ⚠️ Emerging Bear | −11.3% | −25.8% |
XE | X-Energy | Power & Propulsion Systems | 🔴 Cont. Bear | −18.6% | −43.6% |
NNE | Nano Nuclear Energy | Power & Propulsion Systems | 🔴 Cont. Bear | −8.5% | −46.8% |
HII | Huntington Ingalls Industries | Naval & Shipbuilding | ⚠️ Emerging Bear | −13.6% | +3.0% |
GD | General Dynamics | Large Diversified Primes | 🟢 Cont. Bull | −9.9% | +8.8% |
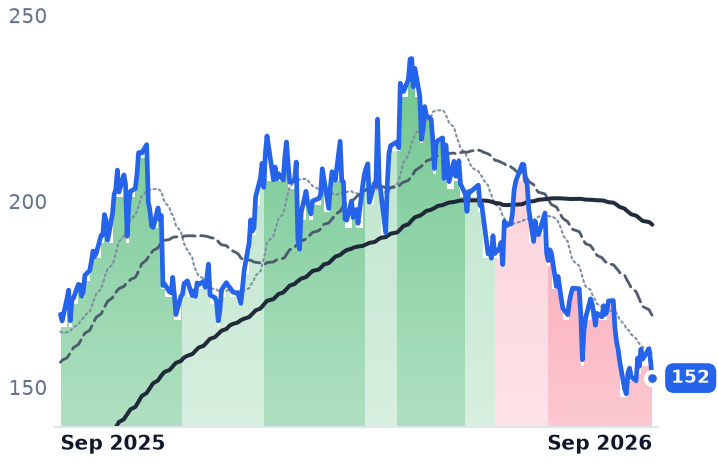
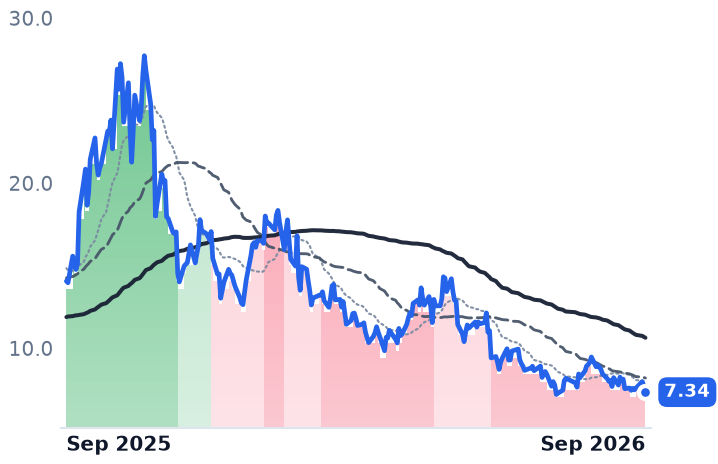
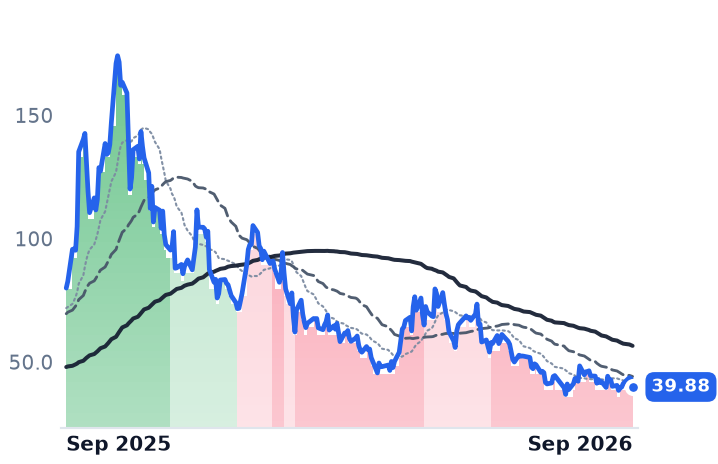
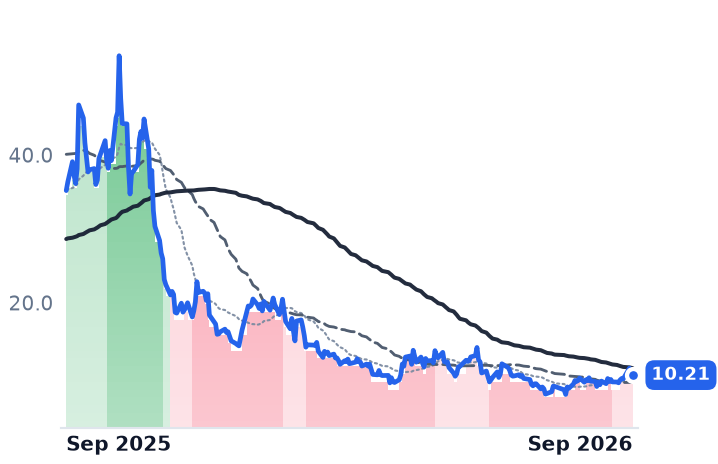
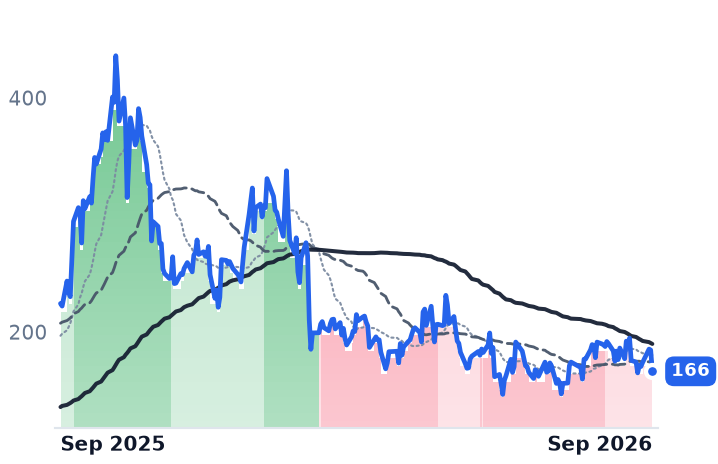
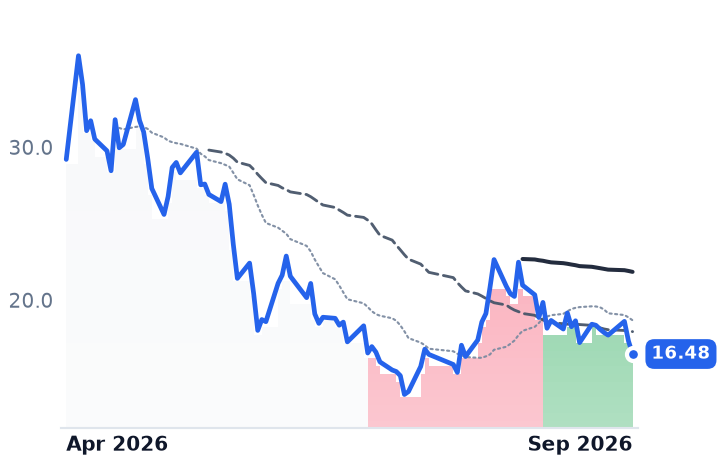
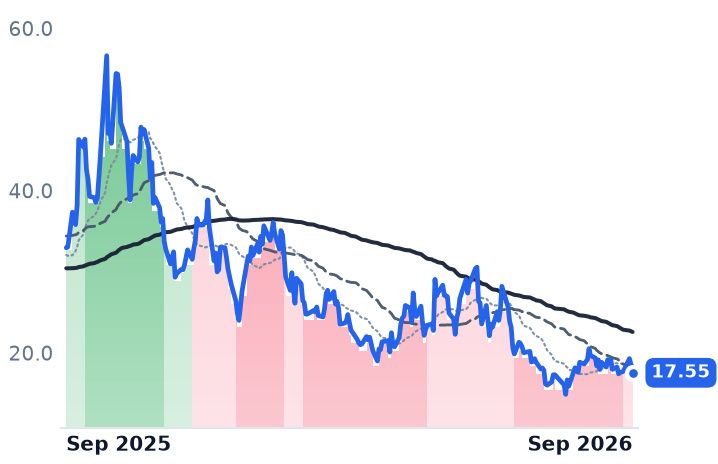
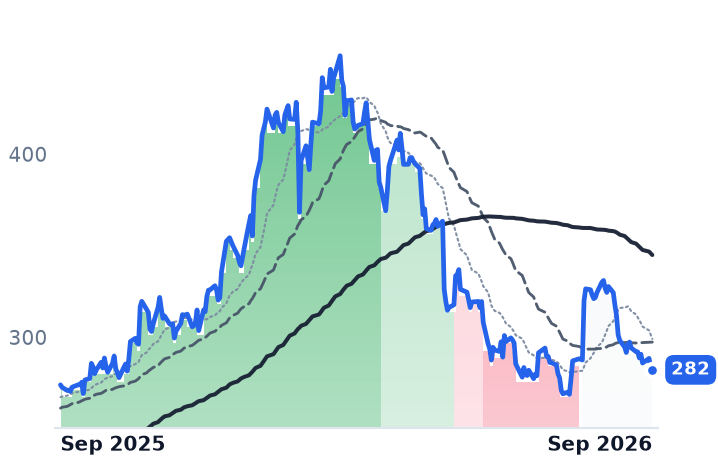
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $14.0B | 39.3x | 32.2x | 4.0x | 3.7x | 18.0x | 16.7x | 27.8x | 2.3% |
LTBR | $258.0M | n/m | — | n/m | — | — | — | n/m | -6.6% |
OKLO | $6.9B | n/m | — | — | — | — | — | n/m | -4.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
LEU | $3.5B | 73.9x | 73.1x | 7.4x | 7.5x | 31.9x | 32.1x | 38.9x | -6.3% |
XE | $381.7M | n/m | — | 3.5x | 1.8x | — | — | 0.3x | -70.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NNE | $1.1B | n/m | — | — | 887.7x | — | — | n/m | -3.7% |
HII | $11.3B | 17.0x | 15.3x | 0.9x | 0.8x | 6.8x | 6.7x | 12.7x | 3.3% |
GD | $90.5B | 20.8x | 20.1x | 1.7x | 1.6x | 11.0x | 10.7x | 15.2x | 6.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWXT | Revenue | +20.6% | +9.6% | +7.0% |
| EPS | +24.1% | +11.6% | +11.7% | |
OKLO | Revenue | — | +252.7% | +552.9% |
| EPS | +57.1% | +9.6% | +13.5% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% | |
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.4% | +12.2% | −22.3% | |
XE | Revenue | +83.1% | +253.8% | +46.2% |
| EPS | −98.0% | −1.4% | −33.6% | |
NNE | Revenue | +1684.0% | +356.5% | +39.0% |
| EPS | −23.4% | +55.2% | +34.3% | |
HII | Revenue | +10.8% | +6.4% | +6.4% |
| EPS | +23.6% | +12.3% | +16.4% | |
GD | Revenue | +6.4% | +4.6% | +4.2% |
| EPS | +7.9% | +9.5% | +7.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
BWX Technologies sells most of what it makes to one customer under contracts that reimburse its costs, and in August it told investors that segment's revenue would grow more slowly this year — because it had found ways to spend less. On the August 3 second-quarter call, management cut 2026 Government Operations revenue-growth guidance to high single digits from low teens on stronger cost performance, and in the same breath raised that segment's adjusted earnings-before-interest-taxes-depreciation-and-amortization margin guide to roughly 20.5% from above 19%.
That is the mechanism a nuclear-labeled stock chart cannot show. BWXT, a Lynchburg, Virginia manufacturer of naval reactors, nuclear fuel and missile launch tubes for the US Navy's propulsion program, books cost-type work: lower reimbursed cost means a smaller revenue line and a better fee margin. Investors reading the government revenue line as a demand meter are reading an accounting artifact — and it is the line that matters most, because Government Operations was $601.3m of the $901.6m BWXT reported for the June quarter, growing 2% year over year at a 17.6% segment operating margin.
The growth is in the lower-margin half
Everything that grew fast sits in Commercial Operations — Canadian reactor components, fuel handling, and, since the Precision Components Group deal closed in early July, US commercial manufacturing including AP1000 content. That segment produced $302.5m of revenue, up 72% (33% of it organic), and $24.3m of operating income: an 8.0% margin, less than half the government business earns.
So the company grew revenue 18% and reported operating income of $89.9m, down 12.2%. Gross margin fell to 22.44% from 25.05% a year earlier. That pattern is not new — reported operating income has declined year over year in each of the last four quarters, and full-year 2025 operating income fell 15.1% on an 18.3% revenue gain. Acquired, capacity-hungry commercial work is diluting a franchise margin. Management also trimmed the Commercial Operations margin guide to about 13% from about 14%, citing capacity expansion and hiring, with recovery expected in 2027.
Demand is funded; the build rate is the constraint
Backlog ended the quarter at $8.4bn, up 40%, on trailing book-to-bill of 1.7x — though that is a step down from the $8.7bn peak the prior quarter, when a $1.4bn Naval Reactors pricing tranche landed. On July 29 the Navy awarded $76.6bn to General Dynamics and HII for nine Virginia-class and five Columbia-class submarines. The money is there; the boats are late. The first Columbia boat is running roughly 12 to 17 months behind, and Virginia-class construction runs near one boat a year against a two-a-year target the Navy's own chief has told Congress will not arrive until about 2032.
All four 2026 guidance lines went up on August 3: revenue to about $3.8bn, adjusted EBITDA to $662–672m, adjusted earnings per share to $4.70–4.80, and free cash flow to $345–360m from an initial $315–330m — the opposite of a capacity program strangling cash. BWXT is also selling its medical business to Nordic Capital for up to $800m, roughly $130m of revenue, keeping a 20% stake. On August 26 the Army paired its BANR microreactor with Fort Campbell under the Janus program. The commercial order the bull case wants is still pending: "Although award timing can be difficult to predict our customer discussions are advancing," chief executive Rex Geveden said on the August 3 call, guiding to at least one new-build equipment order by year-end without committing.
What the multiple did
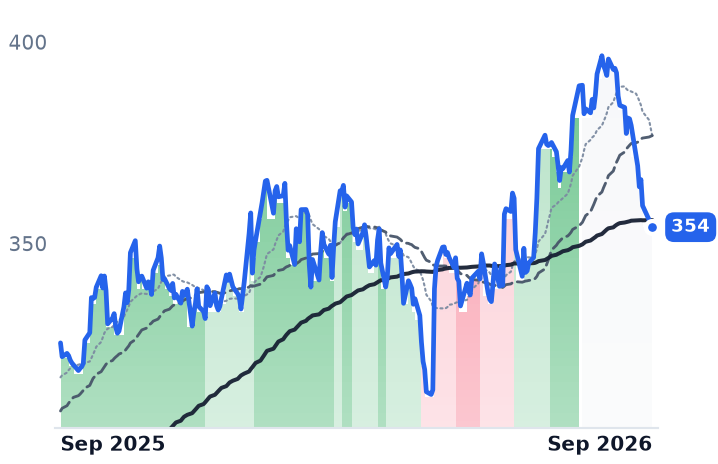
Shares closed at $152.49 on September 10, 36% below the April 15 high of $238.42, having fallen hardest between August 17 and 25 on unusually heavy volume. Forward earnings guidance rose across that span; the forward price-to-earnings multiple fell to 32.2x on consensus 2026 earnings of $4.74, against roughly 46x in early May. The de-rating is almost entirely multiple compression, and it is sector-wide — on September 10 Piper Sandler split its advanced-nuclear coverage, rating Oklo a buy and X-Energy a sell, and Oklo, NuScale and X-Energy each fell about 5%.
The other company filed under the same fuel-and-fabrication heading shows what the market is actually repricing. Lightbridge, a 13-person Reston, Virginia developer of helically twisted metallic reactor fuel, has reported no revenue in any quarter since 2021. Its first-half net loss widened to $12.1m from $8.3m as research spending doubled, diluted shares rose 43.3% year over year to 31.9m, and it held $237.5m of cash against a $258m market value — about $20m of implied value for the entire fuel program, and 0.98x book. Its calendar belongs to Idaho National Laboratory: samples came out of the Advanced Test Reactor on May 6 and must cool before examination begins later this year. Selection for the Department of Energy's Launch Pad program on August 31 did not stop the slide.
The verdict splits cleanly. BWXT's earned deterioration is margin mix — a lower-margin acquired segment carrying the growth — and that is worth something, but not a third of the company's value. The rest is the unwind of a narrative premium that priced microreactors and small modular reactors, sold off now on the same impulse that is marking down pre-revenue developers. What nothing in the numbers explains is why a business whose cost discipline improves its fee margin trades on the sentiment of companies that have no fees at all.
About 55% of second-half earnings fall in the December quarter, management said. A naval contractor spends the year proving it can spend less; the proof arrives in the last three months.