

Diesel Rose $2 a Gallon; International Paper's Price Increase Waits Until 2027
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Containerboard producers spent 2026 announcing the largest price increases on record, and the fuel that hauls the boxes repriced faster than the price publication that pays them. Only $100 a ton of roughly $240 in announced 2026 increases has been recognized by Fastmarkets RISI, and the third round — effective September 1 — lands mostly in the first half of 2027. Diesel took three weeks.
The two protagonists are not in the same position. International Paper's June quarter showed revenue down 11.3% and an operating margin of 0.7%, and guidance came down; at 25.0x this year's consensus earnings, the shares are voting on a 2027 estimate that requires profit to more than double. Packaging Corporation of America told the same September conference that it is running full and cannot make additional tons — and de-rated anyway, from 30.5x trailing earnings against roughly 25x at the end of 2024.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
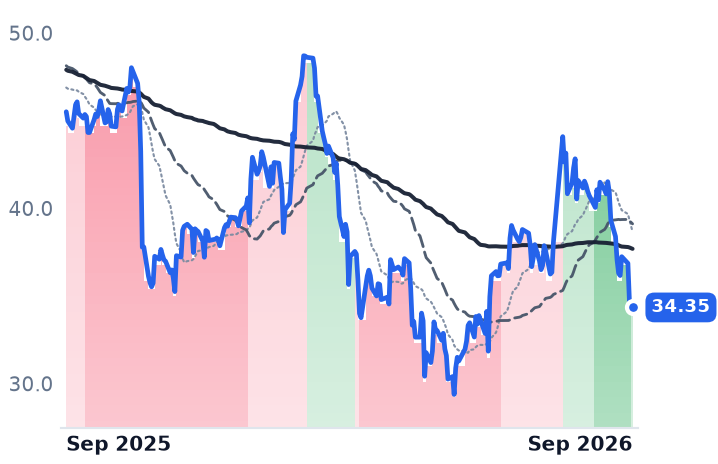
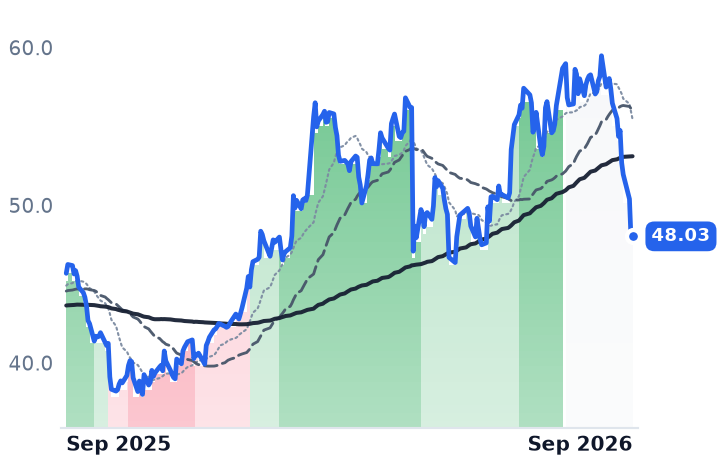
IP | International Paper | Corrugated & Containerboard | 🌱 Emerging Bull | −16.9% | −24.5% |
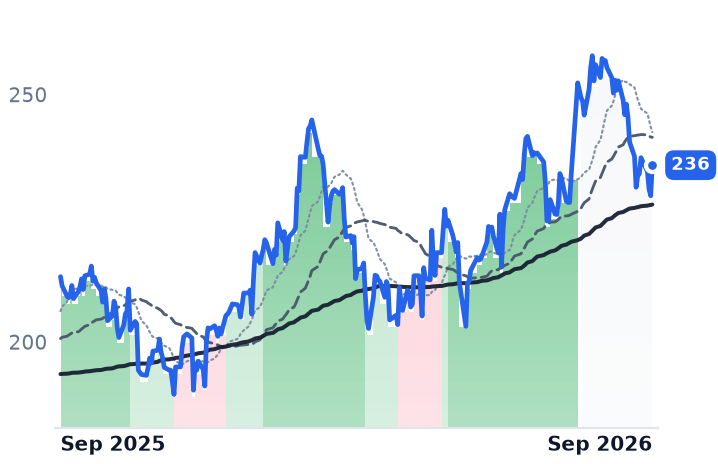
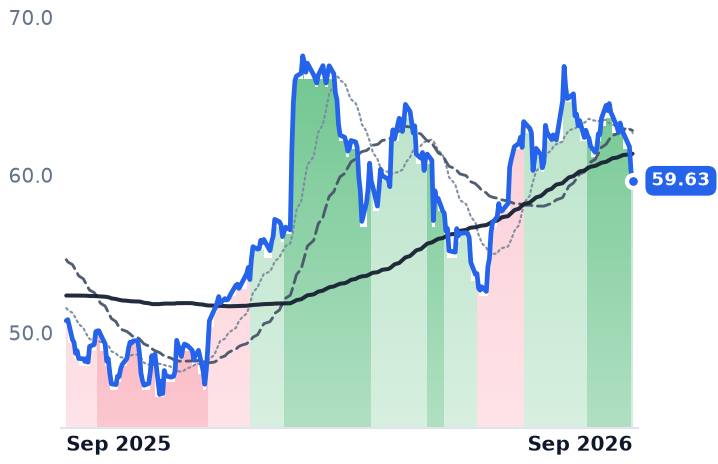
PKG | Packaging Corporation of America | Corrugated & Containerboard | 🟢 Cont. Bull | −8.2% | +10.6% |
| Compared against · context, not the story | |||||
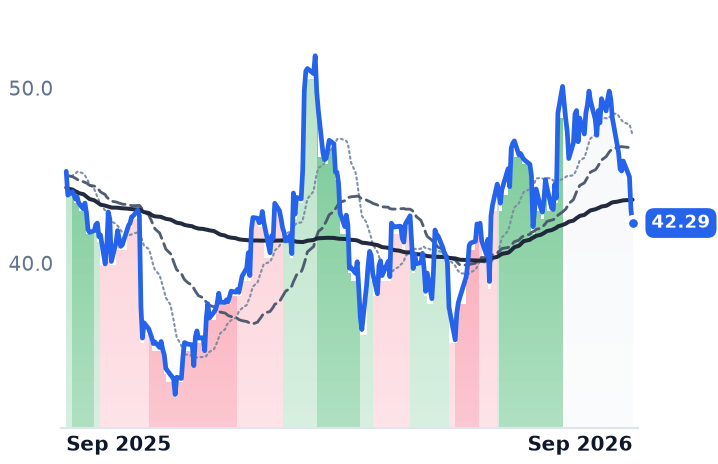
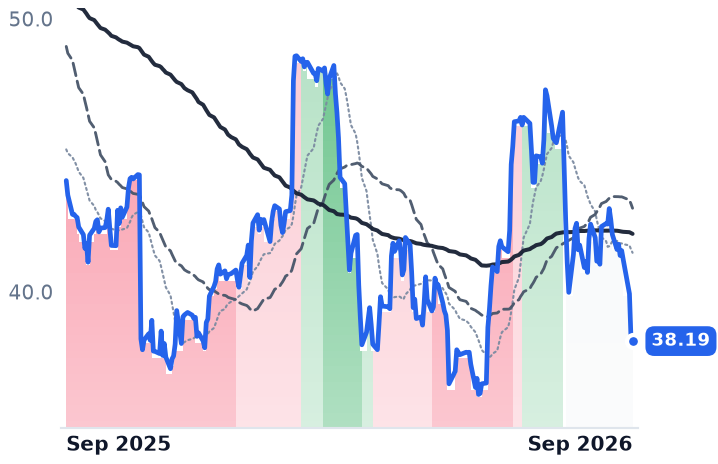
SW | Smurfit Westrock | Corrugated & Containerboard | 🌱 Emerging Bull | −13.8% | −6.5% |
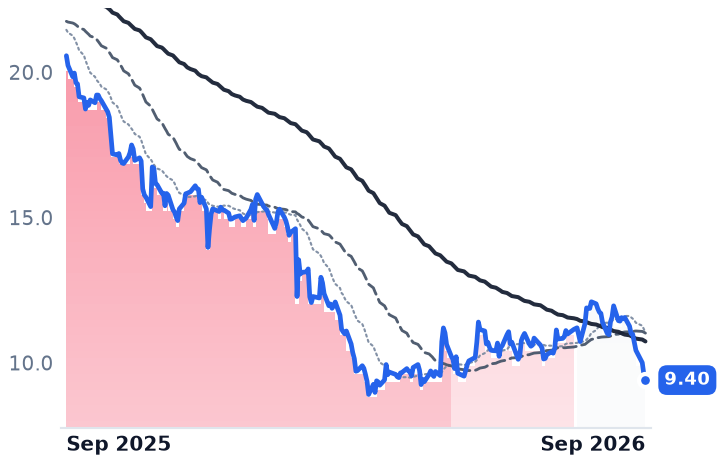
GPK | Graphic Packaging | Corrugated & Containerboard | 🔴 Cont. Bear | −19.9% | −54.3% |
SON | Sonoco Products | Consumer Packaging & Foodservice | 🟢 Cont. Bull | −17.2% | +5.1% |
SLGN | Silgan | Flexible & Rigid Plastic Packaging | 🔴 Cont. Bear | −6.2% | −13.3% |
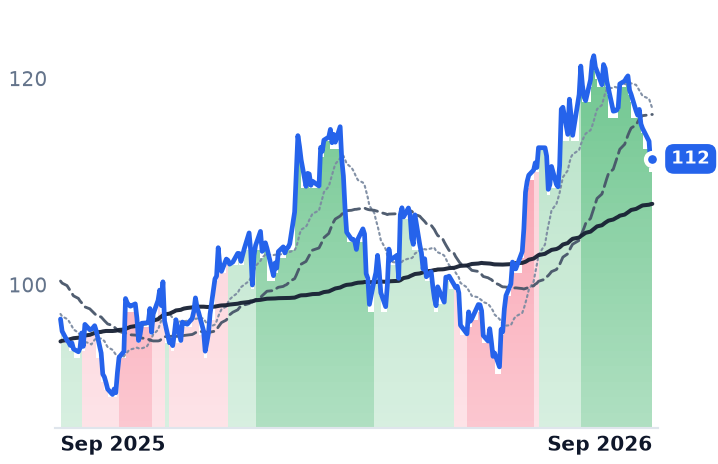
CCK | Crown | Metal Beverage Cans | 🟢 Cont. Bull | −7.2% | +16.1% |
BALL | Ball | Metal Beverage Cans | 🟢 Cont. Bull | −4.6% | +17.5% |
AMCR | Amcor | Flexible & Rigid Plastic Packaging | 🌱 Emerging Bull | −9.1% | +4.2% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.9% | +16.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IP | $18.2B | n/m | 25.0x | 0.8x | 0.7x | 2.7x | 2.7x | n/m | 2.7% |
PKG | $21.0B | 30.5x | 22.5x | 2.2x | 2.1x | 11.0x | 10.4x | 13.5x | 3.5% |
SW | $22.4B | 48.4x | 19.3x | 0.8x | 0.7x | 4.2x | 3.9x | 8.7x | 4.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GPK | $2.8B | 14.3x | 13.2x | 0.3x | 0.3x | 2.1x | 2.1x | 9.1x | 6.8% |
SON | $4.6B | 4.5x | 8.0x | 0.6x | 0.6x | 2.9x | 3.0x | 6.1x | 5.8% |
SLGN | $3.9B | 13.6x | 9.6x | 0.6x | 0.6x | 3.4x | 3.2x | 8.4x | 7.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCK | $10.7B | 15.0x | 11.8x | 0.8x | 0.8x | 4.7x | 4.5x | 8.0x | 9.1% |
BALL | $14.7B | 15.7x | 13.8x | 1.1x | 1.0x | 6.9x | 6.5x | 10.2x | 4.1% |
AMCR | $17.0B | 25.1x | 9.2x | 0.8x | 0.7x | 4.3x | 4.1x | 10.3x | 7.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
IP | Revenue | +0.3% | +5.6% | +1.1% |
| EPS | +470.6% | +119.0% | +16.1% | |
PKG | Revenue | +10.9% | +7.1% | +3.1% |
| EPS | +5.8% | +27.6% | +6.1% | |
SW | Revenue | +3.1% | +5.8% | +2.3% |
| EPS | −7.7% | +56.2% | +13.8% | |
GPK | Revenue | +0.9% | +2.1% | +2.0% |
| EPS | −61.5% | +55.4% | +11.3% | |
SON | Revenue | −2.2% | +2.1% | +2.1% |
| EPS | +2.8% | +10.1% | +9.9% | |
SLGN | Revenue | +6.0% | +2.1% | +3.0% |
| EPS | +3.2% | +7.3% | +8.4% | |
CCK | Revenue | +8.2% | +2.3% | +1.2% |
| EPS | +4.6% | +8.6% | +7.8% | |
BALL | Revenue | +12.1% | +3.4% | +2.9% |
| EPS | +12.3% | +12.8% | +12.1% | |
AMCR | Revenue | +53.3% | +3.1% | +1.0% |
| EPS | +9.9% | +8.9% | +7.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
At the Jefferies Global Industrials Conference on September 10, International Paper's chief executive put a number on the week's oil move: diesel, Andy Silvernail said, has risen about $2.00 a gallon in six months. For a company that makes linerboard and medium and converts them into corrugated boxes, that is a headwind of $150m to $200m. He was speaking on the day his shares bottomed, after a 6.0% single-session fall on September 9 — the session Brent crude jumped to $100.72 on Middle East fighting and US diesel set a record at $5.94 a gallon, on its way past $6 by September 11.
That is the whole of the story, and it is a timing story. A containerboard maker's revenue is set by contracts indexed to a published third-party benchmark, with one to three months of lag before an announced increase reaches an invoice — and only if the publisher validates it. Diesel has no lag. So the industry's strongest pricing year in memory and its worst input shock in years are settling on two different clocks, and the shares are marking the fast one.
The slow leg
The price side is real and documented. Roughly 3.9m tons — about 10% of US containerboard capacity — was permanently retired between February 2025 and March 2026, International Paper's Red River, Riceboro and Savannah mills a large share of it. The industry operating rate reached nearly 95% in the second quarter against 93% in the first. Producers opened a third increase in July, the largest on record: PCA at $140 a ton effective September 1, International Paper at $80 and Smurfit Westrock at $100.
Collecting it is another matter. Fastmarkets RISI has recognized a net increase of only $100 a ton across the year's first two rounds, and North American containerboard was flat in August for the second consecutive month. Buyers are contesting the third: the Association of Independent Corrugated Converters opposed it on August 10, arguing three hikes in five months are not justified by raw-material costs. Anthony Smurfit, chief executive of Smurfit Westrock, the third large North American producer, described the lag plainly on the July 29 call: "the full effect of that is going to be felt in quarter 3 and quarter 4 and any other pricing initiatives will be felt either very late quarter 4 or into quarter 1 of next year."
The fast leg, and what it has already eaten
"The pricing up to now has really been eaten by inflation," Silvernail told investors on July 30. "If you look at what's happened with OCC, energy, diesel, freight, you name it... it's unfortunately really eaten every bit of that pricing up until today." Smurfit Westrock's finance chief Ken Bowles said the same thing on July 29 — "freight costs globally represented a significant headwind, driven largely by higher fuel costs and shipping rates" — as the company's freight estimate climbed to $300m from $50m in April.
International Paper's June quarter is what that arithmetic produces: revenue down 11.3% to $6.00bn and operating income of $45m, a margin of 0.7% against 3.0% a year earlier. Full-year North American adjusted earnings before interest, tax, depreciation and amortization guidance came down to $2.35–2.45bn, the macro headwind estimate was tripled to about $150m, and the second-half volume assumption was cut to flat from up 1%. Demand is not the culprit: box volumes still grew 1.7% a day year over year.
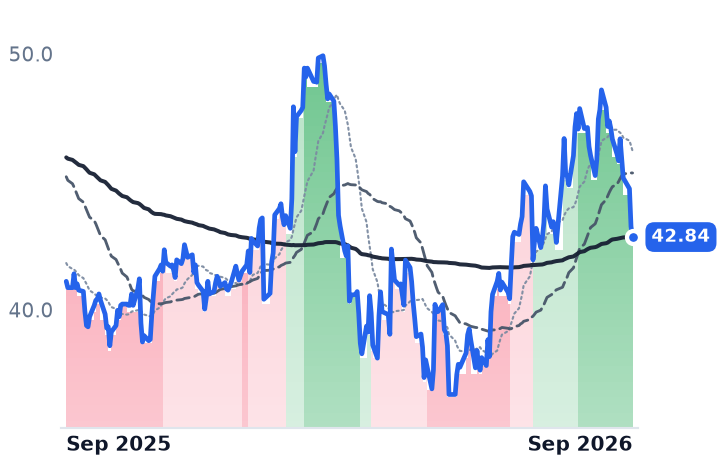
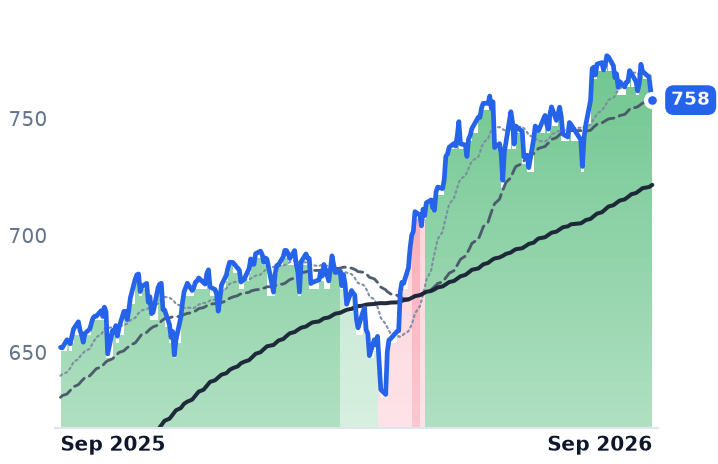
Packaging Corporation of America, the Illinois producer that converts most of its own tons into boxes, sits on the other side. It told the same Jefferies conference that containerboard markets remain "exceptionally tight," that it is running full and cannot produce additional tons, and guided the third quarter to higher price and mix as it implements the first increase and begins the second. It fell 10.8% between August 11 and September 10; International Paper fell 17.0% and Smurfit Westrock 13.0%, against 1.7% for the S&P 500 tracker. The September 9 session itself was broad — the index lost 0.48% — so the packaging complex was singled out.
What the businesses earn
International Paper's de-rating is earned on the earnings currently visible. Trailing multiples are unusable after 2025's $3.52bn net loss; on consensus the shares trade at 25.0x this year's $1.37 and 11.4x next year's $3.00. The fall is a vote against the 2027 line, which requires profit to more than double while the company spins off its European packaging business, still targeted for early 2027.
PCA's is harder to justify from the business. It is de-rating from a full price — 30.5x trailing earnings against roughly 25x at the end of 2024 and 24x at the end of 2025, on lower earnings, and 22.5x forward, the most expensive of the three. Smurfit Westrock is the cheapest, at 8.7x trailing enterprise value to EBITDA and 1.4x book, having cut North American corrugated volumes 4.5% deliberately and shrunk its loss-making plant count from about 80 to about 20. None of the three reported a demand collapse. What they reported was a cost line that moved before the price line could.
The industry's decade-long argument is that price increases pay for input inflation. This year has tested the sequencing rather than the logic, and the sequencing failed: the third round is the largest ever announced, and the only meter that decides whether it happened has now printed no change for two straight months.