

Chemed's Medicare Cap Charge Fell to $0.5m; Option Care's Gross Margin Rose to 18.5%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Four companies file under the same home health and hospice heading, and not one of them is paid the way another is. Chemed's hospice arm collects a flat Medicare per-day rate; Option Care Health buys infusion drugs and is reimbursed on a spread over what it paid for them. Both just reported quarters where profit grew faster than revenue, for reasons that share nothing.
Chemed's June-quarter operating income rose 31% on revenue up 8.8%, helped by an average length of stay that fell to 101.2 days from 137.1, which relieved the aggregate Medicare cap. Option Care's gross profit grew 5.7% on revenue up 1.9% — its first quarter in five with profit dollars outgrowing sales, as the Stelara biosimilar step-down annualized out.
The July rally on the proposed 2027 home-health rule treated them as one trade. Since then Aveanna alone has risen; the other three fell.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
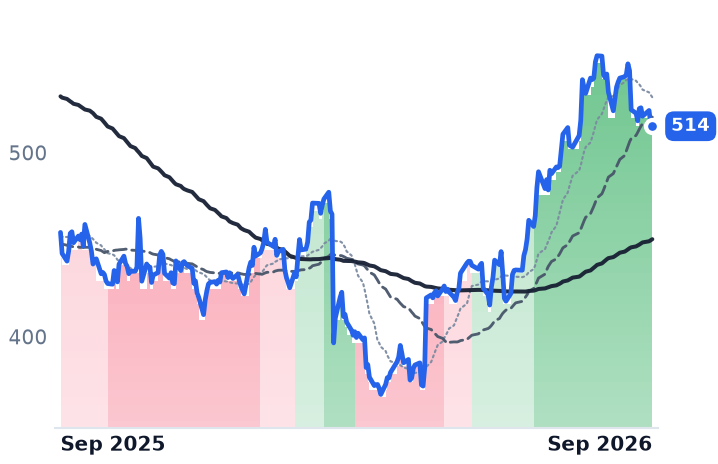
CHE | Chemed | Home Health & Hospice | 🌱 Emerging Bull | −4.9% | +12.6% |
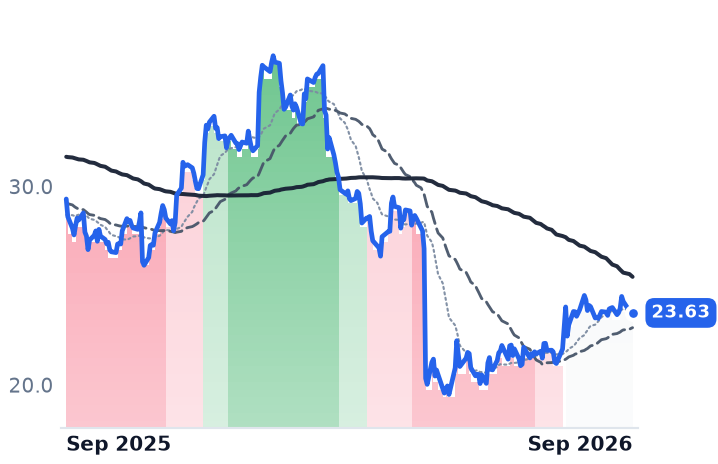
OPCH | Option Care Health | Home Health & Hospice | 🔴 Cont. Bear | −0.5% | −19.5% |
| Compared against · context, not the story | |||||
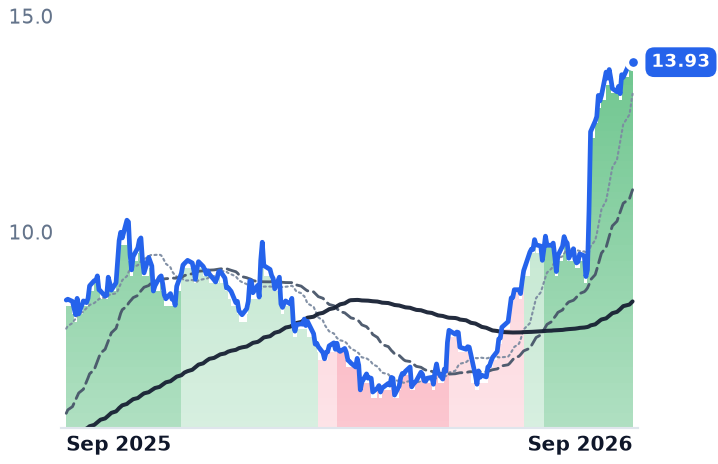
AVAH | Aveanna Healthcare | Home Health & Hospice | 🟢 Cont. Bull | +52.7% | +65.4% |
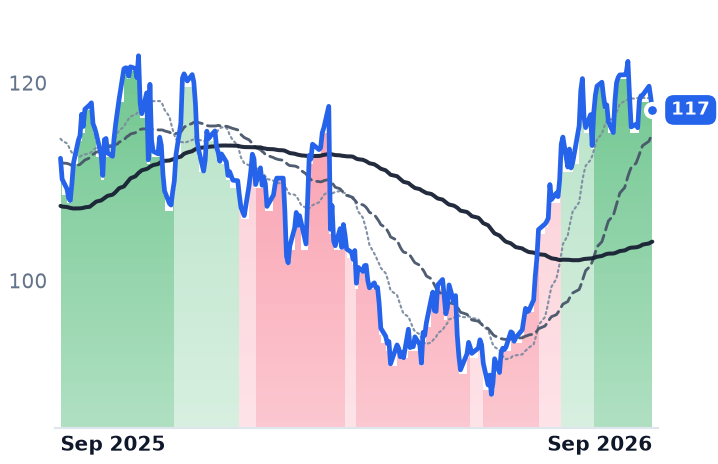
ADUS | Addus HomeCare | Home Health & Hospice | 🌱 Emerging Bull | −0.2% | +4.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CHE | $6.7B | 25.8x | 20.2x | 2.6x | 2.5x | 8.5x | 8.1x | 16.2x | 4.8% |
OPCH | $3.5B | 17.8x | 12.6x | 0.6x | 0.6x | 3.4x | 3.4x | 11.1x | 9.8% |
AVAH | $3.0B | 10.4x | 17.0x | 1.2x | 1.1x | 3.6x | 3.5x | 14.8x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADUS | $2.2B | 20.9x | 16.8x | 1.5x | 1.5x | 4.6x | 4.5x | 13.3x | 6.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CHE | Revenue | +6.7% | +6.0% | +5.9% |
| EPS | +15.2% | +7.8% | +6.6% | |
OPCH | Revenue | +1.9% | +6.6% | +8.2% |
| EPS | +8.7% | +10.8% | +11.4% | |
AVAH | Revenue | +20.3% | +11.3% | +7.5% |
| EPS | +4822.7% | +40.7% | +10.0% | |
ADUS | Revenue | +7.1% | +4.9% | +4.6% |
| EPS | +13.7% | +6.7% | +6.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Chemed's hospice arm is paid a flat Medicare rate for each day a patient is on service, whatever that day's care actually costs. In the June quarter its patients stayed less time — an average of 101.2 days against 137.1 a year earlier — and the accrual Chemed books against the aggregate per-beneficiary cap, Medicare's ceiling on average payment per patient, fell to $0.5m from $16.4m.
That swing is most of the reason operating income rose 31% on revenue up 8.8%, and it explains nothing whatsoever about the companies filed beside it. Four businesses still trade under the home health and hospice heading, and each is paid by a different machine: a hospice per-diem, state Medicaid personal-care rates, a California pediatric nursing rate, and a spread over the acquisition cost of infusion drugs. CMS's proposed calendar-2027 home health payment rule, issued 1 July with an estimated 2.4% aggregate increase, lifted all of them in late July. They have since gone separate ways: over the past month Aveanna Healthcare rose 52.7% while Option Care Health fell 2.7%, Chemed 5.2% and Addus HomeCare 1.1%. Over three months the spread runs from Aveanna's 99% to Option Care's 13.7%.
Chemed: shorter stays, and a plumbing arm Google is squeezing
VITAS, Chemed's hospice and palliative care business, admitted 19,125 patients in the quarter, up 9%, and carried an average daily census of 23,687, up 6.1%. Adjusted earnings of $6.06 a share beat consensus of $5.60, and management raised full-year census growth guidance to 5.75-6.25% and consolidated adjusted earnings to $25.00-25.75 a share, a midpoint 7.8% above last year. "VITAS has never been in a better position to take advantage of growth opportunities," VITAS president and chief executive Joel L. Wherley told investors on the 29 July call. "We have put the difficulties of 2025 behind us."
The buyback is not doing the work. Reported diluted earnings per share rose 43.7% to $5.13, but diluted shares fell 8.1% — roughly eight points of the gain — leaving the remainder to the 29% rise in net income.
Roto-Rooter, the plumbing and drain-cleaning franchise bolted to the hospice business, is the drag, and its problem is a search engine. Adjusted earnings before interest, taxes, depreciation and amortization were flat at $48.5m with margin down 77 basis points; total sales leads fell 1.6% and free leads fell 13.1%. "Google hates the idea of free leads," chief executive Kevin J. McNamara said on the same call. "They have systematically tried to drive their users away from the free aspects of service providers."
Option Care: paid on the spread, not the patient
Option Care Health, the largest national provider of home and alternate-site infusion therapy, delivers immunoglobulin, nutrition and chronic inflammatory therapies in patients' homes with nurses attached. Its economics are a distributor's: gross margin fell from 22.8% in 2023 to 18.1% last year, and 2025 revenue grew 13.0% to $5.65bn while gross profit grew 0.7%. Biosimilar conversion in the chronic inflammatory portfolio repriced the drug while volumes kept rising.
June quarter revenue rose 1.9% to $1.442bn and gross profit 5.7% to $267.3m, margin recovering to 18.53% from 17.85% — the first quarter in five in which profit dollars outgrew sales. "Stelara and related biosimilars will represent less than 1% of 2026 company net revenue and gross profit," chief financial officer Meenal Anil Sethna said on 29 July; the chronic inflammatory headwind still embedded in guidance is about $55m of gross profit. The May guidance cut that took 26% off the shares in a session has not been recovered, and the shares are the only ones of the four that have not re-established an uptrend, the 50-day and 200-day averages tangled since late July. "We are not satisfied with our performance," chief executive John Charles Rademacher told investors.
Where they trade
Gross margins differ too widely here for sales multiples to compare, so price against gross profit does the work: Option Care at 3.42x trailing is the cheapest of the four and Chemed at 8.51x the dearest, with Addus at 4.63x and Aveanna at 3.63x. Option Care fetches 12.6x forward earnings against 17.8x trailing and yields 9.8% on trailing free cash flow; Chemed 20.2x forward against 25.8x trailing, still short of the roughly 32.7x its 2024 high implied. Addus, whose personal-care revenue comes mostly from state Medicaid programs, grew 8.0% in the quarter after running near 25% through 2025 and trades at 16.8x forward. Aveanna's revenue rose 13.7% but gross margin fell to 32.6% from 35.8%; its 13 August guidance raise and California's first pediatric private-duty-nursing rate increase since July 2018, effective 1 January 2027, are what moved the stock.
What the businesses earn
Chemed's quarter is operating, not financial engineering — but the cap cushion came from a mix shift toward shorter stays, and mix reverses. Option Care's reacceleration is one quarter old and priced against a top line consensus has growing 1.9% this year; the cheapness is real and so is the flatness behind it. What July's rally assumed — that one federal rule moves this group — has not survived August. Anyone holding the four is holding four payers.
CMS finalized the 2027 hospice rate at a 2.3% update, trimmed from the 2.4% it proposed in April. VITAS's new per-diem takes effect on 1 October; in Florida, where the cap cushion it just rebuilt sits, management says the increase is 1.0%.