

Entergy's Net Income Rose 3.4% and Its Share Count 4.6%, So Per-Share Earnings Fell
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Entergy's Louisiana build is working the way regulation intends, and shareholders got less of it than a year ago. The company is funding a $67bn five-year capital plan with a $7bn equity program, roughly $4.1bn of it settled or contracted by 30 June, and the shares are arriving faster than the plants they pay for. Industrial sales grew 10% in the June quarter; adjusted earnings per share still slipped to $1.03. Management affirmed 2026 guidance of $4.25 to $4.45, so the case now rests on timing rather than demand.
The wider group's thirty-day decline is mostly one California name — PG&E's wildfire-liability collapse — which has no data-center content at all.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ETR | Entergy | Vertically Integrated Utilities | 🟢 Cont. Bull | −1.5% | +19.2% |
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −3.9% | +11.2% |
| Compared against · context, not the story | |||||
PCG | PG&E | Vertically Integrated Utilities | ⚠️ Emerging Bear | −20.0% | −11.2% |
NEE | NextEra Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −2.9% | +17.8% |
SO | The Southern | Vertically Integrated Utilities | 🟢 Cont. Bull | −4.6% | −3.0% |
DUK | Duke Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −3.0% | −0.3% |
AEP | American Electric Power | Vertically Integrated Utilities | ⚠️ Emerging Bear | −0.5% | +15.5% |
PPL | PPL | Transmission & Distribution Only | ⚠️ Emerging Bear | −3.2% | −3.7% |
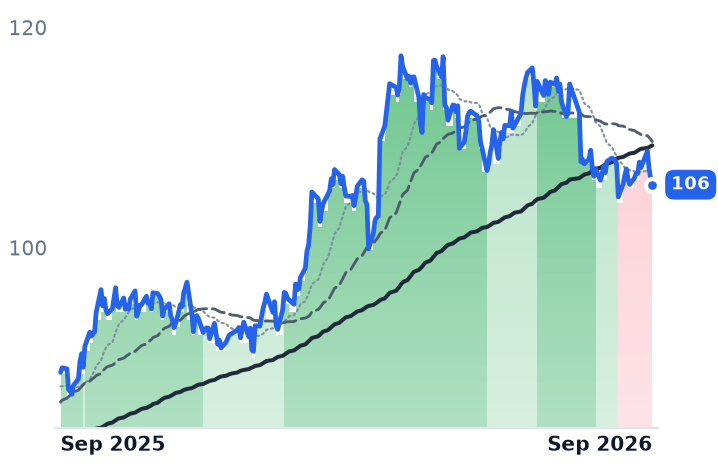
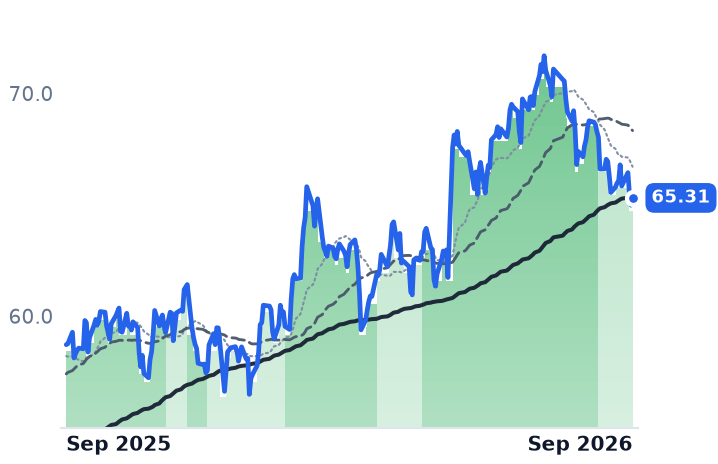
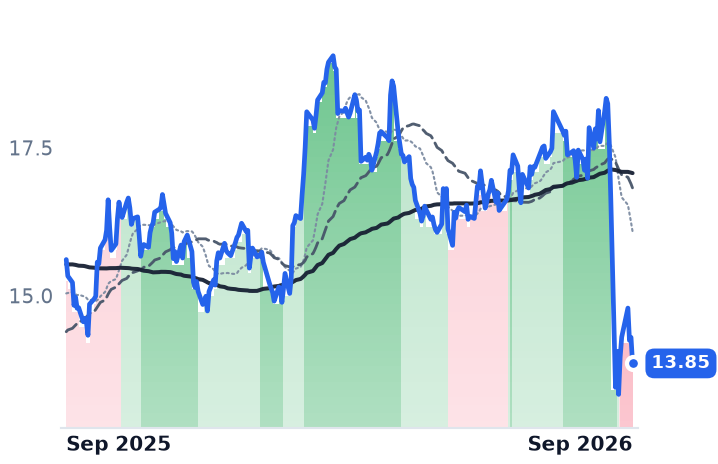
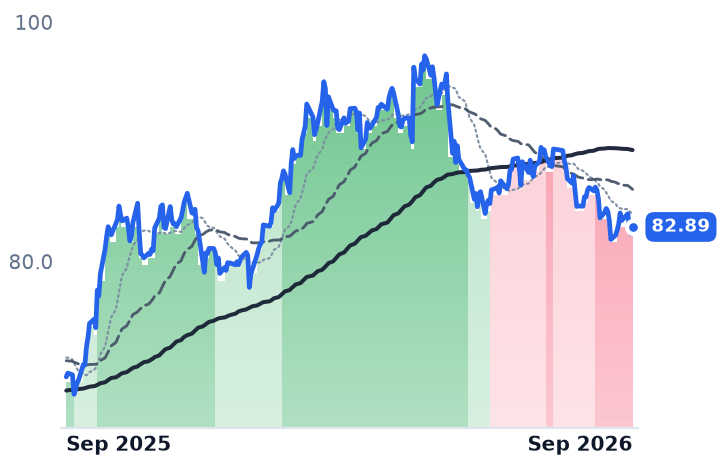
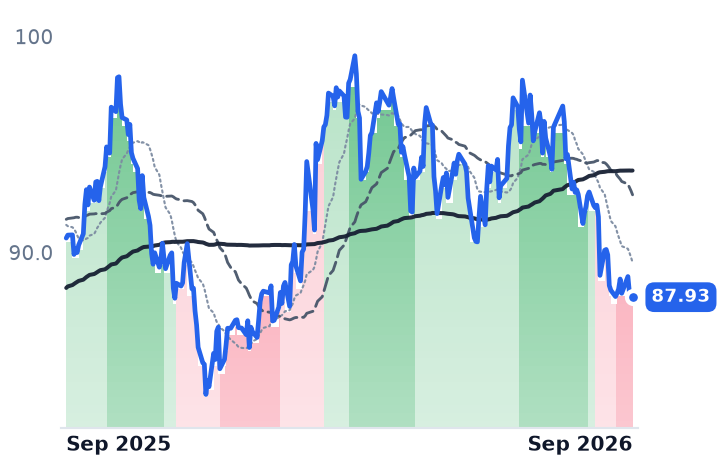
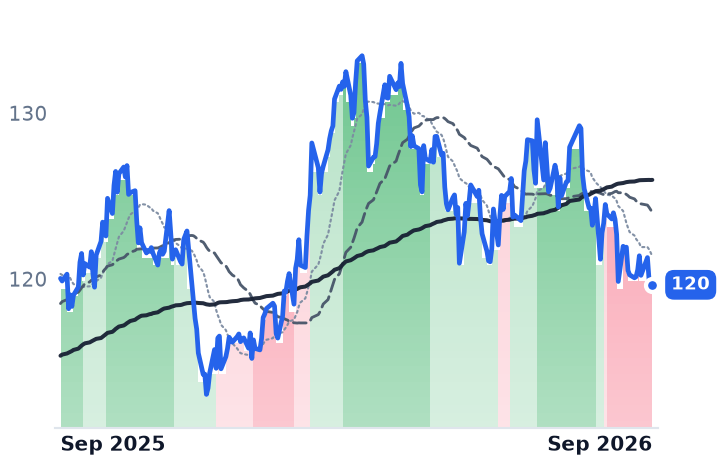
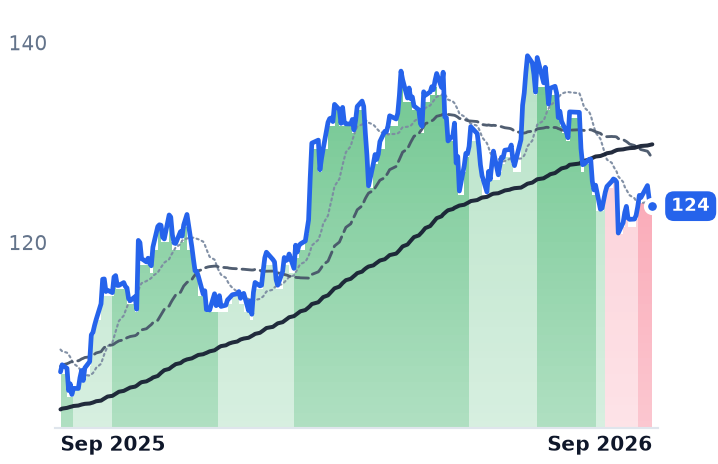
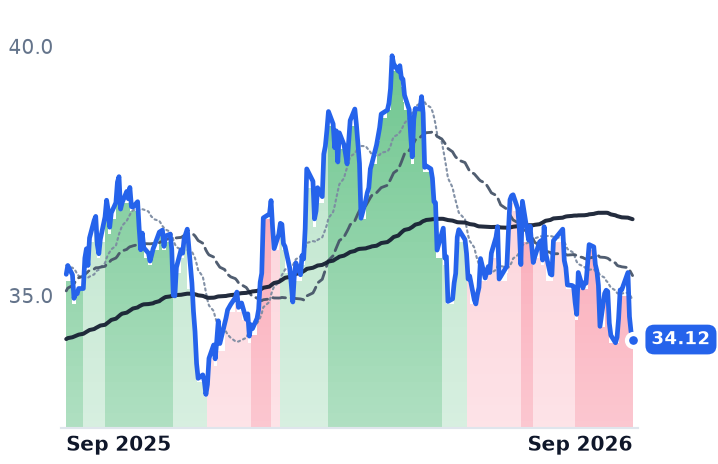
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETR | $49.3B | 26.7x | 24.0x | 3.7x | 3.5x | 9.4x | 9.1x | 14.3x | -6.4% |
D | $57.4B | 22.6x | 18.2x | 3.1x | 3.1x | 6.4x | 6.4x | 15.0x | -11.9% |
PCG | $37.7B | 10.2x | 8.5x | 1.5x | 1.4x | 2.6x | 2.6x | 9.6x | -11.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEE | $172.8B | 18.5x | 20.6x | 6.0x | 5.6x | 8.3x | 7.8x | 15.8x | -5.9% |
SO | $106.6B | 22.2x | 20.2x | 3.5x | 3.5x | 8.1x | 8.0x | 12.7x | 2.4% |
DUK | $93.7B | 18.1x | 17.9x | 2.8x | 2.8x | 4.1x | 4.1x | 11.4x | 1.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AEP | $67.8B | 21.4x | 19.5x | 3.0x | 2.9x | 6.1x | 5.9x | 14.1x | 13.2% |
PPL | $25.9B | 27.1x | 17.6x | 3.6x | 2.7x | 10.5x | 7.7x | 13.7x | 1.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ETR | Revenue | +8.7% | +9.7% | +9.7% |
| EPS | +12.3% | +16.1% | +13.6% | |
D | Revenue | +13.7% | +6.5% | +5.8% |
| EPS | +5.0% | +6.3% | +7.0% | |
PCG | Revenue | +2.8% | +3.9% | +3.9% |
| EPS | +10.1% | +9.0% | +9.2% | |
NEE | Revenue | +9.4% | +9.7% | +8.9% |
| EPS | +9.0% | +9.0% | +8.5% | |
SO | Revenue | +7.7% | +5.5% | +6.1% |
| EPS | +6.8% | +7.5% | +9.2% | |
DUK | Revenue | +5.8% | +4.6% | +4.2% |
| EPS | +6.3% | +6.9% | +7.0% | |
AEP | Revenue | +9.5% | +5.9% | +7.6% |
| EPS | +7.9% | +7.6% | +10.6% | |
PPL | Revenue | +11.0% | +5.8% | +5.4% |
| EPS | +7.6% | +8.7% | +8.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Entergy reported higher net income for the June quarter and lower earnings per share, and the gap between those two facts is the equity it is issuing to build power plants for Meta. Net income rose 3.4% to $487.8m. Diluted shares rose 4.6%, to 466.3m, and adjusted earnings per share came in at $1.03 against $1.05 a year earlier.
That is the whole mechanism of a regulated utility compressed into one quarter. Entergy — the New Orleans company that serves about 3 million electricity customers across Arkansas, Louisiana, Mississippi and Texas — is not paid for megawatt-hours in any way its revenue line makes legible. Fuel and purchased power are largely passed through at no margin; earnings come from an allowed return on rate base, the depreciated capital a state commission has approved it to own. Data-center load reaches net income only after it becomes approved capital spending — and capital spending on this scale has to be funded. Entergy's five-year plan runs to $67bn, with $13.2bn of investment in 2026 rising to $16.8bn in 2027, supported by a $7bn equity program. About $4.1bn of that equity was already settled or contracted under forward sale agreements as of 30 June, against a consolidated debt-to-capital ratio of 65.2%.
Rate base grows; the denominator grows with it
The dilution is not new and not an accident. Full-year 2025 diluted shares averaged 450.2m against 431.6m in 2024. Industrial sales grew 10% year on year in the June quarter as new projects ramped, revenue growth nonetheless decelerated from 12.0% in the March quarter to 5.9%, and operating income was slightly lower than a year ago at $834.7m. Entergy affirmed adjusted earnings guidance of $4.25 to $4.45 for 2026 and told investors the majority of the year-on-year increase lands in the fourth quarter. "We remain firmly on track to meet our 2026 adjusted EPS guidance and longer-term outlooks," chair and chief executive Drew Marsh said on the July 29 call.
What Louisiana decides in December
The demand side is the least contested part. Marsh put the pipeline at "seven to 12 gigawatts of hyperscale data center potential," plus three to five gigawatts of traditional industrial interest — a range, not a contract book. What is contracted is Meta's Hyperion campus in Richland Parish, under an electric service agreement currently running 15 years with a proposal to extend to 20, which Entergy says is structured so that Meta pays full cost of service and delivers roughly $2bn of customer savings over twenty years on top of $650m announced earlier.
Who carries the risk if the load does not show up is what the Louisiana Public Service Commission votes on in December. It agreed 4-1 in April to fast-track seven more gas plants for the Meta campus — the first application under the state's new "Lightning Amendment" — on top of three units totalling 2.26 gigawatts approved in August 2025. Critics, including the Union of Concerned Scientists, argue the framework leaves ratepayers exposed to large portions of data-center-triggered system costs. Entergy's answer is a voluntary standard: "The Fair Share Plus pledge really kind of originated with our first customer in Mississippi, with AWS," Marsh said on the same call. Virginia codified the equivalent instead — its new large-load class, effective 1 January 2027, requires customers above 25 megawatts to pay at least 85% of contracted transmission and distribution demand and 60% of generation demand. Dominion, the incumbent there, no longer offers an independent read on any of it: since NextEra agreed in May to buy it all-stock at 0.8138 NextEra shares, it trades within about 3% of deal terms.
What the de-rating is doing
Entergy's shares are flat over thirty days and down 3.8% over three months, up 17.7% over twelve; the 50-day average crossed below the 200-day on 21 August. The multiple has come in from 29.9x trailing earnings in May to 26.7x trailing and 24.0x forward — still the dearest of the large regulated names, against Dominion's 18.2x forward. With the 30-year Treasury at 5.25% against a 12-month average of 4.89% and authorized returns near 9.8%, the spread that makes a utility a bond substitute has narrowed for everyone.
The group-wide bearish reading is mostly one name and one state. Across the eight large load-growth utilities the equal-weight thirty-day decline is 4.5%, but PG&E fell 19.0% in the 31 August session alone — its worst since March 2020 — after California lawmakers amended Senate Bill 492 without the wildfire liability protections investors expected. Excluding it, the group is down 2.5% and one member is higher.
So the de-rating is doing rational work rather than opening a gap. Entergy's business is delivering what it promised on the load side and converting it into rate base through a formula rate plan that admits each new generator into rates on entering service. What nothing in the quarter yet establishes is that the conversion reaches a shareholder: net income is growing at low single digits while the share count grows faster, and consensus asks for 16% per-share growth in 2027 to make the current price work. One number that would settle it — Entergy Louisiana's currently authorized return on equity — is not stated in the commission's published formula-rate schedules.
The Cottonwood plant Entergy acquired is available now; the customer arrival window management describes is years out. December decides seven more plants on the same bet.