

nCino Has Moved 48% of Contract Value Off Software Seats and Onto Bank Assets
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two companies filed under the same vertical software heading are paid by mechanisms neither calls software. nCino's renewals now step up at signing and then scale with the customer bank's assets; Procore's annual fee is set by the dollar value of construction its customer runs through the platform. The two indexes point opposite ways.
Private nonresidential construction spending fell 4.7% year over year in June and the Dodge Momentum Index slipped to 282.0 in August, while nCino's subscription revenue excluding mortgage accelerated to 12% growth. Procore's margins have inflected to a first GAAP operating profit, but at 6.62x forward gross profit it is cheaper than the 7.96x it carried in early May. nCino's earnings lens and its gross-profit lens flatly disagree, and that disagreement is the story.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
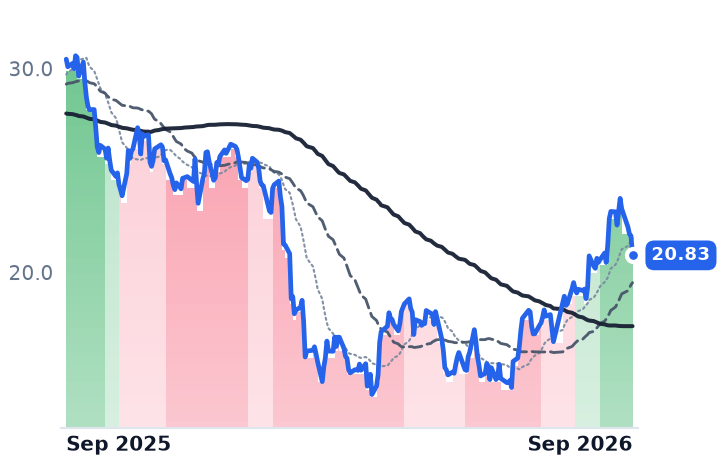
NCNO | nCino | Financial Services Software | 🌱 Emerging Bull | +11.4% | −31.6% |
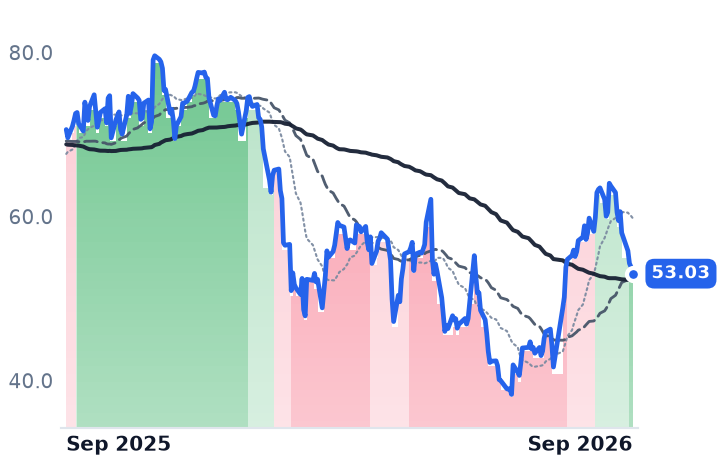
PCOR | Procore Technologies | Specialized Enterprise Solutions | 🔴 Cont. Bear | −7.3% | −24.9% |
| Compared against · context, not the story | |||||
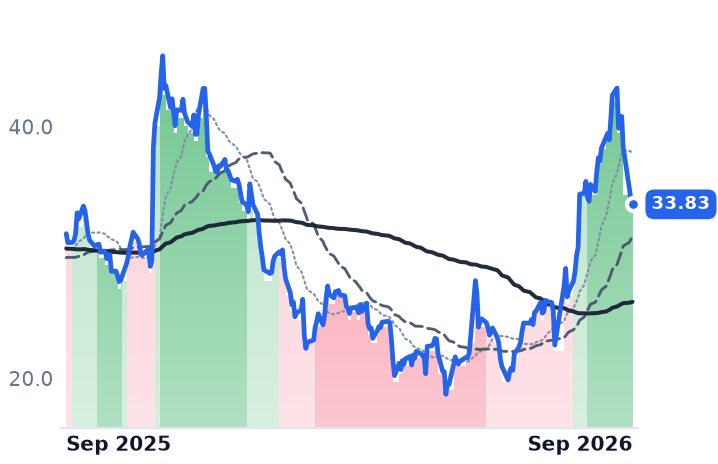
APPN | Appian | Low-Code & Process Automation | 🟢 Cont. Bull | −1.7% | +7.4% |
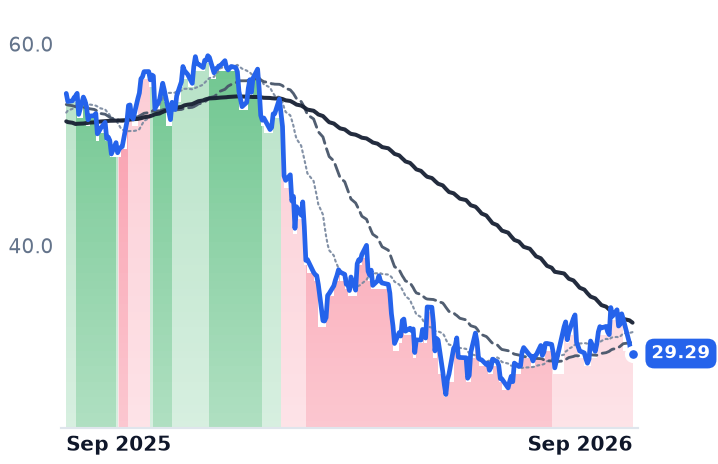
BL | BlackLine | Financial Services Software | 🔴 Cont. Bear | +3.4% | −46.8% |
FRSH | Freshworks | Security & Compliance | 🌱 Emerging Bull | +1.8% | −8.2% |
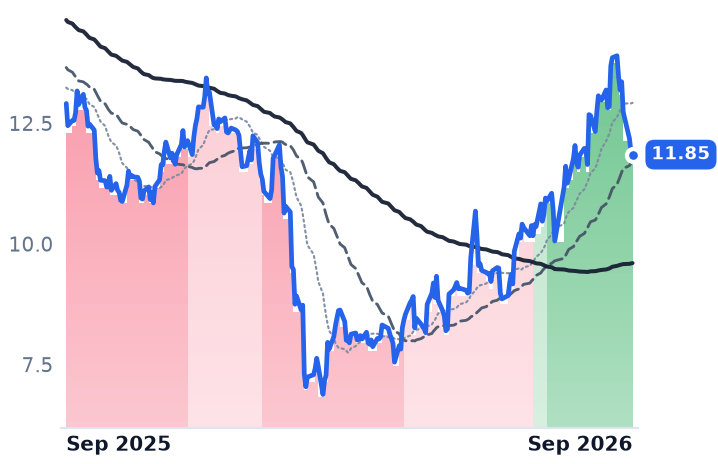
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NCNO | $2.3B | 67.3x | 15.9x | 3.7x | 3.5x | 6.0x | 5.7x | 30.8x | 5.8% |
PCOR | $8.0B | n/m | 31.5x | 5.6x | 5.3x | 7.0x | 6.6x | 125.2x | 3.7% |
APPN | $2.5B | n/m | 31.7x | 3.2x | 3.0x | 4.4x | 4.1x | 110.1x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BL | $1.7B | 48.7x | 11.5x | 2.3x | 2.2x | 3.0x | 2.9x | 21.2x | 10.1% |
FRSH | $3.3B | 18.1x | 17.7x | 3.6x | 3.4x | 4.3x | 4.0x | 36.2x | 7.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NCNO | Revenue | +9.8% | +9.0% | +8.5% |
| EPS | +25.2% | +44.5% | +20.0% | |
PCOR | Revenue | +15.2% | +13.8% | +14.3% |
| EPS | +24.2% | +46.1% | +20.1% | |
APPN | Revenue | +19.1% | +10.8% | +7.4% |
| EPS | +104.0% | +31.1% | +11.4% | |
BL | Revenue | +9.5% | +10.5% | +10.2% |
| EPS | +19.4% | +11.9% | +17.3% | |
FRSH | Revenue | +15.6% | +14.2% | +15.6% |
| EPS | +5.4% | +24.5% | +19.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
nCino, which sells loan-origination, account-opening and compliance software to banks and credit unions, has spent a year rewriting how it charges. Instead of counting seats and modules, renewals now take a one-time price step of about 10% and then scale with the client's asset growth. Just under half the company's annual contract value has crossed over — 48%, up from 40% three months earlier, with 12 of its 20 largest American enterprise customers converted.
Procore, the construction-management platform that competes with Autodesk Construction Cloud and Oracle Aconex, never sold seats at all: it charges an upfront annual fee per product based on the customer's Annual Construction Volume — the aggregate dollar value of work across that customer's projects — with unlimited users, support and storage included. Both companies have therefore handed their growth rate to someone else's activity: nCino's to bank balance sheets and mortgage volumes, Procore's to the dollar value of buildings going up. The meters that matter are construction planning and weekly mortgage applications, and they currently point in opposite directions.
The bank index is working; the mortgage index is not
nCino's July-quarter revenue was $161.0m, up 8.2%, with subscription revenue of $143.5m up 10%. Strip out mortgage and subscription growth accelerated to 12%; United States mortgage revenue of $20.6m fell 1%, and management guided it down again, to $20m this quarter and $18.5m next, blaming higher-for-longer rates and churn among independent mortgage banks. That guidance has since hardened into fact: the Mortgage Bankers Association reported applications down 2.7% in the week ending 4 September, with its refinance index 25% below a year earlier and the 30-year fixed rate at 6.85%, the highest since June 2025.
The rest of the business is where the repricing lands. Gross margin reached 62.6% from 59.2% a year earlier, operating margin swung to +8.5% from −6.2%, and free cash flow of $34.0m rose 170%. "We are no longer trying to convince prospective customers that we can lead the transition to agentic-AI-powered banking. We're doing it," chief executive Sean Desmond told investors on the August 25 call. Full-year revenue guidance of $644m–$647m still implies single-digit growth, and consensus carries 8.5% into the following year.
The construction index is contracting
Procore's June-quarter revenue was $375.2m, up 15.8%, the fourth straight quarter in a narrow band from 14.5%. Gross margin held near 80%, operating margin turned positive at 1.2% against −9.3% a year earlier, and net income of $16.9m replaced a $21.1m loss. "Our outstanding Q2 results demonstrate the continued value our platform provides to the construction industry," chief executive Ajei Gopal said on 29 July, alongside full-year guidance of $1,510m–$1,514m — about 14% growth, slower than the quarter just reported. The order book grows faster than revenue, but management told analysts the two rates will converge over three to four quarters as average contract duration stabilises, so part of that gap is contract length rather than demand.
Underneath sits the index itself. Private nonresidential construction spending fell 4.7% year over year in June and 7.9% excluding data centers, with manufacturing down 21.4%. The forward planning gauge is no better: the Dodge Momentum Index slipped 0.4% in August to 282.0, commercial planning down 3.0%, and it leads nonresidential spending by twelve to eighteen months.
What the shares did
Procore rose 67% from its 25 June low to a 27 August peak of $64.05 and nCino 65% into early September; both have since given back about 12% in six sessions, with no company news at either. They fell in step with BlackLine, Freshworks and Appian — close-automation, seat-priced support software and low-code, none of them indexed to a customer's volume — after a poor 30-year Treasury auction pushed yields up across the curve on 10 September. Rotation out of long-duration software is the likelier reading, not five company stories. Over twelve months Procore is down 25% and nCino 31%.
The verdict
Procore earned its summer on margins, not on its index: with earnings still thin, price-to-gross-profit of 7.05x trailing and 6.62x forward sits below the 7.96x of early May, so the advance restored a multiple rather than created one. Its uplift lever requires customers to build more in a market whose non-data-center spending is shrinking. nCino's lever is self-help — a renewal step that arrives whether or not the customer grows — which is why its two valuation lenses disagree so violently: trailing price-to-earnings has collapsed from 348x in May to 67x as profits inflected, while price-to-gross-profit has risen to 5.97x from 5.52x over the same stretch. Earnings say it is re-rating downward; gross profit says it has re-rated up about a tenth while growing 8%. Both are true, and which one governs depends on whether the repricing outruns the mortgage drag.
More than half of nCino's contract value has yet to convert. After that, the rest of the story belongs to the banks and the builders.